How To Get Your Finances In Order After Bankruptcy

While experiencing bankruptcy is tragic and bouncing back is challenging, there are some strategies to get your monetary train on track.

1. COMMIT TO CHANGE

You are feeling isolated and helpless due to the recent loss of your assets, bank accounts, and primary source of income. Declaring bankruptcy can shake one’s confidence in many ways. However, you need to be reminded about the brighter things ahead. Is there any place to go to than up? The best thing that you can do now is to pick up the pieces and put them back together.

The first step is to make a strong commitment. Change your financial habits and be ready to perpetually follow through a plan.

2. ANALYZE THE CIRCUMSTANCE

You must analyze the overall financial circumstance that you are in, especially the events that led up to your downfall. Figure out the financial mistakes you made in the past and avoid repeating it in the future.

I have to admit that some setbacks are due to factors that are beyond your control (e.g., layoffs due to recession). While others are due to poor financial decisions. For instance, you became addicted to retail therapy and exhausted all your income on designer goods. You skipped out on emergency fund in favor of your fashion sprees. This is why you must come up with a plan to dig yourself out of the financial trap.
Image Credits: pixabay.com

Image Credits: pixabay.com

3. FIX YOUR BUDGET

A new budget will help you rebuild your wealth by placing some constraints on your spending. Treat this as a map that will guide you to your financial goals. Now, let us start with the income. It is most likely that you are left with a single source of income that pays a minimum amount. Search for other part-time jobs or additional streams of income that can aid your journey. Face the uphill battle with a realistic budget.

Find ways to ensure that you are spending less than you are earning. I know it is not easy at first but, you have to endure the tides. Cut the unnecessary spending that you can spot in your previous budget. Rather than purchasing a smaller flat, ask your friends or family if you can crash their homes and pay a “rent” for the meantime. Lastly, sell your mint condition items to earn more money on the side.

4. PAY OUTSTANDING DEBTS

Contrary to popular belief, bankruptcy will not dissolve all your debts. You are not entirely safe yet! Although many of your unsecured debts were discharged, other forms of debts may still be on hold. This includes child support and student debt.

This is why you must gather and organize your financial documents. Determine all your obligations and list them down. Then, figure out various arrangements to pay off each one.

5. KEEP THE FAITH

The graceful bamboo stands firm in a beautiful sunny day. But, it is not always sunshine and rainbows. As strong winds gush through the forest, the graceful bamboo sways with the breeze. Be pliant like a bamboo. Embrace the strong winds of life much like this graceful creature does!
Image Credits: pixabay.com

Image Credits: pixabay.com

No plan is entirely perfect and roadblocks are inevitable. Do your hardest to rebound from every setback and reverse the financial situation. The worst thing that you can do right now is to give up!
Sources: 1 & 2

Read More...

The Perils of Short-Term Business Loans

It’s almost inevitable that life will have the occasional financial pinch. Having to meet financial deadlines is not just reserved to everyday life bills. Many times business owners, especially small business owners, are faced with the pressure of meeting deadlines for vendor invoices, inventory and payroll. When faced with tight financial situations, some business owners consider short term loans as a way to keep the ship afloat.

That being said, these loans come with their own unique risk profile that you need to be aware of lest you get trapped in the murky waters of toxic and unending loans. The short-term nature of these loans makes the borrowing process a little bit difficult for borrowers who have complex and below par credit histories. Before going for these loans, you must conduct a cost-benefit analysis to see whether borrowing on a short-term basis is more beneficial to a conventional long-term loan. Below are some of the perils of short-term financing for businesses.

Unfavorable Renewals

Though most short-term business loans are meant to paid off quickly, there are instances when you need additional time for repayment and this can put the lender in a controlling position making him sort of dictate the terms on which the contract is to be renewed. The new repayment plan may be less favorable to you because after all, the lender is in business. The newly accumulated debt can potentially push you into not only into business bankruptcy but also personal bankruptcy, which comes with its own set of perils.

Reputational Risks

If you rely on short-term loans as a business, investors may be worried or even turned off when they review your financial history. Most of the times, short-term loans hold on to specific asset classes as security and this give a picture that your business is not financially stable and is teetering on the edge of collapse. Also, the manner in which you handle your short-term financing can affect your ability to secure long-term financing in future.

Less-Than-Required Financing

Compared to traditional loans, short-term loans are much smaller. The reason behind this is that these loans are meant to be realistically paid off in a few months or year. If this is to happen, the principal plus the interest must be within the business financial radar to repay. If what you need is just a small loan to plug in a gap in expenses, this can work well with you, but if you want to replenish larger inventory items or boost your production so as to meet a deadline, this may not be enough.

Relatively Higher Interest Rates

The cost of short-term borrowing attracts higher interest rates compared to long-term financing. In the short run, the impact of these interest expenses may not be strongly felt, but when you look at your books a few years down the line, the cost may even double or triple that of bigger long-term loans. For instance, if the loan comes at a cost of about 25%, what this means is that your business must generate a rate of return higher than the cost of capital for the short-term loan to make sense.

Difficulties in Refinancing

As a business owner, having more flexibility is a great deal for you. This is because it opens up options making you adaptable to unforeseen circumstances or emergencies. However, refinancing short-term debt with another short-term facility can narrow your options. When you refinance, the new loan may potentially prevent the existing balance from getting low enough to enable you qualify for a credit facility by another lender. This may not be much of a problem if you are contented with your existing lender, but it can limit you if you want to cross over and shop for more competitive deals.

What Alternatives Do You Have?

Instead of focusing most of your energies on short-term financing where your bargaining power is somewhat limited and compromised by the urgency of your need, you can explore refinancing with long-term debt. This will save you stress and lower the frequency or size of your payments. Getting a line of credit can also be an option because then, you only pay the interest on the money you require and the capital is always available should you need it.

Though it is tempting, play your cards well and closely analyze the fine print before giving a short-term loan deal an okay.

Read More...

4 Must-Read Books On Real Estate Investing

Books will always serve as a clever investment. Books will offer you the chance to learn new strategies to become a better real estate investor. Furthermore, you can save a substantial amount of money by avoiding the expensive mistakes of other authors.

On that note, here are the must-read publications if you are looking for ways to make the most of your property investments:

1. REAL ESTATE INVESTING FOR DUMMIES BY ERIC TYSON AND ROBERT GRISWOLD

Buy it here.

The preconceive notion of purchasing a “For Dummies” guide is that you are utterly clueless about a certain topic. Do not mind this! This book is a good resource for newbies in the Real Estate scene, especially made for those who have no prior experience. It elaborates difficult concepts in simpler terms.

The authors do not promise an overnight success story. Instead, they offer practical and realistic advice for its readers. These advice will help you conquer the challenges and take advantage of the opportunities ahead.

2. LANDLORD ON AUTOPILOT BY MIKE BUTLER

Buy it here.

The rich wisdom of this book grew from the author’s experiences after he managed 75 rental properties while he still committed to a full-time job as a police detective. It may seem impossible to juggle the two worlds but, it is doable.

Landlording on AutoPilot features useful information on dealing with the dynamics between the tenants and the landlord. It can dramatically improve your rental business and its surrounding relationships. If you are afraid to jump in this field or if you are struggling as a landlord, you must give this book a shot!

3. RICH DAD POOR DAD BY ROBERT KIYOSAKI

Buy it here.

As you dive in the world of investments, feed your mind with the philosophy of the renowned author and lecturer Robert Kiyosaki. I was intrigued about his teachings after I watched the book summary video by Evan Carmichael. See it for yourself.

What you can expect from this book is a lot of motivational talk. It is one of the library staples among investors because it contains a massive amount of thought-provoking content. He created two unique perspectives about money that emerged from two of his fathers – the rich and the poor. While the poor dad will tell you to work for your money, the rich dad will tell you to let the money work for you. The author did a great job in encapsulating the what I had been feeling for a long time.

4. THE ULTIMATE GUIDE TO REAL ESTATE INVESTMENT IN SINGAPORE BY ISMAIL GAFOOR

Buy it here.

When it comes to the big players in the Singapore real estate industry, Ismail Gafoor leads the wolf-pack. This book is the culmination of his passion and hardwork. Let us begin with his inspiring life story.

Mr. Gafoor and his family struggled with money when he was young. At the prime age of 7, he was tasked to deliver newspapers with his dad. This means that he was constantly late for school. As a young adult, he began a career with the Singapore Armed Forces. His cumulative salary led to his brave decision to buy his first property at Normanton Park. Because he saw the potential of real estate investments as a decade passed, he decided to open his own property agency with his wife. Nowadays, we know this leading agency by the name of PropNex Pte Ltd.

Image Credits: pixabay.com

Image Credits: pixabay.com

Enclosed in this book are answers to various questions that investors ask. It is hard to go wrong with this book knowing that its contents came straight from the workings of a top real estate pioneer.

Sources: 1 & 2

Read More...

6 Strategies To Control Your Urges To Spend

Self-control is one of the virtues that a savvy Singaporean can cultivate. Having a sense of self-control helps you to manage the seemingly irresistible urge to spend money. While, people who lack it have a tendency to instantly gratify their “itch” to splurge.

Combat this dilemma against your willpower by employing these strategies:

TRACK YOUR SPENDING

I know how cliché this sounds but, awareness is the key. You must note down how much money comes in and goes out. Previous literature displayed that this act of tracking your spending is an efficient tool to control one’s urges to spend. Start by keeping a daily list of your expenses.

IMPOSE LIMITS 

To prevent accidents and to maintain order in the streets, authorities impose speed limits. Apply the same idea to your finances by imposing monetary limits.

It easy to create tangible boundaries to some services such as postpaid and bundle plans. However, this is not always the case. This is why Professor and TED Speaker Dan Ariely highlighted that it is important to dictate your own boundaries. Doing so was proven to help increase self-control. Furthermore, sharing your self-determined limitations to other people urges you to stick to it more.

MAKE ONE DECISION AT A TIME

The shiny distractions all over the shopping mall are designed to confuse your mind and to open your wallets. You see, findings showed that strain in cognition (thinking) depletes self-control. This is why shops are graced with flashy signs, vibrant colors, loud songs, and bright wall decor.

Conquer the distractions by making one financial decision at a time. This strategy is not only limited to shopping. Divide your financial decisions instead of overwhelming your mind.

SAVE AUTOMATICALLY

Avoid committing much of your willpower toward deciding whether to save or to spend by automatic your finances. Some institutions allow the employer to automate your salary in a bank account that is solely for your savings. Patronizing this method will lessen the temptation of immediate spending.

Image Credits: pixabay.com

Image Credits: pixabay.com

TAKE TIME TO DECIDE

With my background in Psychology, I can attest to the idea that the emotional states affect the way you spend. Anxiety was shown to decrease the likelihood of taking risks and sadness was shown to increase spending. Emotions influence your self-control in complex ways.

This is why I encourage you to take sufficient time for contemplation before buying something. Wait for a few hours or a few days, especially for huge and expensive purchases. Many people have submitted to this efficient strategy. Be one of them!

PREVENT TEMPTATION

A surefire way to stay on top of finances is to avoid temptation at all costs. Reduce your time spent on shopping malls and invest it in more productive matters. Alternatively, you may leave your plastic cards (i.e., credit and debit) at home. Simply carry the amount of cash that you can confidently afford.

Image Credits: pixabay.com

Image Credits: pixabay.com

These six strategies share one goal and that is to take control of your finances again. May these aforementioned help you to reclaim what was rightfully yours.

Sources: 1 & 2

Read More...

4 Benefits of a Monthly Investment Plan

Based on a Worldwide Cost of Living survey conducted by the Economist Intelligence Unit, Singapore has been ranked as the world’s most expensive city to live in for the third consecutive year. Indeed, many living in Singapore have to contend with the high property and car prices. Healthcare and education costs are also not far from people’s minds.

Investment is seen as a way to potentially amplify one’s wealth to better fulfil these life goals. But what if you do not have a substantial amount of capital or time set aside for investing? A Monthly Investment Plan or what’s also known as a Regular Savings Plan, could be something for you to consider.

  1. Affordable

There’s a common misconception that you need to have sizeable capital in order to start building a nest egg through investing. However, with a Monthly Investment Plan, you can decide how much to invest based on your personal financial situation. You can even set aside just $100 a month, and put that money into blue chip stocks, exchange traded funds (ETFs) and Real Estate Investment Trusts (REITs) listed on global markets to build your portfolio.

  1. Takes Advantage of Dollar Cost Averaging

Monthly Investment Plans follow the principle of dollar cost averaging. By investing regularly every month instead of trying to time the market and find the best time to buy and sell shares, the risk of investing a large amount in a single investment at the wrong time is reduced.

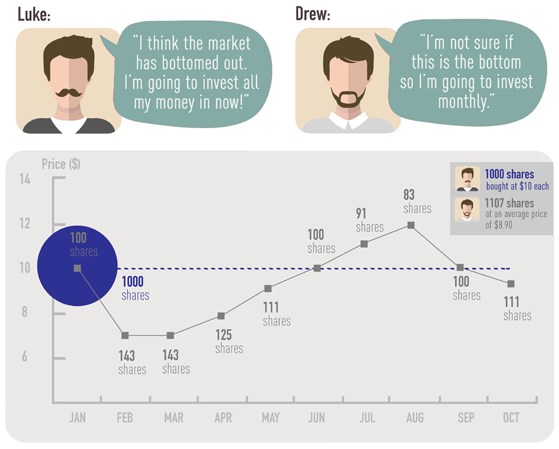
To gain a better understanding of dollar cost averaging, consider this example where two siblings are given $10,000 each, but choose to invest it in different ways.

Luke used the money to buy 1000 shares at $10. Drew, on the other hand, invested a predetermined amount each month, and he ended up buying more shares when the price was low and fewer shares when the price was high.

monthly-investment-plans-graph

Drew’s average price per share ($8.90) is therefore lower compared to Luke’s ($10) – this is how dollar cost averaging works and by extension, how Monthly Investment Plans can help you achieve your investment goals.

  1. Automated and Hassle-Free

No one can exactly foresee and predict the behaviour of the stock market. Instead of trying to time the market and finding the right time to enter and exit, Monthly Investment Plans focus instead on long-term gains, and build your portfolio by automatically buying your shares for you every month. Your work is done at the outset. All you need to do is choose your desired shares and set your monthly investment amount. From that point on, you can sit back and watch as your portfolio grows and your shares accumulate.

  1. Diversification

Monthly Investment Plans enable you to diversify your investment portfolio in a couple of ways.

Most of these plans allow you to invest in ETFs like SPDR STI ETF or Nikko AM STI ETF which are funds that invest in the 30 largest companies listed on Singapore Stock Exchange. More conservative investors can go for these ETFs. In addition to these ETFs, your Monthly Investment Plan may allow for investments into REITs. If you are interested in investing in property, then this is something to look out for; REITs don’t just give you exposure to one property – they give you exposure to a whole portfolio of properties. Some Monthly Investment Plans will also allow you to access stocks listed in markets like the US, Hong Kong, Malaysia and Thailand. Expanding your horizons and looking at offerings listed on these global markets is another way to diversify your portfolio.

If any of these four benefits sound appealing to you, then you should find out more about how Monthly Investment Plans can help you along your investment journey.

Read More...