How to Allocate your Portfolio

How to allocate your portfolio

(This article is brought to you by Some Ideas on Investing in Singapore)

I’m going to share some of the ways that you can allocate your portfolio according to the different amounts of money that you are able to invest (those above your emergency fund and not needed for any big-ticket purchases).

Straits Times has done a similar article on this topic, How to invest if you have $20k or more (19 Jul), but I disagree with some of their recommendations (especially since I don’t really like the idea of unit trusts and prefer index funds)


If you have around:

$10,000 (or less) to invest….

  • 100% Index funds or ETFs

You can place your money in index funds or an exchange-traded funds (ETFs), the latter can be bought and sold on the SGX like shares, but some of the funds are specified Special Investing Products (SIPs) and would require you to meet some criteria. This would give you diversification as investing in the fund will give you exposure to the different shares in the fund.

For example, investing in an index fund that tracks the Straits Times Index (STI) will spread your capital across the 30 shares that make up the STI, according to the size of the market cap of each company as the STI is a capitalization-weighted index.

$50,000 to invest….

  • 60% Index funds or ETFs 40% Stocks or REITs

Instead of investing in index funds or ETFs, if you are more adventurous, you can try investing in individual companies or REITs (but I think it’s still good to keep a good part of your portfolio in index funds or ETFs). Picking out individual companies will require a bit more time to research the companies on your own to pick out the good from the rest. The ability to pick out good companies will require some experience to master, but the potential returns will be much better than investing in index funds or ETFs if done well, but don’t try to do so if you’re not willing to put in time to learn and research as you may end up only paying “tuition fees”.

$100,000 (or more) to invest….

  • 70% Stocks or REITs 20% Bonds 10% Cash

With this amount, you may be able to purchase all of the 30 shares in the STI on your own to avoid the expense ratios of index funds and ETFs and another advantage would be getting dividends as the companies pay them instead of waiting for the funds to pay them out. You may still incur some minimum brokerage charges if you try this, but if held over a long enough period, this would be cheaper than using index funds or ETFs.

Another advantage of not using index funds and ETFs at this point is the ability to buy shares that you think may outperform the market. Let’s say you think that the finance sector may not do so well in Singapore, you can cut out the finance stocks, such as DBS, UOB and OCBC, and go for the companies that you think will outperform the market.

You may also want to keep some of your portfolio in bonds and cash as well to better protect your portfolio should the market enter a downturn, you still have an income and cash to take advantage of the drop in share prices to buy into the market at the cheaper prices.

I think that this is a good way to invest if you have above $100,000, unless you have amounts in the millions in which case I have not much idea of how to invest in that region.

Summary

Overall I support index funds and ETFs as a good way for people with smaller portfolios to be able to access a wide diversification across different shares in the index that the fund covers. (You can see my post on indexing at: Thoughts on Indexing) As your portfolio grows, you may want to move into individual shares as they offer the potential for better returns and with your larger investment, it would make more sense to spend more time researching the companies (amount earned over time is higher).

When investing in the market, you may also want to practice dollar-cost averaging to ensure that you do not enter the market at too high a price and get your fingers burnt when the market drops, but don’t invest too small amounts such that you spend a large amount of your money on minimum brokerage fees. While it’s good to diversify to reduce your exposure to any one company, investing in too many companies dilutes the returns of the “winners” that you have chosen.
 

Read More...

What Is Financial Well-Being And How Does One Boost It?

Early this year, the U.S. Consumer Financial Protection Bureau conducted a study on 59 consumers as well as 30 professionals to define what financial well-being actually is. Through their in-depth interviews they found that your income does not matter; consumers can experience financial well-being or the lack of it because it is highly personal. Therefore, financial well-being is defined as having financial freedom of choice and financial security in the present and in the future.

FACTORS THAT INFLUENCE THE FINANCIAL WELL-BEING

a. Social and economic environment,

b. Personality and attitudes,

c. Decision context,

d. Knowledge and skills,

e. Available opportunities,

f. and Behavior.

Image Credits: pixabay.com (CC0 Public Domain)

Image Credits: pixabay.com (CC0 Public Domain)

FINANCIAL WELL-BEING’S FOUR ELEMENTS

1. PRESENT SECURITY

You are able to pay your bills on time and do not have to worry about having enough money. You manage your finances and not the other way around.

2. FUTURE SECURITY

You are prepared to handle any financial emergencies or shocks that when it strikes, you have sufficient insurance, savings, and support from your family and friends.

3. PRESENT FREEDOM OF CHOICE

You have control over your life because you have financial freedom. Taking holidays, going out for dinner, and being generous to your family are done as you wish.

4. FUTURE FREEDOM OF CHOICE

You have short-term and long-term financial goals and you know how to meet them.

Image Credits: pixabay.com (CC0 Public Domain)

Image Credits: pixabay.com (CC0 Public Domain)

WAYS TO BOOST YOUR FINANCIAL WELL-BEING

1. EARN  IT

Many people cut expenses but only a few examine ways to increase income. In the event of job loss, it is still important to do whatever it takes to provide for yourself and your family.

2. PROTECT IT

Do research (e.g., from newspapers, Internet, and financial experts) to ensure that all your monetary efforts are not wasted.

3. MANAGE IT

After you retire, the bottom line is not how much you make but how much you keep.

4. GROW IT

With careful financial planning, money will grow even in a slower economy.

5. ENJOY IT

A comprehensive plan will allow you to go for vacations, new car, and so much more. With this, you can transfer some funds to your heirs or to charitable causes.

Take each day as an opportunity to work towards improving your financial well-being! 🙂

Read More...

Free Investment Resources Singaporeans Can Benefit From

1. BORROW BOOKS FROM THE PUBLIC LIBRARIES

The best way to fish in an unfamiliar territory is to research about it first. Know the basics in investing and trading by visiting your local or regional public library and borrowing their books. A few examples of the books you may find are “The Resilient Investor”, “Trading Options for Dummies”, and “7 Simple Strategies of Highly Effective Traders”.

The National Library Board (NLB) ensures that the information given in the public libraries are trusted, accessible, and comprehensive. Their genuine aim is to build a knowledgeable nation with generations of readers.

What is great about NLB’s website is that you can browse the availability of the book as well as find the list of libraries where it is located. This way, you do not have to go to a nearby library only to find out that what you are looking for is not there. For instance, you can find the 7 Simple Strategies of Highly Effective Traders book in 12 public libraries including Toa Payoh Public Library – our nearby library. Start searching by yourself, here.

2. ATTEND A NO-COST WORKSHOP ABOUT INCOME INVESTING

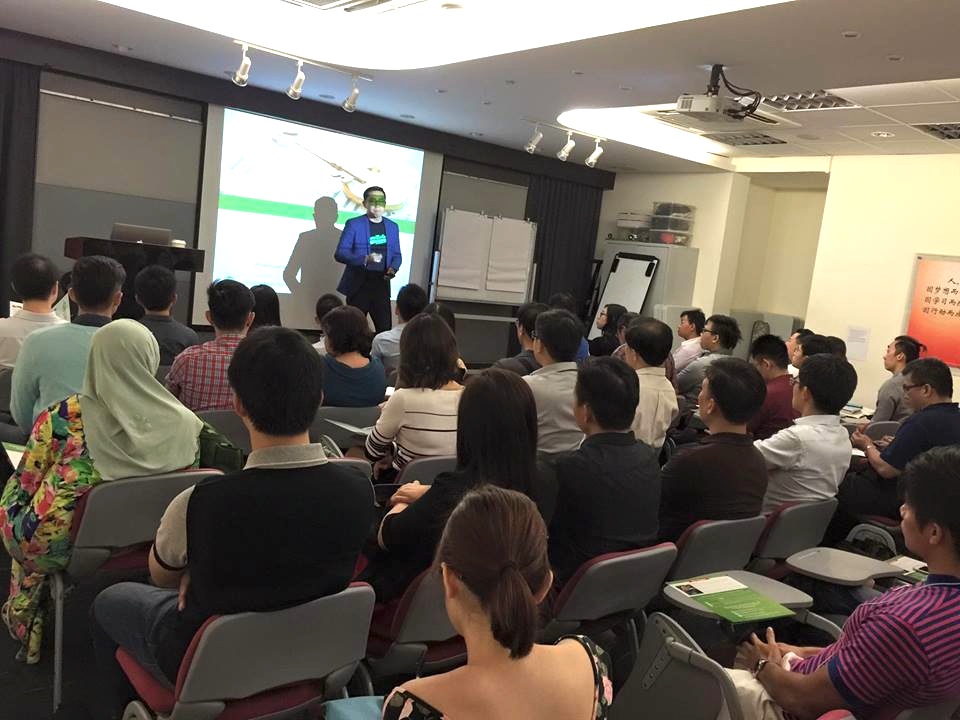
Last Tuesday, I had an opportunity to attend a workshop named: “Get Rich Slowly, The Income Investing Way”. Terence Tan led it. Terence Tan is the creator of the first Income Investing Programme in Asia-Pacific called Income Mastery Programme (IMP). Also, he is the chief investment strategist in Giants Learning Technologies as well as the founder of First Traders Network.

With a guy whose experience in stocks spans over 16 years, I thought to myself that I could certainly learn a thing or two. To get things straightened out, if you are looking for a method to get rich quickly through investing, this talk is not for you. Instead, this is for people who seek financial freedom by patiently and diligently pouring their resources for years on end.

Image Credits: facebook.com/IncomeMasteryProgramme

Image Credits: facebook.com/IncomeMasteryProgramme

What you can expect from this free 2-hour workshop is to gain a glimpse of the mindsets of some investors such as the renowned Warren Edward Buffett, to uncover the principles of income investing, and to determine the right stocks in 15 minutes or less. Furthermore, he will introduce you to his own methodology called the Income Mastery Programme. My impression of IMP after the workshop was it was a feasible yet gradual way to generate profits while in the midst of low-risk trades. By lowering down the risk, you will be confident that the stocks make money over time. If you are interested to know more, you can register for their upcoming talk on August 18, here.

3. TAKE PART IN A HUGE INVESTMENT FAIR – FOR FREE

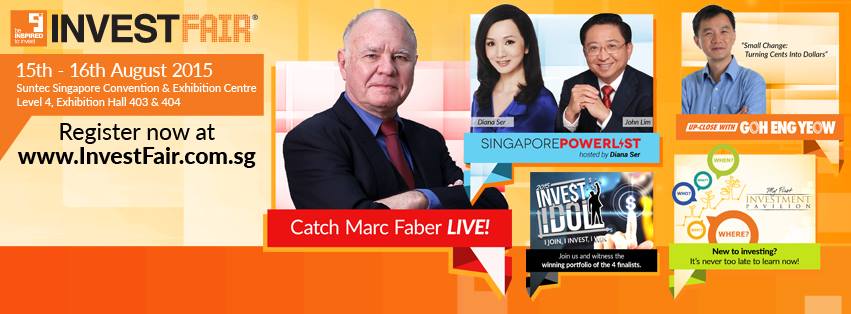
Dating back from 2007, Invest Fair Singapore is ShareInvestor’s annual event for investors and traders alike. Enjoy the presence of world-class speakers, key stakeholders, and other experts in the financial industry by registering here.

The list of featured speakers include Marc Faber (Investment Expert and Best-Selling Author), Kathy Lien (World-renowned Currency Strategist and Best-Selling Author), Roger Monthomery (Chairman and CIO of Montgomery Investment Management), and one of Forbes’ 2014 list of Singapore’s 50 Richest men – John Lim.

The seminars start with “Simple Trading Strategies for Fast Profits” on August 15 and ends with “Portfolio Allocation” on August 16. Best of all? You can get exclusive promotions from their exhibitors and stand a chance to win prizes at their lucky draw.

Image Credits: facebook.com/ShareInvestorSG

Image Credits: facebook.com/ShareInvestorSG


Read More...

Easy Ways You Can Save Over S$3,000 A Year

Life is unexpected; you will never know when an emergency or financial crisis will hit. With that constant reminder, who does not want to save over S$3,000 a year? That said, here are the Easy Ways You Can Save Over S$3,000 A Year:

1. WATER SELECTION

If you are purchasing bottled water from the stores that are priced at S$1/1.5L bottle then, a family of four goes through at least 20 bottles a week. This is why it is best to drink from the safe tap. Filling up your reusable water bottle or jug only takes seconds and only costs S$0! With the tap water, you save about S$960 annually!

2. POWER STRIPS OFF

Power strips or otherwise known as power bar, trailer lead, or extension block, can spike your electric costs even if you turn it off.

Image Credits: US-power-strip-rotated via Wikimedia Commons (Licensed under CC BY-SA 3.0)

Image Credits: US-power-strip-rotated via Wikimedia Commons (Licensed under CC BY-SA 3.0)

Accounting for about 5-10% of your home’s energy bill, the best way to save from this is to unplug it completely. Unplugging your power strips can save you approximately S$70-330 per annum.

3. LIMITING AIR CONDITIONER USAGE

At 900 watts or more, your air conditioner (AC) is one of the major appliances that contribute to a huge chunk of your energy bill. So, if it is running for 8 hours a night for 365 days then, your medium-sized AC unit will cost you about S$600 annually. A good way to save about 50% is to time your AC to shut down after 4 hours. Then, save about S$25 on AC – a month!

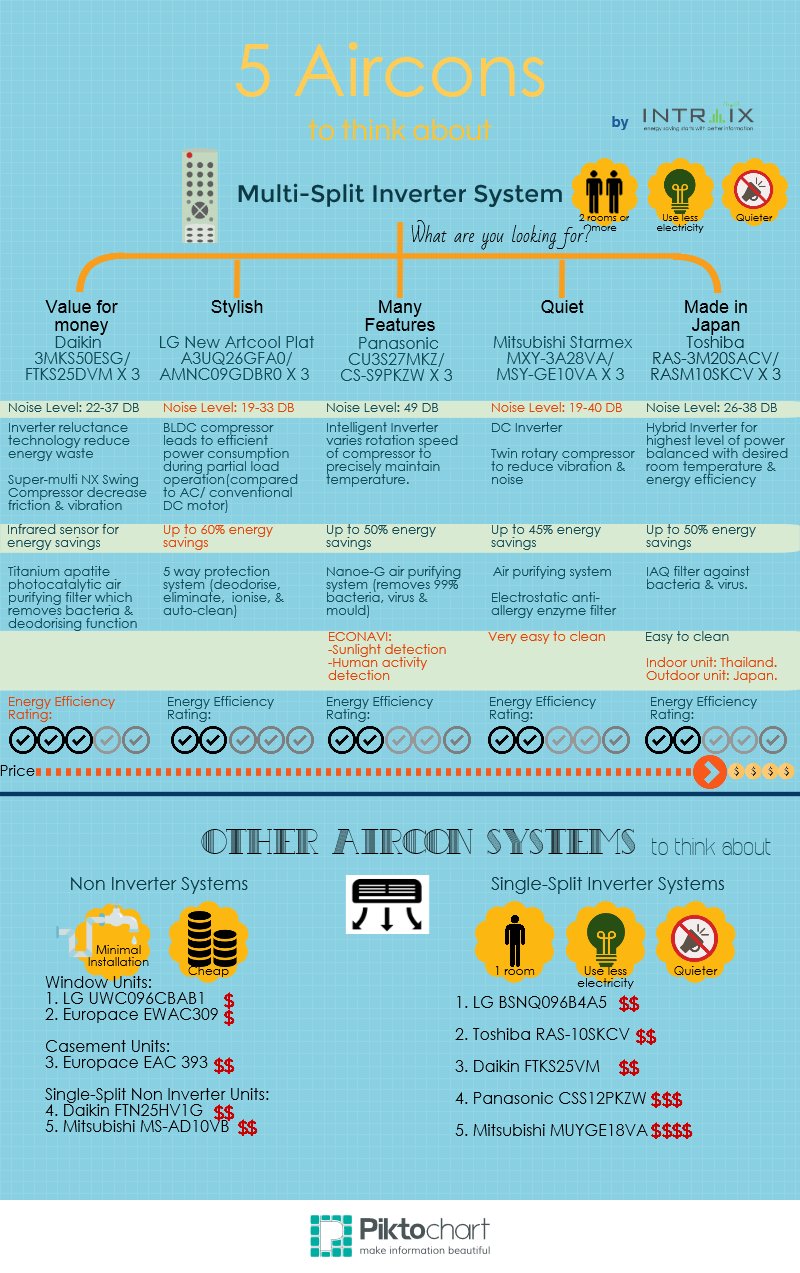
Furthermore, here are the 5 Cost Saving and Energy Saving Air conditioners For your HDB:

Image Credits: home.intraix.com/5-aircons-to-buy

Image Credits: home.intraix.com/5-aircons-to-buy

4. ELIMINATE THE DRYER

Instead of constantly putting your clothes in the dryer, hang it in properly in a clothesline. The dryer, like the AC, is contributing to a huge chunk of your energy bill. It feeds on energy and a lot of it. So, by letting your dryer rest, you can save about S$103 a year. That is if you regularly have 6 loads per week and take 20 minutes per load.

5. HAVE HOME COOKED MEALS FOR DINNER

Aside from packing lunch at work, cooking at home every dinner will cut your costs effectively and immensely. The cost of the meat, vegetables, and spices are lesser at the grocery than at the restaurants outside. This is why you must limit your restaurant trips or take-out meals to at least once a week.

For instance, you are going out for dinner at an average restaurant for 3 times a week then, it can cost you S$240 a month or S$2,880 a year. So if you limit your outside dinner trips to once every week then you can save up to S$1,920 a year!

SUMMARY (M-1 month & Y-1 year):

A. Water: S$80/M , S$960/Y

B. Power Strips: S$5.8-27.5/M, S$70-330/Y

C. Air Conditioner: S$25/M, S$300/Y

D. Dryer: S$8.6/M, S$103/Y

E. Dinner: S$160/M, S$1,920/Y

Image Credits: pixabay.com (CC0 Public Domain)

Image Credits: pixabay.com (CC0 Public Domain)

Thus, the total can go up to S$3,613 worth of savings in just 12 months! 🙂

Sources: 1,2,3 & 4

Read More...

World Value Invest Fest 2015 Power Lessons [David Kuo]

Previously we explored into the mind of Warren Buffett through Mary Buffett’s invaluable lessons on Mr Buffett’s Value Investment Methodology and some of the power pointers on how to select a company to invest in. This time, let’s draw from David Kuo’s experience on Managing Risks In Stock Investing!


What is ‘Risk’?

A term we hear too often, yet never really having a perfect definition of what risk is. There are so many types of risks out there and how do we effectively manage all of them at once? Almost impossible! At best, we can mitigate them, but probably not completely eliminate them. But what good is identifying all the various types of risks affecting you, when you fail to know yourself? Risk profiling. If we don’t even know what is our risk profile, how can we select investments that have risk profile that is aligned to our own? Is it important for them to be aligned? Definitely! Say a 65-year old man who wants to invest his retirement fund for income, would you recommend him to buy speculative stocks with P/Es in the hundreds and no fundamentals? Of course not! Similarly, have we overlooked the risk of not a comprehensive risk profiling of ourselves and check if our investment decisions are aligned?


Different Strands of Investing for Different People!

There are so many different strands of investing:

  • Growth
  • Income
  • Blue Sky (Start-ups)
  • Sideways
  • GARP (Growth At Reasonable Price)
  • Bottom-Up
  • Top-Down
  • Value
  • Index Trackers

You don’t have to be afraid that you won’t find one that doesn’t suit you! First you need to identify where you are in life, what your investment goals are, and how much risks are you willing to take on to achieve your investment goals. Different strands of investing entails different risks and requires different investment mindset and strategies. Identify the strand that you want to focus in, read up on the skills and mindset required for the different strategies. For example, Index Trackers would adopt a very different mindset require a different skill set from Value or Growth investing. Index Trackers take on a more passive approach towards investing while gladly accepting the diversification it provides. Growth and Value Investing however requires the ability to not just read financial statements, but also, understand business as a whole and consider it from the point-of-view of a businessman. Both method works, but it depends on your investment goals. Are you trying to get from rags-to-riches? Or do you want to simply take a back seat and enjoy the ride? There’s no right or wrong, but it’s worth exploring and knowing yourself a little more.


How To Avoid Panicking

David Kuo shared this very powerful quote which many of us tend to forget – “Do not confuse the price of the stock with the story behind the stock.”

Indeed, does the price of the stock dictate the story behind the stock, or is it the other way around? If you only knew the price of the stock and not the story behind the stock, you would definitely panic because you have nothing to fall back on! David emphasises on the importance of knowing why you bought your stocks in the first place. If you knew the story behind the stock, would a falling price cause you to panic or would you see it as an opportunity to buy more at a cheaper price? If you knew the story, you would at least have the mental and emotional capacity to ride out the rough patch, having quiet confidence that the company’s results will show for itself in the long-run. “There will be delays in our investing journey”, so ALWAYS have a margin of safety! If we can’t eliminate, at least mitigate the temporary losses! Lastly, ask yourself, do you have the courage to invest when times are bad? 🙂

Read More...