When it comes to spending less and saving more, it is tempting to bury our heads in Sentosa’s sand. The way we manage our finances today is entirely different from the way money was managed in the past. It is getting increasingly easier to spend money, and more challenging to save money.
When done right, budgeting can direct a series of clever financial choices to move you closer to the things you want out of life. Take the time to get this right at the start, to give yourself a massive advantage and benefit from the results for years to come.
Start by using simple brain tricks to help you stick to your budget.
#1: TREAT YOUR SAVINGS ACCOUNT LIKE A BILL
Consider your savings account as another monthly bill. Start by allotting money towards your fixed expenses, followed by assigning a certain amount towards your future. You can use this fund either for your retirement or your future goals, but do not go out and blow it on things you do not need.
Saving for your future is just as important as paying your other bills. When you treat it that way, you will develop a wealth-building mindset.
#2: MAKE SMALL BARRIERS TO CURB YOUR SPENDING
The convenience of online banking and banking apps cannot be denied. Your banking app can show you the movements of your funds in real time. Moreover, you have the ability to input your debit or credit cards directly onto your phone to experience fast payment processes. When there is no barrier between you and your money, it becomes easier for you to spend more.
Place a barrier between you and your emotional shopping tendencies. Whether you are keen on putting a long passcode on your banking app or using two-factor authentication for your online banking, you will be less tempted to spend when barriers exist.
#3: GAIN CONTROL OF SMALL, FREQUENT PURCHASES
Your small, frequent purchases add up. Every time you buy a coffee or eat out, your ability to save decreases. It might not seem too much at the moment, but it adds up to a significant amount. Track your expenses by writing down every small purchase per month. This will increase your awareness and help motivate you to cut down on your spending.
You might be shocked to see the number at first. However, you will be able to recognize why you are struggling to save.
#4: WAIT 15 MINUTES BEFORE MAKING A PURCHASE
As you are walking down the aisle of the nearest grocery store, you find it difficult to resist the promotions from left to right. Control your spending by giving yourself 15 minutes to ponder about your potential purchase. Giving yourself 15 minutes will allow you to resist your impulsive purchases.
If you can, it is even better to wait for a full day or a week before making purchases. Remember that having a waiting period is the best way to train your brain.
#5: GO OUTSIDE OF YOUR COMFORT ZONE
We are creatures of habit. This is why people resist changing their insurance provider, telecommunications provider, and so on. There is a desire to keep everything the same and anything different can be perceived as a loss.
Image Credits: unsplash.com
However, staying in our comfort zone means that we are paying more for services than we need to. Pushing yourself out of it will allow you to shop for the best deals. Start with reassessing your mobile plan, before moving to your utilities, insurance, and other providers. Revisiting these plans on a yearly basis will ensure that you are maximizing your hard-earned money.
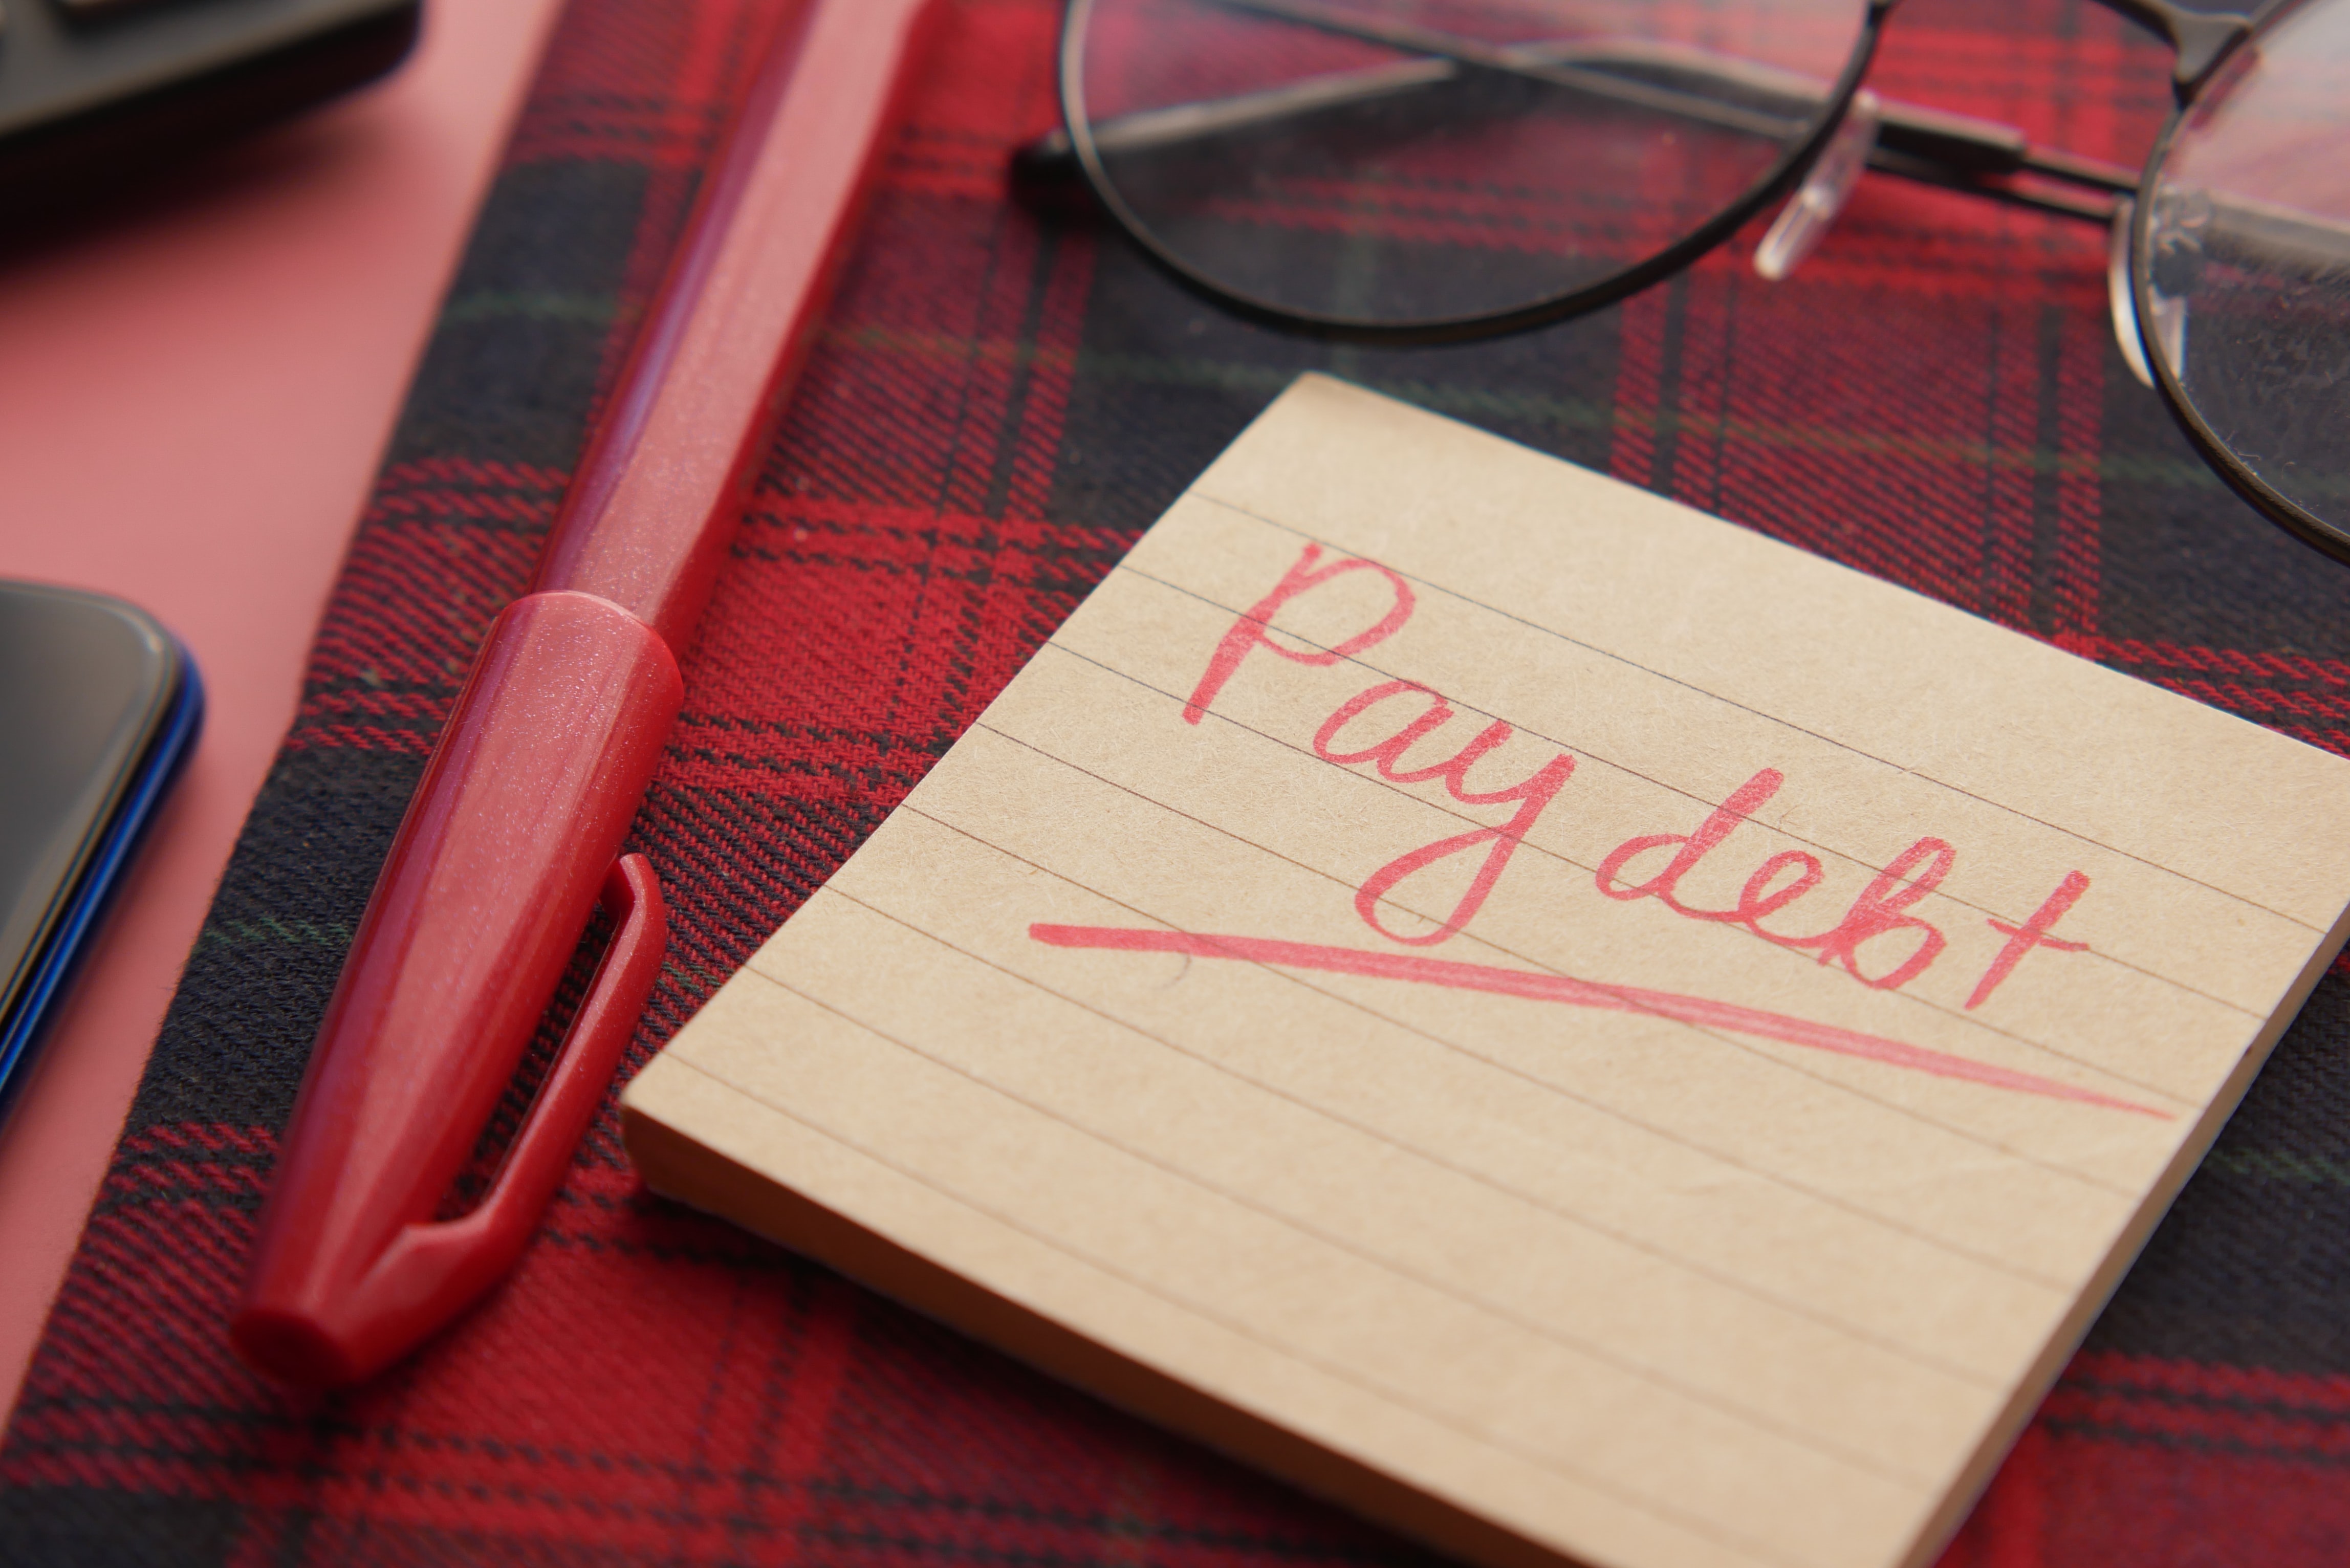
You’re not alone in feeling bad about being in debt.
Many people struggle every day with the weight of their debt. But what if we told you that debt doesn’t have to be a bad thing?
Believe it or not, there are benefits to having some form of debt. Below, we will outline a few of the more significant ones. We hope this information will help you see your debt in a new light and give you the strength to face it head-on.
How debt can be beneficial
Many people feel guilty for being in debt.
They see it as a negative thing as if they’re doing something wrong. But having some form of debt is not always a bad thing. In fact, there are many types of “good debt” that can help you build wealth or increase your income.
For example, student loans can be a good form of debt because they can help you get an education that will lead to a better job. Mortgages can also be seen as okay because they can help you buy a home that will appreciate over time.
So don’t feel bad if you’re in debt. It’s not always a bad thing. Just make sure that you’re only borrowing money for things that will benefit you in the long run.
Ways to manage debt
One way to do this is by checking your credit report. This will help you understand where you stand and what opportunities are available to you.
Another thing you can do is contact your creditors before the debt collectors become involved. This can help you negotiate a payment plan that works for both of you.
Tips for using debt wisely
Image Credits: unsplash.com
First, make sure that you have good debt—debt that helps you reach your financial goals. For example, investing in projects with a high return can be a good use of debt.
Second, focus on paying off high-interest debt first. This will help you save money in the long run. Finally, remember that debt can open doors and opportunities. So don’t be afraid to use it wisely to reach your goals!
What to do if you feel overwhelmed by your debt
If you’re feeling overwhelmed by your debt, there are a few things you can do to get back on track.
First, try to change your debt-related mindset. Yes, it’s wise to be smart about your finances and not spend more than you can afford, but some debt is unavoidable. And it’s not necessarily a bad thing—a lot of people use debt to finance big purchases like homes.
Second, you can consolidate your high-interest debts into one low-interest loan. This will save you money on interest and make your monthly payments more manageable.
The fact is, debt is a part of life for many people. And contrary to popular belief, having debt doesn’t mean you’re irresponsible or that you’re headed for financial disaster. There are a lot of misconceptions about debt out there, and a lot of people feel guilty or ashamed for being in debt. But the truth is, there’s nothing wrong with having some form of debt. So don’t feel bad. Just focus on paying off your debt and improving your finances as you tread along.
Singapore’s inflation may have eased slightly in November 2022, but the Monetary Authority of Singapore (MAS) warned of prolonged pain likely to linger. Risk factors pile up to the nation’s financial vulnerability in the corporate, banking, and housing sectors.
MAS stated, “Amid weakening external demand, the Singapore economy is projected to slow to a below-trend pace in 2023.” It added that “Inflation is expected to remain elevated, underpinned by a strong labor market and continued pass-through from high imported inflation.”
In 2022, the following items were heavily affected by inflation.
#1: GAS AND CAR REPAIRS
Fuel costs skyrocketed in 2022. It saw huge increases in the months of February, March, May, June, October, and November. Moreover, its increased fuel costs spilled over to January 2023. This high fuel costs were driven by the rising global oil and gas prices that were exacerbated by the war in Ukraine. Apart from fuel prices, repair costs definitely took a toll since early 2022.
#2: DELIVERY FEES
Delivery costs increased many companies and restaurants, hammered by inflation and higher fuel rates, passed those costs to consumers. Do you need to cut the costs of online delivery to your budget this 2023?
#3: CLEANING SUPPLIES
The pandemic led us to stay inside our homes more. With the increased demand and effects of inflation, household items became more expensive. Prices of garbage bags, aluminum foil, batteries, and cleaning supplies rose.
Image Credits: pixabay.com
Despite the price hikes, 2022 also saw some unexpected price drops. For instance, television prices sank globally in hopes of lightening their inventory. Major appliances also decreased in price. Used cars also saw a drop in prices. Apart from these observations, clothing retailers have also enticed the consumers with their continuous promotions.
Not to mention, households in Singapore can welcome the new year with lower electricity bills. The tariff for the first quarter of 2023 will decrease by 2.7 per cent. From January 1 to March 31, the electricity tariff before GST will drop from 29.74 cents to 28.95 cents per kilowatt-hour (kWh), said SP Group. This will take effect even as the new goods and services tax (GST) of 8 per cent kicks in.
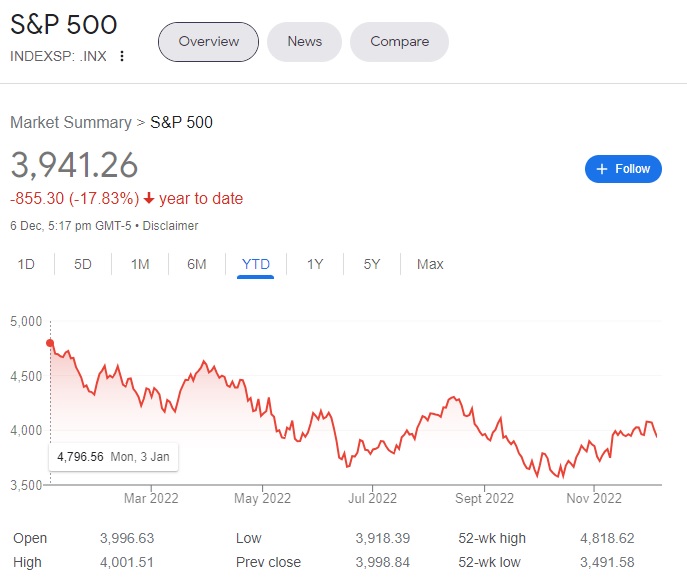
2022 has undoubtedly been a tough year for equity markets with global indices such as the S&P 500 down approximately 18% year to date.
A falling market can present interesting situations to different investors, and some would now see the glass as half-full. For instance, they may view cheaper valuations as a safety net that offers a larger margin for error. For investors who are thinking of starting their trading journey now, they can consider exploring with OCBC Securities. A wholly owned subsidiary of OCBC Group, OCBC Securities is a brokerage in Singapore that offers reliable services with transparent upfront fees. Now with their newly revamped iOCBC mobile app that comes packed with a myriad of user-friendly features, an even more seamless investment journey with iOCBC awaits.
Here are 5 new features on iOCBC that can help you spot timely trading opportunities:
1. Intuitive interface throughout the entire trading journey
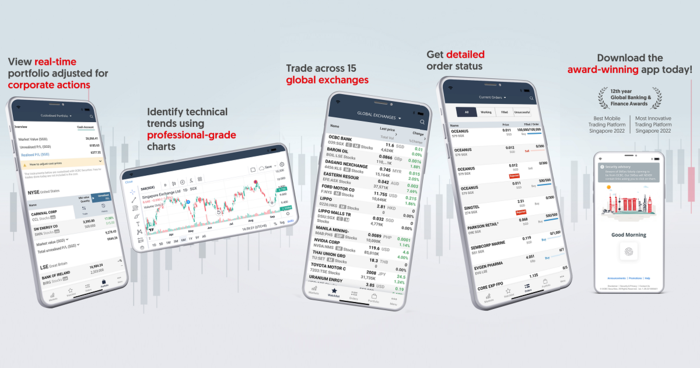
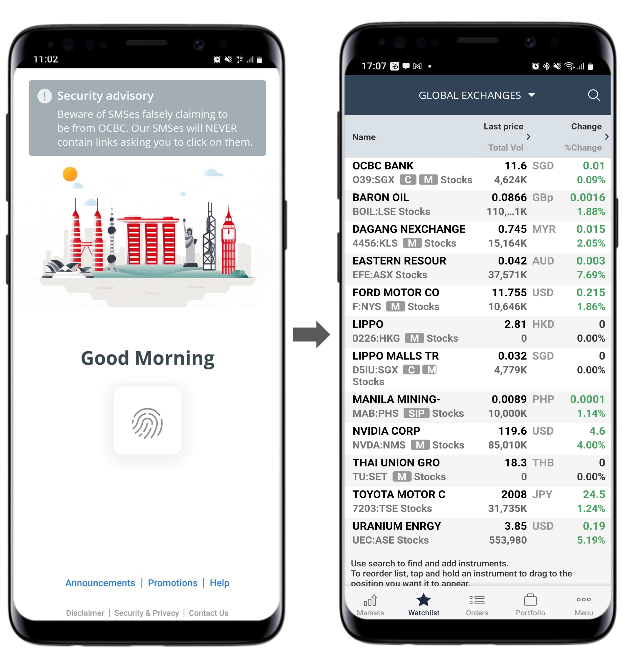
For those who trade, they will know that every second counts. From the overall look and feel to small thoughtful details, the iOCBC Trade Mobile App is now designed intuitively for traders to trader smoother and faster. To start with, the biometric capabilities allow you to login and submit orders in a flash.
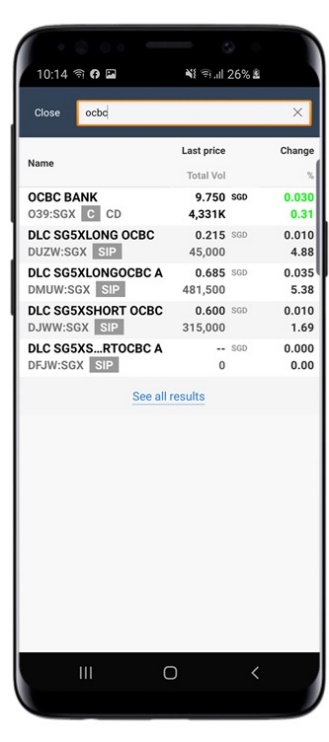
When browsing the markets, their predictive search bar with suggested results can help you to find the security you are looking for quickly, and also show you other similar instruments that are available on the iOCBC platform.
You can then add tickers to your watchlists from various convenient points through the app such as the search results and order ticket. Customise your watchlists to your preferences with collapsible columns to choose what information you want to see upfront or hide, and easily organise your watchlists with the drag-and-drop function.
As a new investor, making your first few trades can be incredibly stressful. With iOCBC, fret not as their trade order form comes with pre-built order validity checks. For newbies, this is very helpful as it will automatically display possible errors upfront by ensuring valid lot size and price range. Seasoned traders will benefit from this as well as it helps to reduce chances of fat-finger errors and also speed up your order placement.
After your orders are placed, tracking them is a breeze as the orders page is cleanly designed with colour coding to easily distinguish between buy and sell orders. Filter your orders by status (active, filled and unsuccessful) and see exactly how each order is filled and at what time with a detailed order log.
2. Gain market insights
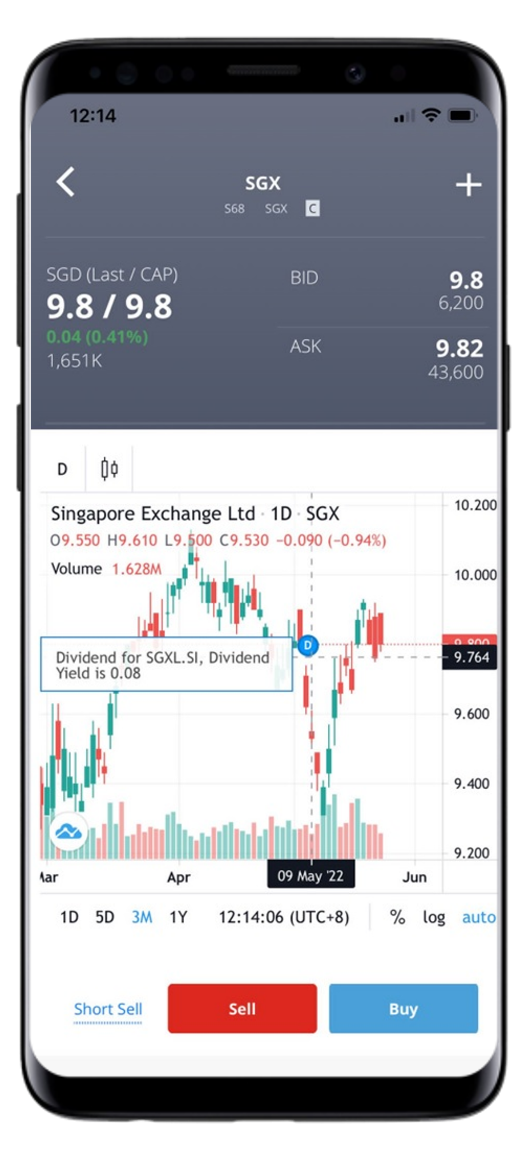
The iOCBC mobile app is packed with features to help you spot trading ideas and validate them with your technical analysis. Their professional-grade yet easy-to-use charts powered by TradingView comes with more than 100 Technical Analysis indicators and over 50 smart drawing tools to support you in identifying actionable technical patterns. Investors can also choose to discover new trading ideas effortlessly with iOCBC’s trading tools – Market Statistics, ChartSense and StockReports+. StockReports+ is especially helpful for new investors as reading these reports will help them gain valuable sectoral insights. With in-depth market analysis from industry reports, coupled with charting tools ready at disposal, these could help to elevate trading performances.
3. Manage your portfolio like a professional!
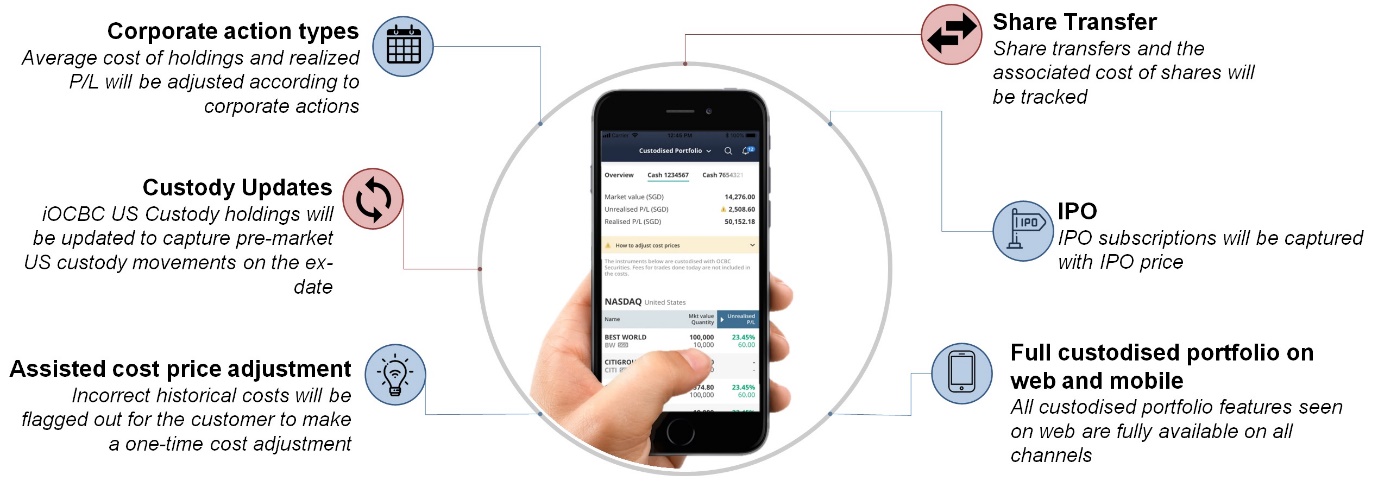
How would one know how well he/she is doing without keeping score? Not to worry, an investor’s portfolio is updated in real-time for timely monitoring as part of holistic portfolio management on the iOCBC mobile app. Amazingly, various types of corporate action events including stock splits, dividends and rights issues are tracked so that the average cost of holdings, realised profit and losses will be adjusted accordingly.
4. Know the fees you pay upfront
Whilst you might have heard of other brokerages having hidden fees that customers may not be aware of, you will be glad to know that OCBC Securities has always been upfront about the fees that it charges to investors. With something as critical as your trading portfolio, you would want to know what you need to pay for and trade with peace of mind.
5. A reliable and secure platform
Lastly, OCBC Securities is a wholly owned subsidiary of OCBC Group, and OCBC Bank is consistently ranked among the World’s Top 50 Safest Banks by Global Finance! OCBC Securities offers reliable, secure end-to-end encryption trading and custodises your foreign shares with a renowned global service provider. With more than 35 years of experience in the industry, OCBC Securities has always been a brokerage that priorities their customers’ needs. Customers of OCBC Securities are provided with a dedicated Trading Representative to guide and assist them on their queries and even discuss market ideas. For beginners, this means you will have someone to handhold you to start your trading journey.
The article is published by MoneyDigest and does not represent OCBC Securities Private Limited (“OSPL”)’s view on the matters mentioned. All views or information expressed or provided in this article belong to and are that of the writers and are for information purposes only. They do not take into account the specific objectives, financial situation or particular needs of any particular person. You should not make any decisions without independently verifying or assessing the contents. No representation or warranty whatsoever (including without limitation any representation or warranty as to the accuracy, usefulness, adequacy, timeliness or completeness) in respect of any information (including without limitation any statement, figures, opinion, view or estimate) provided herein is given by OSPL and it should not be relied upon as such. OSPL does not undertake an obligation to update the information or to correct any inaccuracy that may become apparent at a later time. OSPL shall not be responsible for any loss or damage howsoever arising, directly or indirectly, as a result of any person acting on any information provided herein.
Trading in capital markets products and borrowing to finance the trading transactions (including, but not limited to leveraged trading or gearing) can be very risky, and you may lose all or more than the amount invested or deposited. Where necessary, please seek advice from an independent financial adviser regarding the suitability of any trade or capital markets product taking into account your investment objectives, financial situation or particular needs before making a commitment to trade or purchase the capital markets product. In the event that you choose not to seek advice from a financial adviser, you should consider whether the capital markets product is suitable for you. You should consider carefully and exercise caution in making any trading decision whether or not you have received advice from any financial adviser.
Managing your finances as a single man or woman has both its advantages and disadvantages. As such, you have the freedom to choose how you intend to save or spend. On the other hand, married individuals have the safety net of a second income.
The benefit of managing your money when you are single is freedom. There is no one else to check in if you want to spend your Christmas bonus on a trip to Europe. Complete freedom cannot happen when you are married. Living off peanut butter and bread may sound reasonable to you, but your spouse and children may disagree.
When it comes to the disadvantage, you do not have a partner to offer accountability. Moreover, you do not have a safety net of second income should an emergency such as job loss occur. You need to figure out how to pay for food, loan payments, rent, and other expenses alone.
Hence, you must start managing your money by creating a budget.
#1: SET A BUDGET
Control your finances by creating a budget. You can try the 50/30/20 method. With this strategy, you allocate 50% of your income for fixed costs, 20% for savings and debt repayment, and the remaining 30% for your non-essentials. Adjust these percentages when necessary.
#2: FIND AN ACCOUNTABILITY PARTNER
We all need help. If you are single and you are having trouble with staying within your budget, you can find an accountability partner. Here is a helpful phrase: “It is not in the budget!”
#3: MASTER YOUR MEALS
You may be tempted to simply order takeout or eat at restaurants, but this strategy can easily get expensive in the long run. Cooking your own meals can save you a lot of cash. Search online for budget-friendly recipes for one person.
#4: MAKE YOUR GOALS HAPPEN
Set specific, measurable, time-sensitive, and attainable financial goals. Put them into writing. It will be easier to stay motivated when you can read these goals on a daily basis. For instance, you can create a list of goals and stick it to your fridge or make a desktop wallpaper out of it.