Micro-investing: Small Money Big Momentum

Micro-investing has emerged as one of the most accessible ways for Singaporeans to enter the financial markets without the stress of committing large sums. The idea is straightforward. You invest small amounts at regular intervals, often through mobile apps that automate everything from deposits to portfolio allocation. With fractional shares and exchange traded funds available for as little as S$1, even the smallest contributions begin to take shape as a genuine portfolio over time.

Its appeal lies in simplicity and confidence building. Micro-investing eliminates the belief that serious investing requires substantial capital. User friendly apps guide beginners at their own pace and budget, making the learning curve far less intimidating. The automated nature of these platforms also encourages discipline. When contributions occur quietly in the background, saving becomes habitual rather than aspirational. Over time, these habits compound and can meaningfully influence long term financial health. Even with limited funds, investors can achieve diversification by spreading small amounts across sectors, markets, and asset classes.

However, micro-investing is not without its drawbacks, particularly when it comes to cost. Round up apps may be convenient, but they often charge a flat fee regardless of account size. Some popular platforms start at about S$4 per month, which translates to roughly S$37 per year. This may not seem significant, but if you are investing only S$7 to S$13 a month, the fees can quickly outweigh your early returns. Many platforms operate on similar fixed fee structures, which can erode gains until the portfolio grows large enough to absorb these charges. Growth potential also remains modest unless contributions increase steadily. Small amounts will yield small results in the early years, which means micro-investing alone might not support major long term goals such as retirement or home purchases. Volatile markets can also feel more discouraging when account values are still small, as fluctuations appear more pronounced.

Image Credits: unsplash.com

Despite these limitations, the true value of micro-investing lies in habit formation and long term discipline. Small recurring contributions serve as early training for future investment behavior. They introduce new investors to market movements while reinforcing consistency. A simple projection illustrates the impact. Investing S$27 per month at a ten percent annual return grows to about S$339 after one year from S$324 in contributions. After ten years, it becomes roughly S$5,531. After thirty years, it surpasses S$61,033 from just S$9,720 in total contributions. These figures show how time and compound interest can turn modest amounts into meaningful progress. Micro-investing may start small, but it builds momentum. As contributions rise alongside income and confidence, it can become the gateway to a stronger, more resilient investment journey.

Sources: 1 & 2


Read More...

Spending Less and Living More in Singapore

I once stumbled upon a small shop that sold pre-loved books and a title caught my eye. It read “Live More, Spend Less”, and it made me reflect on how people in Singapore can stretch every dollar without giving up comfort or joy. In a city where the cost of living can feel overwhelming, it becomes even more important to be conscious of how we live and what we value. Living well does not need to mean spending freely. Sometimes it means being intentional with daily choices.

One of the most practical ways to save is by rethinking everyday habits. Cooking at home can make a big difference. If you have access to a kitchen, preparing meals in advance can cut food expenses dramatically while also giving you control over what goes into your meals. Even something as simple as drinking water from a reusable bottle can save money that often gets spent on beverages throughout the day. And of course, we are blessed with its famous hawker culture. For less than S$10, you can enjoy hearty meals and local favorites. If you want a more comfortable setting, food courts offer air conditioned spaces, although they come at a slightly higher cost.

Image Credits: unsplash.com

Living better also means spending with awareness. Tracking expenses through a simple app or spreadsheet helps reveal patterns that are easy to miss. Paying yourself first by setting aside savings before spending anything else builds financial discipline. But saving money should not mean giving up the things that make life meaningful. A thoughtful splurge on an experience with loved ones or a purchase that enhances your life is more rewarding than spending without thinking. Planning ahead also goes a long way. Booking tickets for activities through platforms like Klook or Agoda often comes with discounts that free up more room in the budget.

Furthermore, the beauty of Singapore is that you do not always need to spend to enjoy it. The city offers many free attractions that showcase what makes it unique. Walking trails at the Singapore Botanic Gardens are a refreshing escape in the middle of the city, while neighborhoods such as Little India and Chinatown offer vibrant streets filled with culture and food. A hike up Mount Faber rewards you with a sweeping view of the skyline and sea. Visit at sunset and you will be treated to one of the most beautiful sights in the city. From there, the cable car to Sentosa awaits if you choose to continue the adventure.

Image Credits: unsplash.com

Living more while spending less is not about deprivation. It is about being mindful, embracing resourcefulness, and finding joy in what already exists around us. Sometimes we just need to pause long enough to see them.

Sources: 1 & 2


Read More...

How to Start Investing in Gold in Singapore

There is something undeniably alluring about gold. Beyond its gleam and grandeur, gold carries a timeless quality, a tangible piece of wealth that transcends generations. Whether worn as jewelry or stored as bullion, it is an asset that often endures when markets falter. But for those looking to begin investing in gold in Singapore, the questions remain: Where should you start? Should you buy gold bars or gold jewelry, and which form truly protects you against inflation?

Gold’s enduring appeal lies in its reputation as a safe haven. When uncertainty shakes the global economy, as seen during the 2008 financial crisis or the COVID-19 pandemic, investors frequently turn to gold to preserve value. It is the metal that shines brightest when confidence in currencies fades.

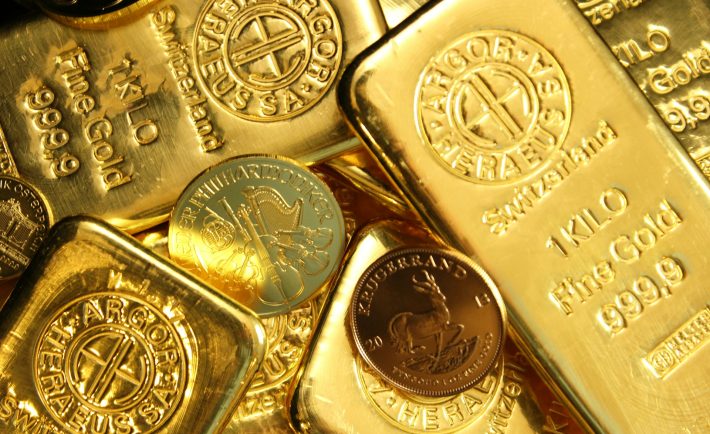
One of the most traditional ways to invest in gold is by purchasing physical bullion, which refers to investment-grade gold in the form of bars, coins, or ingots. Each bar typically bears the stamp of its manufacturer along with its weight and purity, usually 99.5 percent or higher. Coins, on the other hand, often carry artistic engravings or collector value that can push prices above the metal’s intrinsic worth. In Singapore, buying bullion comes with a tax advantage because gold that qualifies as an Investment Precious Metal (IPM) is exempt from the Goods and Services Tax (GST). Reputable sellers include UOB Gold Bullion, BullionStar, and GoldSilver Central.

Gold jewelry offers another route, though it is not quite the same as investing in pure gold. Jewelry comes with added costs such as craftsmanship, branding, and design premiums, which dilute its value as an investment asset. It can still serve as a portable store of wealth, but it is not GST-exempt and should not be mistaken for a direct hedge against inflation.

Image Credits: unsplash.com

For investors seeking something more dynamic, gold can also be approached as a currency-linked investment. Some structured products allow you to treat gold as a tradable currency known by its code XAU. In this setup, you agree on an investment term, a base currency such as USD or SGD, and a target conversion rate. Depending on gold’s performance against your chosen currency, your returns may be paid in cash or in gold itself. The potential for higher yields makes this approach attractive to those comfortable with some risk and the idea of being repaid in ounces rather than dollars.

If you prefer not to store or insure physical gold, exchange-traded funds (ETFs) and unit trusts offer a more accessible alternative. These funds mirror gold’s market performance without requiring you to hold the metal. ETFs tend to passively track gold prices, while unit trusts are actively managed by professionals who buy and sell gold-related assets on your behalf. They trade easily on the stock exchange, making them a flexible and liquid way to diversify your portfolio. Still, investors should review management fees and ensure that the fund is operated by a reputable institution.

Another indirect approach is through gold mining stocks. Companies such as Barrick Gold (GOLD) and Newmont Corporation (NEM) give investors exposure to the gold industry without owning the physical commodity. Their share prices often move in tandem with gold’s market value, though management quality, operational efficiency, and geopolitical risks can introduce additional volatility.

Should you buy gold in Singapore? Absolutely, but with a clear understanding of what you are buying and why. Gold can act as an anchor in turbulent times, a hedge against inflation, and a stabilizing force in a diversified portfolio. Yet it is not without its challenges. Physical gold lacks liquidity compared to ETFs or stocks, and its price can swing sharply in response to economic shifts.

Ultimately, investing in gold is about balance. It is not meant to replace other assets but to complement them, serving as a steady counterweight when markets stumble. In a world of uncertainty, gold remains one of the few investments that appeals as much to the heart as to the head, a rare blend of beauty and financial resilience.

Image Credits: unsplash.com

Disclaimer: This article is for general information only. Readers should research gold investments in Singapore and seek professional advice before investing. Remember that gold is best viewed as a way to diversify a portfolio, not as the sole safeguard for wealth.

Sources: 1 & 2


Read More...

Singapore Banks Step Up Scam Defenses From Oct 15

From October 15, Singapore’s biggest banks will roll out new safeguards on digital transactions to protect customers from increasingly sophisticated scams. The move comes just weeks after the Singapore Police Force announced that 15 individuals would be charged for suspected roles in scam-related money mule activities. Twelve men and three women, aged between 18 and 35, were arrested in connection with scams ranging from impersonation and job fraud to e-commerce cons and loan schemes, with total losses exceeding S$8.8 million.

Image Credits: unsplash.com

Scams are not slowing down. They have grown more aggressive and more convincing, making it difficult even for savvy customers to tell a legitimate transaction from a fraudulent one. In response, banks are stepping in to close the gaps with stronger protections.

WHAT YOU SHOULD KNOW

DBS, OCBC, UOB, Citibank, HSBC, Maybank and Standard Chartered will enforce stricter rules on digital banking starting October 15. The safeguards apply to current and savings accounts, including joint accounts, with balances of at least S$50,000. If a transaction causes more than half of an account’s funds to be withdrawn within 24 hours, the safeguard is triggered. That transaction and any that follow will either be held for 24 hours or rejected outright. This pause gives victims a vital window to cancel the transfer if they realize they have been scammed.

These measures apply only to digital banking channels such as mobile apps and internet banking, while cash withdrawals at branches and ATMs remain unaffected. The Association of Banks in Singapore, which announced the move on October 3, has cautioned that customers may experience delays in legitimate digital payments and transfers, particularly for large or time-sensitive transactions like property purchases or stock trades. Customers are advised to plan such transfers ahead of time to avoid unexpected costs.

Image Credits: unsplash.com

While the new rules may cause some inconvenience, the scam cases highlight why they are necessary. Security measures already in place prevented an estimated S$78 million in scam losses during the first seven months of this year. Singapore’s financial system is not immune to the global wave of scams, but it has chosen to act decisively. Customers may have to trade a little convenience for peace of mind, and in the fight against scams, that trade-off may well be worth it.

Sources: 1,2, & 3

Read More...