Browsed any online store recently? You’ve probably encountered the enticing “Buy Now, Pay Later” (BNPL) option. With the promise of splitting payments over weeks or months without interest or hefty fees, it seems like a dream come true. For many, it has been. Yet, as it becomes a tool for essentials like groceries, it’s worth pausing to consider: is BNPL as great as it seems?
#1: BUYER’S REMORSE HITS TOO LATE
Remember the days of saving for that dream pair of sneaks, making payments, and only taking them home after they were fully yours? BNPL flips this script. You get your purchase instantly, and with the click of a button, you’re locked into a commitment before common sense kicks in.
If regret creeps in later, BNPL doesn’t care. Essentially, you’ve handed over control of your wallet.
#2: RISKY CONNECTION TO YOUR CARDS
BNPL payments are often tied directly to your debit or credit card. Miss a payment due to insufficient funds? Expect a late fee. Fail to pay off your credit card balance on time? That BNPL purchase suddenly carries a hefty interest charge. What starts as a seemingly free loan could snowball into a mess of late fees and mounting credit card debt.
#3: IMPULSE SPENDING MADE EASY
Saving up for a purchase gives you time to evaluate if it’s truly necessary. BNPL removes that waiting period, nudging you to click buy without hesitation. So, if you’re going to use BNPL, be intentional. A new wardrobe for a job might be justifiable. A shopping spree because it’s interest-free? Not so much.
Image Credits: unsplash.com
#4: HAVING A MINDSET OF “ZERO” INTEREST
While many BNPL services advertise zero-interest payments, not all plans are created equal. Larger purchases, like appliances or electronics, may come with longer terms and interest. Sometimes, the interest rates are even higher than what your credit card might charge.
The trouble? It’s all too easy to click “BNPL” without fully reading the terms. Once the purchase is processed, undoing it can be a challenge.
#5: TRAPPED BY HIDDEN PSYCHOLOGY TRICKS
One of BNPL’s sneakiest pitfalls is how it breaks down costs. A purchase of S$80 might feel like a mere S$20 every fortnight. While this makes items feel more affordable, it also detaches you from the full cost. Couple this with a lack of financial education and relentless advertising, and many see BNPL as a way to manage money. The result? Early reliance on debt and a lifetime habit of paying things off in chunks rather than saving.
Image Credits: unsplash.com
IN A NUTSHELL
Don’t buy it if you cannot afford it. If you’re tempted, ask yourself: Do I truly need this? Can I pay for it outright?
Financial freedom isn’t about splitting payments or juggling debts. It’s about saving and spending within your means. BNPL may be a tool, but it’s not a safety net. In the end, whatever you’re buying will feel far better when they’re truly yours.
In a 2022 survey by the Institute of Policy Studies and Talking Point, 35% of participants admitted to spending more than they earned, with over 60% stating they used to subscribe to “buy now, pay later” (BNPL) schemes. How serious is the prevalence of these schemes? According to the Monetary Authority of Singapore, BNPL transactions reached around S$440 million in 2021. With the growing popularity of BNPL, navigating credit card ownership has become trickier, especially for younger generations.
If you’re a Gen Z, a younger millennial, or a guardian looking for the right credit card for a young adult, consider this guide to credit card recommendations and tips.
START WITH THE ELIGIBILITY
While requirements vary between financial institutions, these are the most common requirements:
a. Minimum Annual Income: typically S$30,000 for Singapore citizens/PRs or S$45,000 for foreigners
b. Minimum Age: at least 21 years old
c. Good credit history: Certain cards may require a solid credit record of several years
IDENTIFY THE RIGHT CREDIT CARD FOR YOU
Identifying the right credit card can feel overwhelming because of the variety of options in the market today. A good place to begin is by examining your lifestyle. Are you a frequent traveler or do you spend more money on groceries? After identifying the factors that matter to you the most, you can shop around and compare each credit card’s features.
On that note, here are some of the best credit cards for beginners in Singapore:
#1: FOR AVID TRAVELERS: KRISFLYER UOB CREDIT CARD
The KrisFlyer UOB Credit Card allows you to earn 3 miles per S$1 spent on Singapore Airlines, Scoot, KrisShop, and Kris+ purchases. Additionally, you can earn 3 miles per S$1 spent on dining, food delivery, online shopping, travel, and transport. For all other spending, you’ll earn 1.2 miles per S$1.
What’s more? From now until 30 Sep 2024, you can take advantage of a promotion offering up to 31,000 miles and a first-year annual fee waiver (worth S$196.20, including GST) when you spend a minimum of S$2,000 within 60 days of approval (T&Cs apply). Apply for KrisFlyer UOB Credit Card at uob.com.sg.
#2: FOR TRANSPORT AND SHOPPING REWARDS: DBS LIVE FRESH CARD
If you are looking for a credit card that rewards you for transportation and shopping, look no further than the DBS Live Fresh Card. It offers up to 6% cashback on transportation and shopping, along with 0.3% unlimited cashback on every eligible purchase. Keep in mind that a minimum spend of S$800 is required, with a cashback cap of S$70.
Best of all? There’s a promotion of S$150 cashback when you spend a minimum of S$800 within 60 days of card approval (T&Cs apply). This promotion is valid until 30 Sep 2024. Learn more about the DBS Live Fresh Card at dbs.com.sg.
#3: FOR ONLINE & IN-STORE SHOPPING: CITI REWARDS CARD
The Citi Rewards Card allows you to earn 10x points or 4 miles per S$1 on online and shopping purchases. You can also earn 1x point for all other spending. Additionally, you can redeem your points for every purchase via the Citi Mobile App. You will get S$1 with every 440 points.
If you’re interested in applying now, you can receive up to S$450 in cash rewards or 5,540 SmartPoints, plus a chance to win a Rolex Submariner Date 126610 (T&Cs apply)! Hurry, as the promo runs until 13 Sep 2024. Sign-up for Citi Rewards Card at citibank.com.sg.
READ THE ANNUAL FEES
Much like the benefits, annual fees vary across credit cards. Some cards offer no annual fees, while others may waive the fee for the first year. However, don’t automatically choose a no-fee card as you need to compare the features before deciding what suits you best.
Pro tip: Sometimes, you can get the annual fee waived simply by requesting it from your bank. It doesn’t hurt to try!
FINAL THOUGHTS
Getting your first credit card is an exciting milestone, but it also brings new responsibilities. As a newbie, it is important to do your research first before committing to a credit card application. Then, always monitor your spending and stay within your credit limit to avoid financial stress. Lastly, make sure to pay off your balance on time to build a solid credit history.
Image Credits: unsplash.com
Disclaimer: All data provided is accurate as of 10 September 2024. Promotional details are subject to change at the discretion of the respective banks. Please conduct your own due diligence when comparing credit cards and their offers before signing up, as individual lifestyles and needs may vary. Use this article as a guide only. Thank you.
Life is full of unexpected twists and turns. Car repairs, medical bills, or maybe that dream vacation you’ve been eyeing—whatever the reason, sometimes you need a little financial boost. That’s where personal loans come in. They provide quick access to cash when you need it most.
But many people find themselves overwhelmed by the sheer number of options and confusing terminology. It’s easy to feel lost or even make a decision you’ll regret later. This comprehensive guide will explain the ins and outs of personal loans, help you understand the key terms, and walk you through the steps to find the perfect loan for your unique situation. Read on.
Understanding Personal Loans
Personal loans serve a specific purpose and can be incredibly handy in the right situation. Several different types are available, each with unique features.
Secured vs. unsecured
Secured loans require you to offer something valuable as collateral, like your car or savings account. This gives the lender a safety net, so they often offer lower interest rates. Unsecured loans don’t require collateral, but they might come with slightly higher rates.
Fixed-rate vs. variable-rate
A fixed-rate loan means your interest rate stays the same throughout the entire loan term. On the other hand, variable-rate loans can fluctuate with market conditions. It might be lower initially, but it could also rise, making your payments unpredictable.
Debt consolidation loans
If you’re juggling multiple high-interest debts (credit cards, student loans, etc.), debt consolidation personal loans could be your lifesaver. You combine all your debts into one loan with a lower interest rate, making it easier to manage and potentially saving you money in the long run.
Here are some key terms you’ll encounter:
Principal: This is the amount you borrow, the core of your loan.
Interest rate: Think of this as the lender’s fee for letting you borrow their money. It’s expressed as a percentage of your principal.
APR (Annual Percentage Rate): This is a broader measure of the cost of borrowing, including both the interest rate and any fees.
Origination Fees: Some lenders charge an upfront fee to process your loan application.
Prepayment Penalties: Some lenders might charge a penalty if you pay off your loan early.
Knowing these terms helps you understand loan offers, compare options, and ultimately make the best decision for your financial well-being. Don’t be afraid to ask lenders questions if anything is unclear. After all, knowledge is power!
Assess Your Financial Needs
Before you apply for a loan, take a step back and assess your financial needs. Start by asking yourself some key questions:
Why do you need a personal loan?
Be honest with yourself. Is it for a home renovation project, consolidating high-interest debt, or covering unexpected medical bills? Knowing your purpose will help you determine the right loan amount and repayment term.
How much do you need to borrow?
Don’t be tempted to borrow more than you actually need. Crunch the numbers and figure out the exact amount required to achieve your goal. Remember, every dollar you borrow will need to be paid back with interest.
How long do you need to repay the loan?
Shorter loan terms mean higher monthly payments but less overall interest. Longer terms offer lower monthly payments, but you’ll pay more interest in the long run.
What is your ideal monthly payment?
Take a look at your income and expenses to figure out how much you can comfortably afford to pay each month. There are plenty of online calculators that can help you estimate payments based on different loan amounts and terms.
Answering these questions will help you narrow down your loan options and choose the one that best suits your situation.
Research Lenders
Each lender offers different loan products with varying interest rates, fees, and terms. It’s crucial to shop around and compare your options to find the best fit for your needs.
Traditional banks
Traditional banks offer a wide range of financial products and services, including personal loans. If you already have a relationship with a bank, they might offer you preferential rates or terms. However, they tend to have stricter eligibility requirements, especially for those with less-than-perfect credit.
Credit unions
Credit unions are member-owned, not-for-profit organizations that often offer competitive rates and personalized service. They might be a good option if you’re looking for a more community-oriented approach.
Online lenders
These lenders offer convenience and speed, with many applications processed entirely online. They may be more flexible with their eligibility requirements, but their interest rates can vary widely, especially for those with lower credit scores.
Peer-to-peer lending platforms
They connect borrowers directly with individual investors, cutting out the traditional middleman (the bank). This can lead to more flexible terms and potentially lower rates, but it’s important to research the platform and its reputation.
So, how do you actually research lenders? Here are a few tips:
Check their websites: Most lenders list their loan products, rates, and terms online.
Read reviews and ratings: See what other borrowers have to say about their experiences with different lenders.
Talk to friends and family: Get recommendations from people you trust. They might have had positive experiences with certain lenders.
Use comparison tools: Many websites and financial tools allow you to compare multiple loan offers side-by-side.
Remember, don’t be afraid to ask questions and negotiate with lenders. You’re the customer, and you have the power to choose the lender that best suits your requirements.
Evaluate Your Eligibility
Lenders have specific criteria they consider in determining whether you’re a good candidate for a loan. Here are the main factors they check:
Credit score
Your credit score summarizes your credit history, including your payment history, outstanding debts, and credit utilization. A higher score signals to lenders that you’re a responsible borrower.
Income and employment history
Lenders will typically ask for proof of income, such as pay stubs or tax returns. A stable job history demonstrates reliability and increases your chances of approval.
Debt-to-income ratio (DTI)
The debt-to-income ratio measures your monthly debt payments (including credit cards, student loans, and potential loan payments) relative to your income. Banks prefer borrowers with lower DTIs, as it indicates they have more disposable income to handle additional debt.
By understanding these factors, you can set realistic expectations and increase your chances of finding a loan that works for you.
Final Thoughts
The path to securing the best personal loan might feel winding, but with a bit of knowledge and the right tools, you can find something that aligns with your needs and financial goals. So, take a deep breath, trust in your newfound knowledge, and embark on your journey towards financial freedom. The right personal loan is out there, waiting to help you turn your dreams into reality.
Using a credit card can be a savvy move for various purchases, thanks to the added security and potential perks. Beyond building a strong credit history, some purchases are best made with a credit card to maximize these benefits.
Many cards offer rewards like points or cashback, which can accumulate over time, essentially giving you “free money” if you consistently pay off your balance without incurring interest fees. Remember to use your credit card wisely!
SCORING EVENT TICKETS
Credit cards often offer special access to event tickets. Many card companies have partnerships with event promoters or venues, giving cardholders the chance to buy tickets for concerts, sports events, and other activities before the general public. Sometimes, there are even exclusive events just for cardholders.
For instance, when Taylor Swift’s concert tickets in Singapore went on early sale, UOB cardholders had the advantage of grabbing tickets before others.
PURCHASE BIG-TICKET ITEMS
When buying big-ticket items like refrigerators, laptops, or other electronics, using a credit card is a great idea. Not only can you earn significant rewards points, but many credit cards also provide additional insurance on these items.
This might include extended warranties that double the manufacturer’s warranty or price protection if the item’s price drops shortly after purchase.
MAKE TRAVEL ARRANGEMENTS
Booking travel with a credit card can offer substantial benefits. Many cards provide travel-related perks such as trip cancellation or interruption coverage, lost luggage insurance, and even emergency medical coverage. These benefits can save you from purchasing separate travel insurance.
Travel-themed credit cards typically offer higher rewards points for travel-related expenses. Plus, a credit card is often required to secure bookings for flights, accommodations, and car rentals.
SECURE OVERSEAS PURCHASES
Credit cards are generally more widely accepted than debit cards when traveling abroad. They are also safer to carry compared to large amounts of cash, as lost or stolen credit cards can be cancelled easily. Some credit card companies offer favorable exchange rates, providing additional savings.
Before traveling, notify your credit card provider of your itinerary to avoid any security issues or hindrances with your card while overseas.
ADD TO CART
Using a credit card for online shopping offers several advantages. Credit card transactions are easier to trace and often come with protections against fraudulent charges. Many cards also provide insurance for items lost or damaged in transit.
Always ensure that you never send your credit card information over email or text to safeguard your details.
CHARGE YOUR BUSINESS PURCHASES
For business owners, using a credit card to manage expenses can simplify accounting and help build business credit. Many business credit cards offer cash-back rewards or statement credits for purchases like internet services, cell phone plans, and office supplies, which can aid in tracking and managing cash flow.
Using a dedicated business card for recurring expenses can also help with tax deductions.
PROTECT PHONE PURCHASES
If you enjoy buying products via home shopping channels or infomercials, always use your credit card. This provides protection if you don’t receive the item or if it doesn’t match what was advertised. Credit card protections can save you from potential scams or disappointments from phone orders.
Image Credits: unsplash.com
Using your credit card for these types of purchases can provide additional security, rewards, and peace of mind, making it a smart choice for managing your finances.
Congratulations on reaching the incredible milestone of owning your new home! As you stand in your living room, envisioning it as the perfect spot for get-togethers, reality sets in. Do I have the budget needed to create my dream home?
Sounds familiar? Well, you’re not alone.
Many of us have found ourselves in this situation. We need a temporary cash boost for home improvements but, at the same time, are hesitant to rely on awkward favors from friends or family members.
That’s where borrowing smart comes into play. Here’s why GXS Bank, Singapore’s home grown digital bank, might have the best solution for you.
The Best Friend To Borrow Money From
Borrowing from those close to you can be a double-edged sword. It might be easy to get that “loan” but fail to fully understand the unspoken terms, or worse, be late in paying them back, and you could end up with a very strained relationship. This is where GXS FlexiLoan steps in, like a trusted friend who understands your needs but less the drama.
The GXS FlexiLoan lives up to its name by being incredibly flexible. Whether you need a small amount for a quick fix or a larger sum for a home renovation project, it’s there to support you.
Why GXS FlexiLoan stands out as the ideal financing option:
Flexible Borrowing
Borrow what you need, when you need it, for however long you need it
When it was launched, the GXS FlexiLoan was hailed as a revolutionary game-changer in personal finance. It is the first financing option in the market that lets you tailor your borrowing experience according to your individual needs.
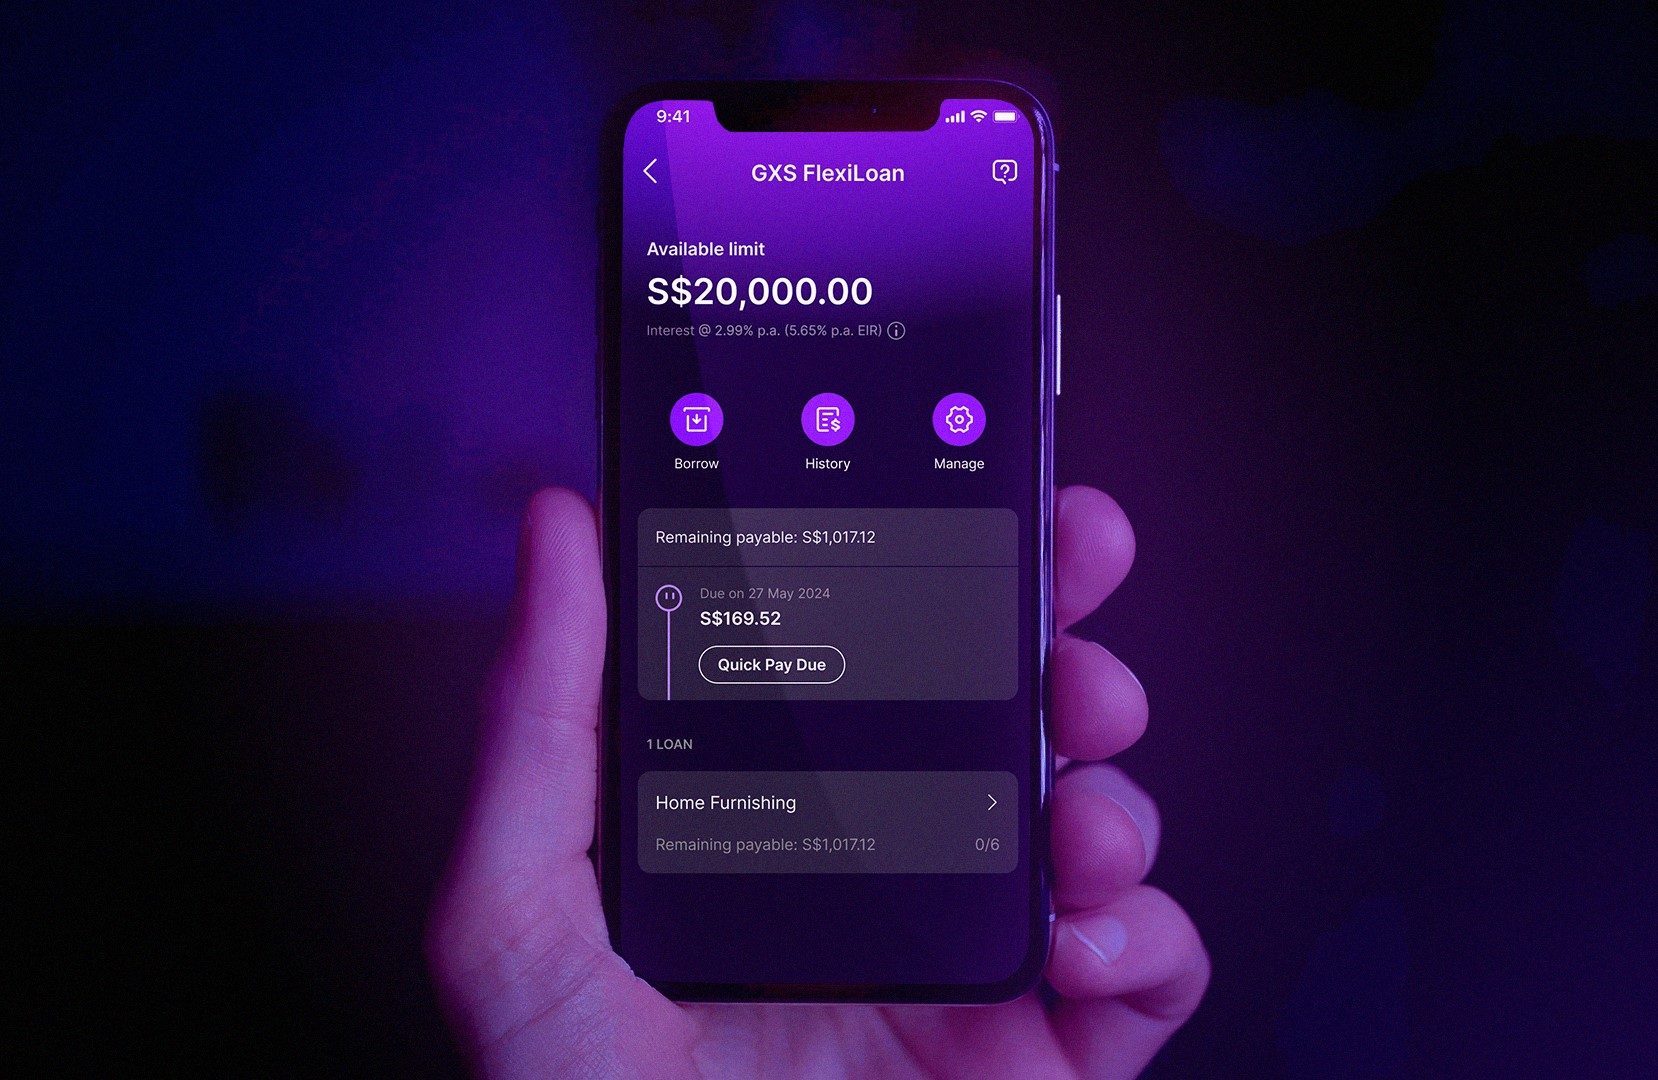
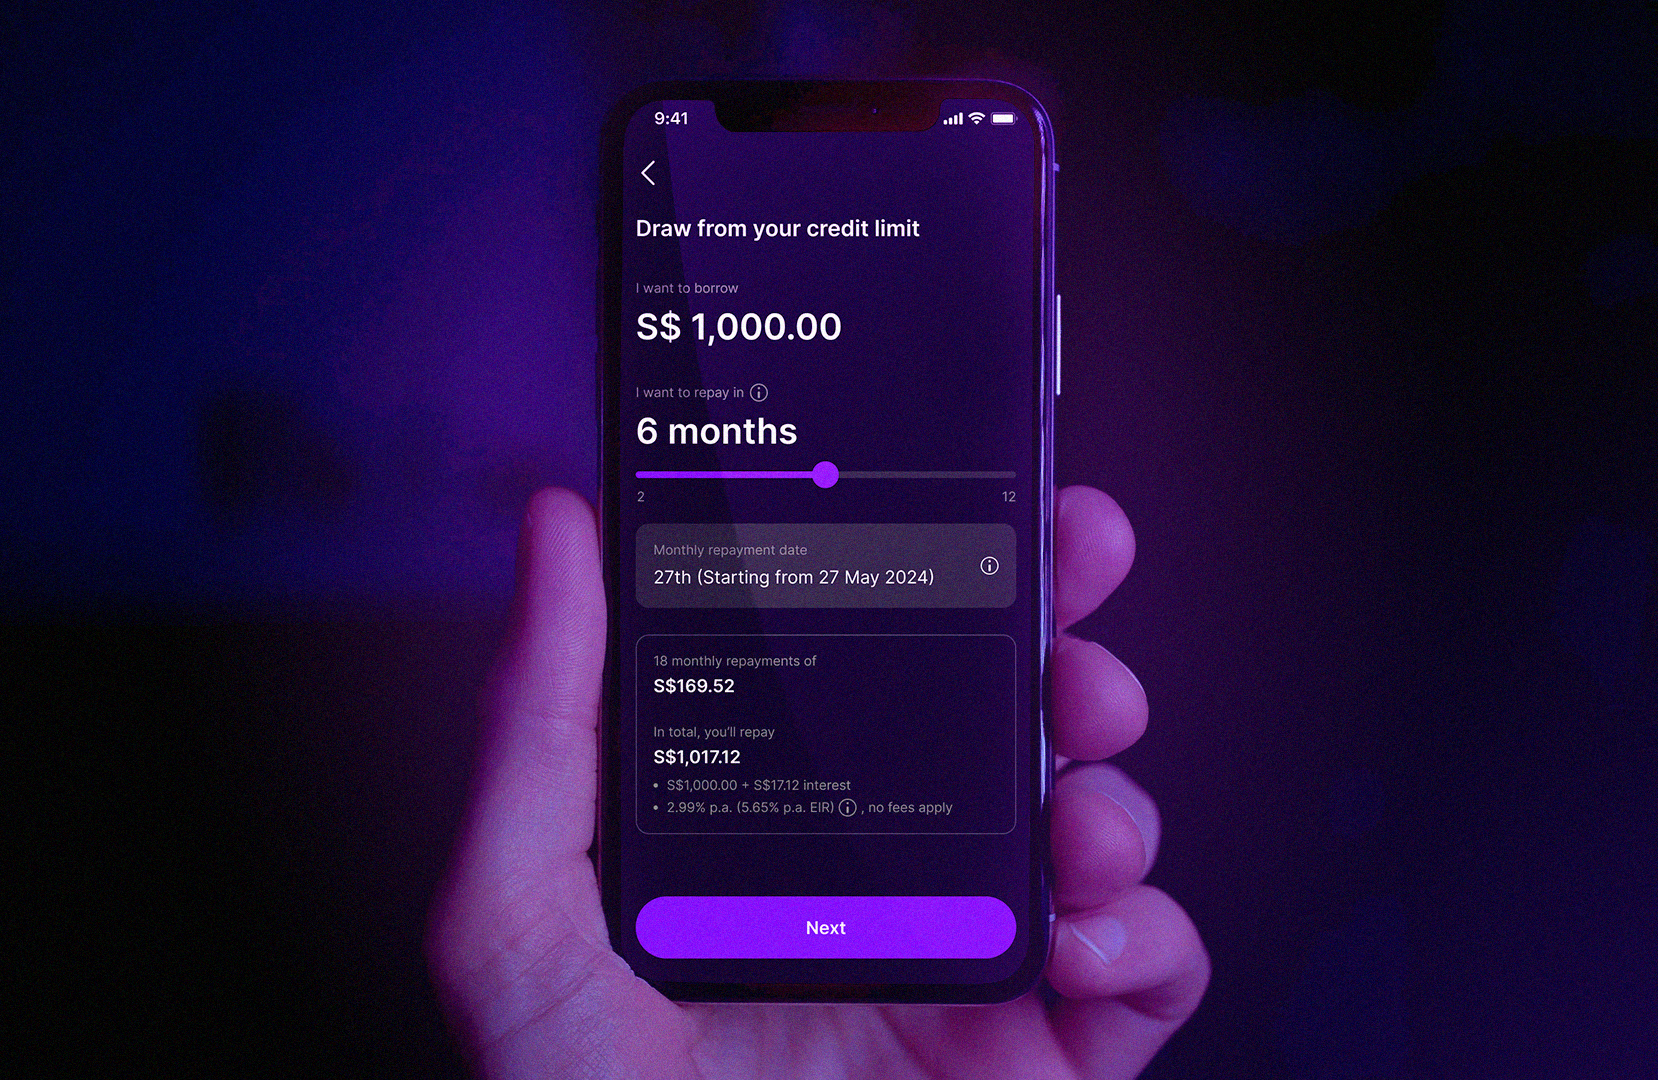
Think about it – a renovation loan typically has a higher loan quantum that is more suitable for larger renovation projects. If you just want to upgrade your kitchen or create a cozy haven in your living room, you might not need such a large quantum. The GXS FlexiLoan puts control in your hands and allows you to draw down multiple loans from your credit line starting from as little as S$200, up to $100k (subject to your available credit limit). GXS FlexiLoan has got your back, on your terms.
Low Interest Rates
Interest rates start from as low as 2.99% (EIR 5.65% p.a.) which is lower than the interest rate you’d pay if you used your credit card. By taking advantage of competitive rates, you can save on interest costs, and stretch your renovation dollar.
With GXS FlexiLoan, you call the shots. Imagine you’re in the midst of your home renovation project, and you want to establish a clear timeline with your interior designer to keep track of progress.
The GXS FlexiLoan is designed to let you call the shots on how much and how long you want to take up the loan. This means you have the power to align your repayment plan with your renovation timeline. Want a shorter repayment period of 2 months to swiftly tackle smaller upgrades or an extended tenure of up to 60 months for comprehensive renovations? The choice is yours.
No Early Repayment Fees
Why pay more when you can save on interest?
You can enjoy interest savings with GXS FlexiLoan because interest on the loan is calculated daily, based on the outstanding balance at the end of the previous day, without compounding interest. This means that if you make an early repayment, the outstanding balance is reduced, resulting in immediate interest savings.
Moreover, there are no early repayment fees, giving you added financial benefits and motivation to settle your loan sooner. This way, you can allocate more funds towards your home renovation project and achieve your dream space without unnecessary financial burdens.
No Hidden Fees
Suppose you’re still not ready to take the loan immediately, there’s no need to worry because, with GXS FlexiLoan, you have the option to apply beforehand and keep it as a reliable standby credit line. There will be no interest charged till you make a drawdown, giving you peace of mind as a backup during your renovation journey.
Limited Time Offer
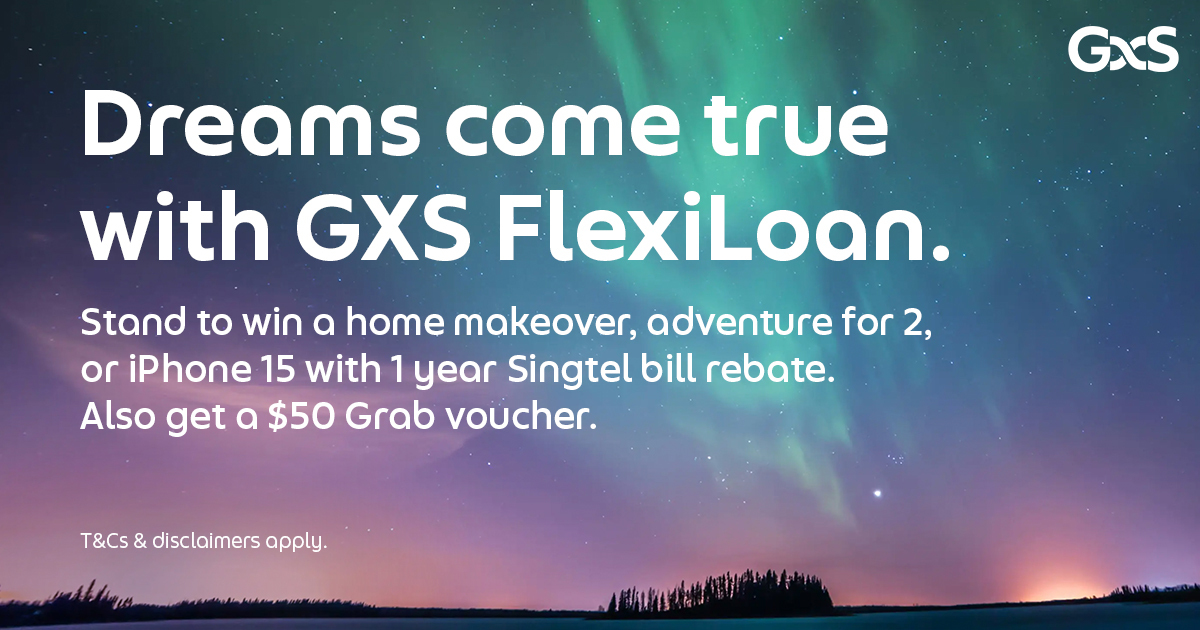
From April 3rd till June 30th 2024, when you sign up and use your GXS FlexiLoan, you stand a chance to win fantastic prizes in their dream giveaway. Prizes include a dream home makeover, a thrilling overseas adventure for two, an iPhone 15 with free Singtel mobile postpaid bills for a year. You also stand to get a S$50 Grab voucher.
Apply via the app which it is available for download on:
For more information, and to check the results of the giveaway, check here
Visit www.gxs.com.sg/flexiloan for the full terms and conditions, and start your journey towards financial empowerment today.
Footnotes: GXS is a digital bank proudly backed by Grab and Singtel. GXS FlexiLoan is provided by GXS. GXS holds a banking licence and is regulated by the Monetary Authority of Singapore. GXS is a separate entity and is not associated with the businesses of Grab Holdings, Singtel, and their entities, or Money Digest.
Terms and conditions apply. For the full terms and conditions on GXS FlexiLoan and the campaign, visit www.gxs.com.sg/flexiloan. All figures in the images are illustrative only.