World Value Invest Fest 2015 Power Lessons [David Kuo]

Previously we explored into the mind of Warren Buffett through Mary Buffett’s invaluable lessons on Mr Buffett’s Value Investment Methodology and some of the power pointers on how to select a company to invest in. This time, let’s draw from David Kuo’s experience on Managing Risks In Stock Investing!


What is ‘Risk’?

A term we hear too often, yet never really having a perfect definition of what risk is. There are so many types of risks out there and how do we effectively manage all of them at once? Almost impossible! At best, we can mitigate them, but probably not completely eliminate them. But what good is identifying all the various types of risks affecting you, when you fail to know yourself? Risk profiling. If we don’t even know what is our risk profile, how can we select investments that have risk profile that is aligned to our own? Is it important for them to be aligned? Definitely! Say a 65-year old man who wants to invest his retirement fund for income, would you recommend him to buy speculative stocks with P/Es in the hundreds and no fundamentals? Of course not! Similarly, have we overlooked the risk of not a comprehensive risk profiling of ourselves and check if our investment decisions are aligned?


Different Strands of Investing for Different People!

There are so many different strands of investing:

  • Growth
  • Income
  • Blue Sky (Start-ups)
  • Sideways
  • GARP (Growth At Reasonable Price)
  • Bottom-Up
  • Top-Down
  • Value
  • Index Trackers

You don’t have to be afraid that you won’t find one that doesn’t suit you! First you need to identify where you are in life, what your investment goals are, and how much risks are you willing to take on to achieve your investment goals. Different strands of investing entails different risks and requires different investment mindset and strategies. Identify the strand that you want to focus in, read up on the skills and mindset required for the different strategies. For example, Index Trackers would adopt a very different mindset require a different skill set from Value or Growth investing. Index Trackers take on a more passive approach towards investing while gladly accepting the diversification it provides. Growth and Value Investing however requires the ability to not just read financial statements, but also, understand business as a whole and consider it from the point-of-view of a businessman. Both method works, but it depends on your investment goals. Are you trying to get from rags-to-riches? Or do you want to simply take a back seat and enjoy the ride? There’s no right or wrong, but it’s worth exploring and knowing yourself a little more.


How To Avoid Panicking

David Kuo shared this very powerful quote which many of us tend to forget – “Do not confuse the price of the stock with the story behind the stock.”

Indeed, does the price of the stock dictate the story behind the stock, or is it the other way around? If you only knew the price of the stock and not the story behind the stock, you would definitely panic because you have nothing to fall back on! David emphasises on the importance of knowing why you bought your stocks in the first place. If you knew the story behind the stock, would a falling price cause you to panic or would you see it as an opportunity to buy more at a cheaper price? If you knew the story, you would at least have the mental and emotional capacity to ride out the rough patch, having quiet confidence that the company’s results will show for itself in the long-run. “There will be delays in our investing journey”, so ALWAYS have a margin of safety! If we can’t eliminate, at least mitigate the temporary losses! Lastly, ask yourself, do you have the courage to invest when times are bad? 🙂
Read More...

World Value Invest Fest 2015 Power Lessons [Mary Buffett]

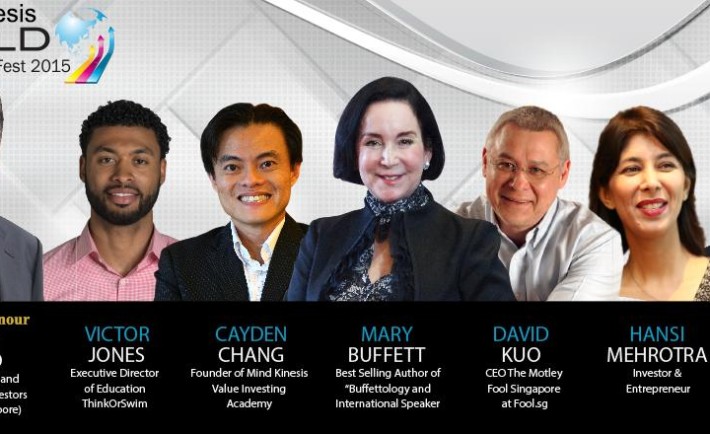
With the recent conclusion of Value Invest Fest 2015 hosted by Cayden Chang, the founder of Mind Kinesis Value Investing Academy, alongside with many world renowned speakers including Mary Buffett and David Kuo of The Motley Fool, I picked up many lessons and wish to pass on their invaluable lessons taught to you! Many topics were touched on during the conference, including funds, portfolio management, investment principles, and even financial planning. It was a very comprehensive package in my opinion and I can’t wait to share! So let’s get started!

Mary Buffett

On Mary Buffett’s part, she taught mostly on how to select a company to invest in. As a protege to Warren Buffett, it’s not surprising that she emphasises on what Warren Buffett teaches in his books. Some of the key pointers were these:

  • Management – Understand the management and how the organisation provides value to its investors. Are the corporate actions taken to value-add to its investors or are they spending at the expense of investors’ money?
  • Think long-term! – Always begin your investment from a business perspective. An investment is most successful when it is most business-like. When she mentioned long-term, she also meant to buy into a company that you would never want to sell.
  • Circle of Competence – Once again, like what Warren Buffett always say, invest based on your circle of competence. Why spend so much effort on an industry or company you don’t understand at all? There are thousands of companies listed around the world and there will be bound to be a company that you can understand! So don’t force yourself to understand a business that you can’t.
  • Margin of Safety – Always purchase companies at a price with a margin of safety. Stock Price < Intrinsic Value. Note that there are many different angles to look at when considering margin of safety. Examples such as P/E and PEG are the commonly used ratios to determine margin of safety. Depending on how in-depth you want your margin of safety to be, decide on the number of variables to factor in.

Warren Buffet’s Value Investment Methodology

Mary then goes on to discuss more in-depth what to look out for in a company:

  1. Buy into companies that have a durable competitive advantage. This means to buy into companies that have the ability to raise prices and people would still buy them with little competition. They tend to be items of necessity or even strong brand names. The idea is to find companies that own a piece of the consumers’ minds. Examples would be Gilette for shavers, Kleenex for tissues, Panadol for paracetamol. Get the drift? The first brand name that comes to your mind when you want to buy an item.
  2. Buy into companies that have predictable and consistent earnings. She continues by mentioning that compound growth is the key to long-term success, CAGR.
  3. Buy at a good price. This is from the wise adage of Benjamin Graham, “The future value of every investment is a function of its present price. The higher the price you pay, the lower your return will be”

And of course, how could she miss out on the 2 Rules of Warren Buffett?

Rule #1: Never lose money.

Rule #2: Never forget Rule #1.

At closing, she reminded us that Value Investing requires a lot of patience and discipline. Would you be patient enough to wait for the stock price to come to a discount? Would you have enough discipline to stick to your investment methodology? “It’s easier to stay out of trouble than to get out of trouble”. Don’t be too eager to jump into a trade or investment! She ends her speech by reinforcing the importance of educating ourselves. The more you learn, the more likely you will earn! Remember, a lack of knowledge is risk itself! Since we can’t control inflation risk or corporate risk, work on something we can. Ourselves! Stay tune for more lessons on the other speakers like David Kuo of The Motley Fools!

Read More...

Is Property A Viable Investment Tool?

A place where you can securely reside with your loving family – that is what you call a home.

Since land is scarce in Singapore, properties had always been a go-to investment tool for many. The majority of these investors have strategies limited to purchasing, reselling, and renting flats or condominiums. But, in order for higher returns to generate, one must consider investing to a range of other properties such as using the Real Estate Investment Trust (REIT).

And for a beginner with merely S$10,000 on hand, is property a viable and smart investment tool?

PROS

1. GETTING MORE LEVERAGE

With the banks help, you can have the ability to leverage your capital, make a down payment, and increase your overall return. Simply, more leverage enables you to pay less money upfront (e.g., 30% down payment and 70% from the bank) while making more money in the process.

2. CAN BE A SHIELD AGAINST INFLATION

Inflation occurs when there is a spike in prices and fall in the purchasing value of the dollar. As the miscellaneous for the property increases, the rent, and its value also increases. This is why property investing can be a good shield against inflation.

Image Credits: .Martin. via Flickr

Image Credits: .Martin. via Flickr

CONS

1. CAN BE TIME CONSUMING

Finding a property in a decent location, building a good relationship with the tenants, and maintaining the condition of the property can be time consuming. Time that may not be in the good side of most.

2. THE RISKS ARE HIGH

A two-bedroom HDB flat can cost about S$250,000. That is a huge sum of money you may be willing to risk if you are serious in property investing. The risks only increase when the investor does not understand how the property market works or when and where to invest. Hurrying up without analyzing the situation thoroughly can only bring about more damage (e.g., bankruptcy) than good.

ULTIMATELY

You can lower the risk of property investing by diligently researching and analyzing reports, tests, and the current situation. Furthermore, investing in below market value properties backed up with insurance can help manage the risk. You would not know all these things unless you are well informed!

A buyer with an in-depth financial knowledge is important to the success of a property investment. So, if you lack sufficient knowledge, seek advice from a financial consultant or other professional advisers. And, when you find the “right property”, ensure that you keep your expectations realistic and keep your finances in tact.

Sources: 1, 2, & 3

Image Credits: Mark Moz via Flickr

Image Credits: Mark Moz via Flickr

 DISCLAIMER: THIS ARTICLE DOES NOT FORM PART OF ANY OFFER OR RECOMMENDATION, OR HAVE ANY REGARD TO THE INVESTMENT OBJECTIVES, FINANCIAL SITUATION, OR NEEDS OF ANY SPECIFIC PERSON. BEFORE COMMITTING TO AN INVESTMENT, PLEASE SEEK ADVICE FROM A FINANCIAL CONSULTANT OR OTHER PROFESSIONAL ADVISER.

Read More...

How to diversify your investment eggs with $1,500

Singapore may be the world’s most expensive city, but to lead a reasonably comfortable life may not be impossible. It takes significant forward planning and a strict adherence to one’s investment principles to achieve a desirable outcome. This article – the third in a five-part series that continues from “How to maximize your life with a $3,000 paycheck”- will thus explore the different ways to diversify and maximize your returns on a $1,500 monthly “investment budget”.

Image credit: blog.propertyguru.com.sg

Image credit: blog.propertyguru.com.sg

  1. Property

A home not only provides a physical shelter, but also instills a sense of belonging and emotional attachment in the members of a family. Therefore, this prized asset is arguably the main driving force that motivates people to work hard and tirelessly, which forms the bedrock of our prosperous society. At the same time, it makes sense to allocate a lion’s share of the investment budget equivalent to 40% or $600 to property. Given that 23% of the wages that are allocated to the Ordinary Account can be used for housing, which thankfully exceeds the regular 20% employee’s CPF contribution, no further action needs to be done to set aside any disposable income for the property budget. Since the CPF savings in the Ordinary Account yield a guaranteed annual interest rate of 2.5%, this should form the benchmark on which the returns of the alternative investment vehicles shown below are based.

Image credit: gelvininfotech.com

Image credit: gelvininfotech.com

  1. Stocks

Evaluating a stock is akin to evaluating your potential life partner. You need to understand it well before you are able to pass a well-informed judgment – to buy, sell or keep in view. And for most working adults, time constraint is a persistent bugbear. But keep your heads up. You just need to stay focused on certain options (both in the arenas of investment and love). Choose the industry that you are familiar and confident with – especially if you are working in that sector or make friends in the sectors that you are interested in – and share the exclusive knowledge and expertise with your selected group of friends to leverage on the pooled insights. Besides that, running checks on the consistencies of the historical dividend yields and the shareholding information of the top management executives of the publicly listed company is pivotal. These track records offer an ultimate backstop when things go awry by providing “consolatory recurring dividends” and a “management confidence boost” (assuming that these companies are content with the status quo). Allocate 35% or $525 monthly to your share investment budget. Engage in the due diligence process while gradually building your ammunition to purchase stocks that offer at least 2.5% dividend yield.

Image credit: pondicherryurbanbank.in

Image credit: pondicherryurbanbank.in

  1. Fixed deposits

While most fixed deposit interest rates are considerably lower than 2.5% and grimly sufficient to beat inflation, it is nevertheless a secure source of income, especially during a recession where stock prices and incomes are falling. Moreover, it offers flexibility as you can decide on the tenure of your fixed deposits that ranges from 30 days to 10 years. Therefore, cap your downside risks by designating 15% or $225 to fixed deposits and be assured of the steady returns to this investment.

Image credit: forbes.com

Image credit: forbes.com

  1. Savings account

Saving up for a big ticket item like the upcoming iPhone? The remaining 10% or $150 should not be tied up in any illiquid investment vehicles. It is a good financial management practice to reserve a small portion of the investment budget every month for the pursuit of the latest trends or luxury indulgences instead of bursting your credit card limits on such occasional treats.

While these measures may not propel you to the top 10% of the Singapore’s population, they serve as a general guide to better manage your finances. As always, sheer hard work and discipline rule the day.

Read More...

The Wondrous Modern Uses of Gold

Gold is probably the most vaunted precious metal most people are familiar with. Indeed, grannies love to don this prized jewellery around their necks while grandpas revel in displaying their wealth with their 18K golden Rolexes.

But this is not all. Gold has far more phenomenal uses than you can ever imagine. And this is part of the reason why the price of gold has not fallen beyond S$1,450 per ounce for the past 5 years.

Image credit: luxpresso.com

Image credit: luxpresso.com

  1. Most electronic devices

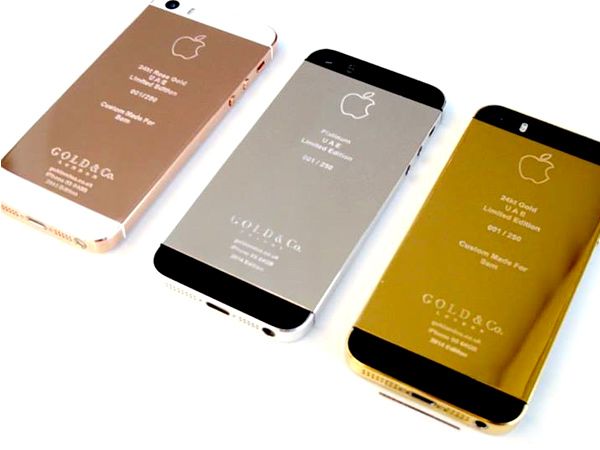
While 78% of the gold consumed every year is used for jewellery, the most significant industrial use of gold is manifested in electronics. Gold is a highly efficient conductor of electricity, only second to silver and copper. From pocket electronic gadgets to large electronic appliances, gold shows up in almost all of them, albeit in minute amounts. If you own a mobile phone, a calculator, a computer, a global positioning system unit and a television set, you are definitely a proud owner of gold. But the reason for the hefty price of iPhone 6 Gold does not lie in the gold content, for most of the mobile phones merely contain around 50 cents worth of gold.

Image credit: blog.badonlinedates.com

Image credit: blog.badonlinedates.com

  1. Medical uses

Want a vibrant golden smile? Dentists are still using gold alloys for tooth fillings, crowns, and bridges because gold is durable, non-allergenic and corrosion-free like silver and platinum. Many surgical instruments and life-support devices are also manufactured with tiny amounts of gold. Gold is a component in drugs to treat medical conditions such as the joint disorder arthritis by reducing swelling, bone damage and relieving joint pain and stiffness. For the diagnosis of diseases, gold is also injected into the body in its radioactive form.

Image credit: goldresource.net

Image credit: goldresource.net

  1. Aerospace

Have you ever thought of what space vehicles are made of? Many parts are actually fitted with gold-coated polyester film to reflect infrared radiation and stabilize the temperature of the spacecraft or risk overheating. As gold is malleable, it also acts as a lubricant between the mechanical parts of the spacecraft in orbit.

Before committing to any investment, it is always prudent to find out the uses of the particular financial product. It allows you to project its future returns more accurately based on economically sound fundamentals instead of sheer speculation. It is also critical to know the relationships between gold price, U.S. dollar and interest rates. The appreciating dollar and prospects for higher U.S. interest rates have curbed gold’s gleaming appeal as a protection of wealth and led to its price decline. Finally, given that the biggest consumer markets are none other than India and China, their economic growth would inevitably impact the gold price significantly.


Read More...