4 essential economic relationships Singaporeans need to know

Featured Image Economy

We frequently hear of the word “economics” in papers or conversations, but how useful or applicable is this course of study to the real world?

Understanding economics is in reality fundamental to understanding the price movements of every single good and service in our economy. It is the aggregation of the demand and supply forces.  Indeed, when we see the airfare skyrockets after the end of school term, it is economics at work. Huge travel demand outweighing limited supply of passenger seats leads to propped up prices. As such, appreciating and capitalising on economic knowledge could end you up in deeper pockets.

While it may be too time consuming and superfluous to master all the economic theories, knowing a few essential concepts may come in handy in guiding our financial and behavioral decisions.

  1. Inflation and savings
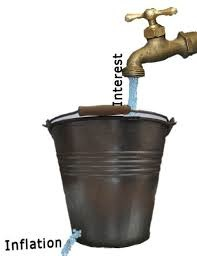
Inflation and Interest

(Image credit: http://inflationdata.com)

Thanks to the prudent policies administered by MAS,  Singapore enjoys a low inflation rate of 2.8% on average since 1962. However, a simple comparison between the interest rates offered by various banks indicates a mere 1.3% as the most competitive rate for 1-year fixed deposits.

What this means: The fund sitting in your bank is losing 1.5% of its value to be exchanged into goods and services annually. Given that you have $100 in your bank today, you can afford to buy 50 McChicken burgers. But one year down the road, you can only afford to purchase 49.25 of them.

Course of actions to be taken: Since the saving rate is not commensurate with the inflation rate, we may be better off investing in alternative assets  that provide higher yields. However, if every rational and irrational soul is doing that, risks abound as illustrated below.

  1. Stock investment
Stock Investing

(Image credit: thenest.com)

Investing in stocks can yield 2 kinds of returns, namely dividend yield and capital gains yield. The former tends to be more predictable than the latter, especially if the company holds a long term track record of constant or growing dividend stream.

How to value stocks: Dividend yield is an objective measure in guiding investment decisions since they are realised returns and a better indicator of future returns. On the other hand, be extra cautious during stock encounters with historically impressive capital appreciation. Gullible investors may be tempted to buy these shares as they often fail to realise  the high variability of capital gains yield could be complicated by the problem of information asymmetry where insiders possess and exploit private information to the disadvantage of outsiders.

Course of actions to be taken: Both insiders and outsiders have to keep abreast of news and developments in the macroeconomy and international economies as they affect stock returns systemically.

Specifically for outsiders, it is crucial to have a good grasp of the economic fundamentals (such as the consistency of dividend payouts and growth potential) of the company that helps to steer towards a proper valuation. A long term investment horizon is more favourable as it puts them on a more level ground with the insiders. If the outsiders were to invest in the short term, speculation is usually involved since by definition, the fact that they do not possess the superior private knowledge is prejudicial to them.

  1. Property investment


For more well-heeled investors looking to diversify their portfolio, real estate investment seems the way to go. Similarly, real estate assets provide 2 types of returns, specifically rental yield and capital gains yield. Best of all, a residential property provides its owner(s) a physical shelter to live in. Despite these benefits though, investors should be wary of overpaying for homes.

How to value property: Rental yield is an objective measure in guiding investment decisions since it measures the payback period of the hefty mortgage loan that homebuyers commit to. The URA Masterplan and a concise understanding of demographics are vital tools in predicting the capital gains yield.

Course of actions to be taken: Beware of one-off anomalous sale transactions that are not reflective of the true market forces. Stay out of homes in which the overinflated prices are not underpinned by strong economic fundamentals  (such as location, amenities and size). Buy during a recessionary period instead of an inflationary period. Timing the market makes an enormous difference in your bank account.

  1. Employment

Investments aside, most of us contribute to the economy through our employment. But to maximise the return on our faculties and time,  insights have to be drawn from the demand and supply forces.

Some simple mathematics to gauge how financially rewarding is a particular industry: If the staff turnover is high (due to long working hours, poor welfare, unchallenging job roles etc.), companies should offer higher wages to attract or retain workers.

However, this is not happening. Reason being a ready supply of potential (local and foreign) employees provides  virtually no impetus for corporations to raise salaries. Does this plight sound familiar?

Course of actions to be taken: Instead of complaining about meagre wages, pursue a career in an alternative industry with market dynamics (i.e. less competition) working in your favour. Although it may seem counter-intuitive, you actually build greater wealth bucking the norm and doing what others don’t do.  Better still, venture into a new industry and gain the first mover advantage.

Now you see, having a good understanding of economics is useful in our day-to-day living as it forms an integral basis for making financially sound decisions.


Read More...

Leading Fixed Deposit Rates In Singapore

First, you must know the nature of fixed deposits (FD), its advantages, and disadvantages. A fixed deposit is a financial tool offered by the bank, which, provides clients (like YOU) with a higher rate of interest than a savings account.

In Singapore, a minimum deposit of S$1, 000 is required to open an account. The fixed deposit rate will only be given within a maturity term. The term ranging from 1 to 36 months depends upon your bank here. Once the money matures, you will get back your initial deposit with the interest.

FD’S ADVANTAGES

a. SAFETY

Fixed deposit is a more stable and safe route than other investments. Since not everyone is willing to risk it all with bonds and property investments, fixed deposits offer guaranteed money back.

b. WORKABILITY

Because the rates vary based on the time on hold, the amount you put in, and the bank you chose…there is a good chance to get the highest interest rate possible. All you have to do is to research and compare the workability or flexibility of the FDs available.

c. LIQUIDITY

Your money that resides in a fixed deposit account is a surefire liquid asset (i.e., can be converted to cash). So, after the money matures, you can withdraw cash for any purpose such as weddings or medical emergencies.

FD’S DISADVANTAGES

a. NO DIVERSIFICATION

If you invest all of your wealth to FDs then, you will not indulge on the benefits of diversification. Diversification is having investments in real estate, gold, and stock markets.

b. VULNERABILITY TO INFLATION

The returns of the FDs are lower if the inflation is very high. To put it in perspective, the interest rate may not change but you will still lose money if the Singapore dollar significantly drops.

To the most exciting part, we shall go…

LEADING FIXED DEPOSIT RATES IN SINGAPORE

Here are the banks that provides the best interest rates if your savings is S$10, 000 within an annum:

1. RHB Singapore Dollar Time Deposit

Interest Rate: 0.63%

Returns: S$63

2. CIMB Why Wait Fixed Deposit-i Account

Interest Rate: 0.50%

Returns: S$50

3. UOB Grand Senior Citizens Fixed Deposit

Interest Rate: 0.38%

Returns: S$38

4. Standard Chartered Singapore Dollar Time Deposits

Interest Rate: 0.35%

Returns: S$35

Here are the banks that provides the best interest rates if your savings is S$100, 000 within an annum:

1. CIMB SGD Fixed Deposit

Interest Rate: 1.30%

Returns: S$1,300

2. Maybank iSaVvy Time Deposit

Interest Rate: 0.85%

Returns: S$850

3. Maybank Singapore Dollar Time Deposit

Interest Rate: 0.70%

Returns: S$700

4. Bank of China SGD Time Deposit Account

Interest Rate: 0.60%

Returns: S$600

Image Credits: Will Clayton via Flickr

Image Credits: Will Clayton via Flickr

The data above goes to show that the strength of the fixed deposit rate truly varies upon the amount you saved and the bank you chose. Hence, it is important to educate yourself first before diving in. ☺

Sources: 1, 2, & 3

Read More...

3 Investments You Should Immediately Consider

Investment is an asset purchased with a purpose to generate more income in the future or to sell it for a higher price. There are a myriad of investment selections available in the market today but here are a few 3 simple investments you can start with…

1. MUTUAL FUNDS

Being a newbie in the investment scene is not a problem anymore. With Mutual Funds, you can entrust a professional investment manager to produce capital gains for you and your co-investors. Mutual funds are investments that gather the investors’ money into a pool to make multiple types of investments, known as the portfolio. Shareholders participate proportionally in the gains and losses. Lastly, it gives the budding investors the access to professionally manage, diversified portfolios of equities, bonds and so on. This can be difficult and nearly impossible to create with a small amount of money.

2. CENTRAL PROVIDENT FUND INVESTMENT SCHEME

The Central Provident Fund (CPF) Investment Scheme is a way to invest your CPF savings to various banks such as OCBC, DBS, or UOB. This will enhance your retirement or housing money. Simply, the money you will generate from your investments will eventually go to your CPF account and not your pockets. To be eligible, you need to be above 18 years old and have over S$20,000 in your Ordinary Account (i.e., used for housing, education, investment, and insurance) and over S$40,000 in your Special Account (i.e., used for retirement). Compare the investment options and their charges. Instead of complaining about the CPF, why don’t you start investing?

3. REAL ESTATE INVESTMENT TRUSTS

Real Estate Investment Trusts (REITs) allows you to invest your money to a range of properties. REIT investors pool their money to buy buildings then, they divide the rental returns. This is a cheaper alternative to buying a property. Furthermore, REITs receive special tax considerations and mostly offer investors high yields and liquid method (i.e., converting your assets into cash) of investing in real estate. Although there are benefits, it is important to hire a trusted REIT Manager. One REIT in Singapore is CapitaMall Trust including properties such as Plaza Singapura, Junction 8, and JCube.

Image Credits: www.rentalrealities.com via Flickr

Image Credits: www.rentalrealities.com via Flickr

Sources: Central Provident Fund Board, MoneySense, and Investopedia

This article does not form part of any offer or recommendation, or have any regard to the investment objectives, financial situation or needs of any specific person.  Before committing to an investment, please seek advice from a financial or other professional adviser.

Read More...

TA: Introduction to Trend Lines

You’ve probably heard about Technical Analysis from my previous articles and may be wondering to yourself, “How should I begin?” I feel that a great start would be learn about Trend Lines because it is the first step to knowing what Support and Resistance mean. You may wonder why is it important, and I hope that by the time you reach the end of the article, you would see it’s effectiveness and be convinced yourself. Perhaps, even try it out for yourself! I have been using trend lines faithfully and they have always served me well in my investments.

What are Trend Lines?

Trend lines are basically lines that you draw on charts that shows you the general direction of a trend. It is useful to help find potential support and resistance levels so you can time your entry and exit better. And the best part of it all, it’s not hard at all and can be performed on any charts! All you need to do is to find the best fit support or resistance line via trial and error by connecting the bottoms or tops of a trend. Here’s an example:

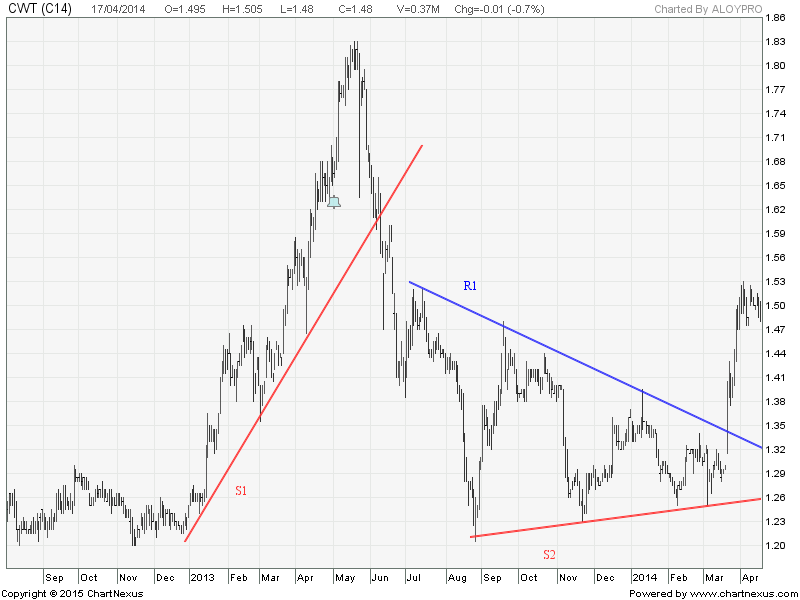
CWT Chart


Here I have presented you with a chart that shows you two support lines (S1 and S2) and one resistance line (R1). It definitely doesn’t look too hard to draw isn’t it? Simply connect the bottoms of a trend and there you have it, a beautiful trend line that can help you spot the next bottom to enter your trade! You’ve always heard of people trying to “time the market”, this is one of the ways traders time their trade. Take for example the trade towards the right of the chart, at S2. Look at how easy it would have been for traders to time their entry and exit just by drawing two lines! Buy when it touches S2, and sell when it touches R1.

Trend Lines Keep Changing!

Had you not drawn the trend lines, would you have known at what price you should enter and at what price you should have exited at? Drawing trend lines help to clearly show where the next potential support and resistance will be at. I place emphasis on the word “potential” because it is not a guarantee that the trend will stay the same forever. Look at S1, it stayed in effect for about 6 months before the trend line is broken, and then we ignore S1 and move on to S2. Same goes for R1 where it was effective for 7 months before it was penetrated in mid-March. This penetrating move then renders R1 meaningless now while S2 is still in play because it hasn’t been breached.

It’s All About Practicing

I understand it can get a little confusing, but when it comes to trend lines, it is all about practice! Keep drawing and fine-tuning your accuracy when drawing these trend line because you will be rewarded at the end of the day! You can practice charting using the software I’m using, Chartnexus. (Note: I’m not receiving any commission for introducing this software from Chartnexus, it’s just that it has helped me a lot and I wanted to share with readers who are interested in Technical Analysis and it would help when I teach more about TA in the future.) Some of you may already have access to charts, do give it a try! Some charts are harder to have their trend line drawn and some are easier. Keep trying and eventually move to harder charts to improve your accuracy!


Disclaimer: The above chart is for learning purposes only and not a recommendation to buy or sell. Always conduct due diligence when making a purchase or sale of a stock.

Read More...

Isn’t Investing Just Buying And Selling?

What is investment? Isn’t it just buying and selling an asset? That was what I thought so too when I first began investing. Along the way, I learnt a great deal about what investment is about. It goes beyond just buying and selling. I remember when I first begun investing, the questions that went through my head were questions like “What stocks should I buy?” or “How much does it cost?”. It was simple as that. Perhaps like me, you asked yourself these two questions and found your answers. Subsequently, the ‘Buy’ button was clicked and now you own your very own stock. You were happy, with emphasis on the word ‘were’. Maybe you got lucky, things went your way for awhile, and suddenly it happened. Your stocks went from profit to loss. You’re not alone and it’s not uncommon. When losing, you begin to enter the denial phase and convince yourself that it’ll go back up again. Weeks passed, and you suddenly realise that you’re holding onto a 20% loss. What now? Now, you learn that investing is not just buying and selling.

I’ve been there and done that, but most importantly, I’ve learnt from it and I want to share with you the lessons I’ve learnt so you don’t have to go through it yourself. But just like investing, easy to understand, hard to apply. However, I will still attempt to offer some practical tips that I use in my investment process. “Investment process”? You mean it’s not just buying and selling? Plainly speaking, it is, but there’s more to it. There’s a whole lot of thought process going on before the ‘Buy’ button is clicked.


The Plan

“If you fail to plan, you plan to fail.” – The overused quote indeed. But it’s only because indeed, it works. Here are some of the questions that go through my mind before I click that ‘Buy’ button.

  1. What is this company that I am about to buy involved in? What is its business like and is it profitable? – This is your fundamental analysis phase.
  2. What’s the price now, can it fall further or should I take action now? – This is your technical analysis phase.
  3. What price am I going to buy at, and why? – Based on the above two analyses.
  4. If I buy at $X, when do I take profit and when do I stop my losses? – Contigency plan: Setting profit targets and stop losses.
  5. Why am I buying this stock? – Are you in for the long-run or a quick bite off the market?


If you can answer these questions, you’ve already answered “What”, “When”, “Why” and that should be almost good enough. Feel free to add on more questions to this list. The more you plan, the better prepared you are when emotions try to block out your rational thinking. When you plan well, you’re setting up barricades against emotions that confuse the rational mind after the ‘Buy’ is clicked. It will be useful to know that it has served me very well and I am confident that it will serve you well also.

The Execution

“Plan your trade, trade your plan” – So after you’ve done your planning and have convinced yourselves that this is a good and profitable company, you click the ‘Buy’ button. Congratulations, you’re now an official stockholder! The real challenge of investing starts now – “Trade your plan”. Anyone can plan, but how many can execute without allowing emotions to get in the way? When things go your way, you pat yourself on the back and say to yourself “Good job!”. Perhaps like myself, you were 20% up, and before you know it, it became 20% down and you feel the pinch. Now, what would you do? As good as my plan was, I found out that my emotions blocked out rational thinking and I started creating false beliefs and adopting a whole new plan(that’s based on emotions) to make myself feel better. Check if you’re saying or doing the same things to yourself.

  • From a short-term trade, you turned it into a “long-term investment”. – You’re suddenly trading for a whole new reason which doesn’t make sense.
  • Cut your profits and let your losses grow – Don’t get mixed up! It should be the other way around.
  • “It’s cheaper now, maybe I should buy more?” – It’s not a bad plan, but it only works if you’ve got deep pockets. Do you? And is it deep enough? Remember, you are adding to a losing position, why not add to a winning position?
  • Ignored your stop losses and allowed it to be breached.


If you’re saying or doing these things, sit down and reflect for awhile. Think about what your game plan was and if you are still following your plan. If you’re no longer trading the same plan based on rational thinking, you’re likely to be trading based on emotions. If you allowed yourself to trade on emotions, be prepared to see yourself wiped out of the market. It’s okay to lose a few battles, but win the war. Don’t get wiped out in one bad hand because you allowed your emotions to run wild.


The Review

After all is said and done, it’s always good to look back and ask yourself these two questions:

  1. What went right, and what could I do to make it better?
  2. What went wrong, and what could I have done instead?

Two simple questions, yet packed with so much wisdom and knowledge that will guide you on your next investment.


Hope this helps you realise that there’s more to investment than just buying and selling. When you have a comprehensive plan and discipline to carry out your plan, you immediately become a successful investor just based on that two criteria. Keep working on it with undying persistence and improve the accuracy of your trade plan. All the best in your investments!


Read More...