Things to contemplate when your parents ask you for money

dad and son talking

As your parents grow older, they may require extra money. Medical bills, unexpected repairs, or lifestyle needs may drive them to ask you for financial help.

It could also be due to the instability in financial markets affecting their retirement funds. Or they may be concurrently facing many of these problems. As their beloved child, you want to help – but the question is – is it a good idea to give them money?

Here are some things to contemplate before you decide if you should or should not.

#1: Their reasons for needing more money
an old woman staring in the blank

Image Credits: mtalvernia.sg

When you’re considering giving your parents money, it is essential to understand why they need the money. Understanding the reasons will help you determine the best way to assist them. 

Maybe it could be a loss of income or savings? Or it could be a hike in sudden expenses related to home/car repairs or medical spendings that exceed your parents’ financial means. These situations are relatively straightforward, and it would be appropriate for you to extend a hand.

On the other hand, if they need money because of bad financial choices – gambling or alcoholism – you should rethink the situation. In such circumstances, financial assistance might be enabling your parents, not supporting them.

So what’s the difference?

#2: Contrast between supporting and enabling
a woman holding an elderly's hand

Image Credits: SIM GE

There’s a subtle difference between ​supporting and enabling​ your parents. Supporting someone is providing them access to a need they are not able to meet. While enabling someone is when you are doing something for them that they should be doing on their own (or should not indulge in at all). 

Giving money to your parents to help them pay bills, maintain their home, or go through a minor surgery are examples of supporting them. But if your mum or dad bust the month’s budget on Toto and beer, lending them money may reinforce their negative behaviours and be harmful in the long run.

#3: Is it within your means?
budget-calculation

Image Credits: wallpaperflare.com

Once you have understood the nature of their problem and decided to help, you must evaluate if it’s within your means. Consider these questions now:

  • What are your financial resources?
  • Do you have surplus income or cash at hand?
  • Do you have liquid assets available, or can you sell surplus possessions or investments?
  • Can your brothers and sisters help, and if so, to what degree?

No matter the need, you should not overextend your finances or jeopardise your financial future. Putting yourself deep into debt to support your parents, or putting off a significant life event such as buying a home or having a child, is unwise.

Straining yourself by giving more than you can afford can lead to feelings of bitterness and resentment. Trust us; this will become ​a major source of stress in your life​ as you age and face your own set of money problems later.

#4: Have you talked with your partner?
a couple having a serious conversation

Image Credits: Everypixel

If you are married or in a long-term committed relationship, you must include your partner in your financial decision-making.

It is likely that your spouse doesn’t feel comfortable or render the situation feasible to give your parents money. That’s why having a dialogue is a basic form of respect for each other.

Should your partner be welcoming of the idea, you should establish in clear terms how much money you are giving or lending your parents and what the agreements are. You should also evaluate the likely needs of your partner’s family needing financial aid soon.

Factoring all the above can aid you in making better money calculations.

#5: Do you have a set of terms?
writing something on a notebook

Image Credits: unsplash.com

Before writing your parents a cheque or handing them a stack of cash, you must put forth a definite set of terms. Here are some questions to guide you:

  • Is this sum a gift or a loan?
  • Have you agreed to a one-time loan, or is it an ongoing disbursement?
  • Where will this money be immediately spent?
  • Will they repay you – and if so, when and how?

Having a detailed conversation with your parents is essential. If your parents are okay with it, ask them to put the agreement in writing. This could minimise potential conflicts and finger-pointing as time goes by.

Find other ways to help

Those who do not have the financial means to assist their parents should not worry too much. There may be other ways to offer a hand.

For example, you can hands-on the minor home or automotive repairs or get them their weekly groceries. You can also work with them to find less expensive solutions to the problems that led them to need money in the first place. Or maybe you can offer some advice on planning a budget.

The help your parents need may not always be in the form of cold hard cash. Take some time to contemplate the points mentioned in this article to determine whether it is good to give your parents money. We hope you will settle on a suitable approach to the issue soon!
Read More...

How to steer clear of financial infidelity against your partner

young-couple-sitting-on-their-bed

Money plays a vital role in all relationships. When it comes to finances, secret-keeping, impulsive spending, and poor money management habits often spell trouble for unsuspecting couples.

For those who aren’t exactly sure of what financial infidelity means, it simply refers to “cheating financially”. Here are a few necessary steps you and your partner can take to avoid financial infidelity in your relationship.

#1: Communicate openly and honestly

“Operate in complete transparency and communicate as frequently as possible,” advised Douglas Boneparth, a certified financial planner and president of Bone Fide Wealth in New York City.

While it’s not necessary to bring up finance topics on the first date, it’s important not to shy away from money conversations. This is especially so when your relationship starts moving towards a long-term commitment. 

Sidestepping these sometimes-uncomfortable talks will have a snowball effect that can lead to expensive consequences.

Though it can be difficult initiating the first discussion surrounding finances, take heart that you’re working towards a healthier relationship. These conversations will eventually become routine.

#2: Be transparent about incomes
a couple discussing about money

Image Credits: The Independent

Whether you have a stable salary or your income is dependent on commissions, bonuses, or unpredictable clients, share it upfront. You owe it to your significant other to be transparent about what you bring to the table or can offer in the future.

Being candid about pay will allow you and your partner to budget accordingly. This might mean cutting back on frivolous spending or forgoing impulsive purchases, but your relationship will benefit from financial security.

#3: Settle for joint or separate accounts

Make sure you and your partner are on the same page when it comes to your bank accounts. Are there plans to merge accounts or split your incomes down the middle? Be sure to make a point of discussing your plans and intentions with your significant other.

If you decide to keep everything separate (which is okay), it might be a good idea to keep one account joined for paying shared expenses. This way, you can be sure your budget is being put to good use, and both are paying their fair share.

#4: Play a part in financial responsibilities
a woman looking at her bills

Image Credits: pymnts.com

When both members take part in the household budgeting, the secrets and deception that lead to financial infidelity are less likely to happen.

For example, one of you can take care of the bill payments while the other keeps track of retirement savings. Just be certain that each of you is involved in the process and the loop of your financial status.

Splitting the responsibilities also help prevent placing all the burden on one party, who might feel like the “bad guy” if they have to say no to that staycation or lifestyle purchase in the future.

#5: Never hide your spendings

If one partner is a spendthrift and the other is a saver, it can lead to rifts in your relationship. Be honest with your partner about the desire for big purchases and discuss whether you can afford it.

Likewise, avoid expensive shopping trips without your significant other’s knowledge or agreement. While a little retail therapy may seem like harmless fun, the credit card bills can add up fast, and the deception will often drive a breakdown of trust in the relationship.

Final thoughts
an asian couple arguing

Image Credits: Asia Wedding Network

According to a financial therapist in North Carolina, there are many reasons why financial infidelity happens. It could be due to a financial trauma in the past, a conflicted relationship with money, or insecurity.

Whatever the reason might be, be mindful that small things add up. A lie told today will lead to more lies and secrets going forward. Don’t let money issues be a deal-breaker in your relationship. It’s not worth the heartbreak.

Read More...

How to manage money problems in a marriage?

a wedding couple dancing

Realistically speaking, financial issues are going to present itself at some point and time in a marriage. This is probably true even for the filthy rich. Dealing with them as a couple can either help you grow closer together or further apart.

But think of it as an opportunity to practice money management techniques to build a more robust and financially secure future.

With that said, do you find yourself yelling at each other when financial issues pop up? Are you looking for help?

Here are some ways to truly deal with money problems in a marriage.

#1: Know your partner’s credit score
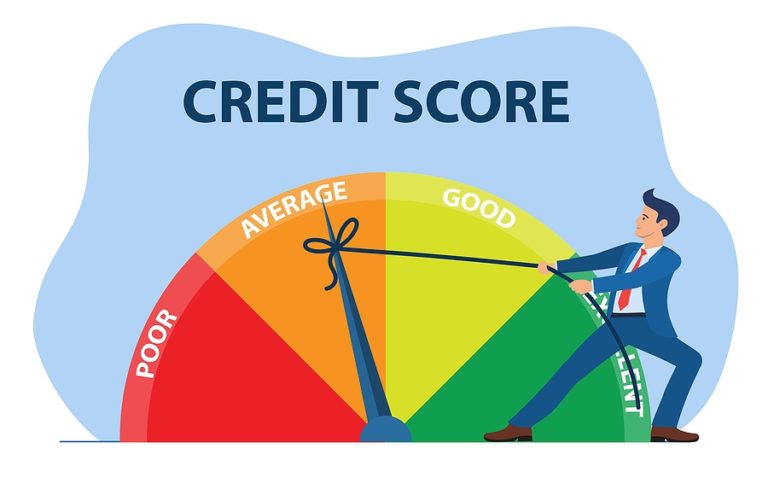
credit score scale

Image Credits: NFCC.org

We have to put this upfront because a couple should lay this foundation ideally before marriage. But even for those who’ve recently tied the knot, it’s not too late. Let Steven Yoda, a partner with a divorce firm, tell you why.

Yoda mentioned that identifying your partner’s credit score can give you insight into their past financial decisions. Money is often a common source of stress in a marriage, so knowing your partner’s money-handling habits can go a long way.

But at this point, do you know what a credit score is?

According to the Credit Bureau Singapore, a credit score is “a number used by lenders as an indicator of how likely an individual is to repay his debts and the probability of going into default. It is an independent assessment of the individual’s risk as a credit applicant.”

Now that you’re aware of the definition, be mindful that your partner’s credit score will not affect your personal credit score. However, it can influence your credit access after marriage because the lender will consider both parties’ credit scores.

In short, a low credit score will lead to higher interest rates and fees on your credit card or loan. But if things happen to go astray…

#2: Don’t play the blame game
a couple arguing

Image Credits: The Telegraph

Even if you feel as though your partner is spending way too much on Starbucks, don’t play the blame game. That’s because there’s no end to it. Both should acknowledge the lack of finances to cover individual or family expenses as the root of the problem.

Just like any other bumps in your marriage, you should approach it as a team. Face the jarring issues together as a unit rather than dissolving into a blame game on who’s spending too much.

#3: Take the lead to communicate
a couple talking over coffee

Image Credits: unsplash.com

When you or your partner spots a potentially money-focused storm on the horizon, schedule a time to sit down and talk. This could range from anything from reduced work hours to the desire of changing jobs.

“To minimise and prevent those issues from becoming bigger problems in your relationship it is important to start with the simple act of having conversations about money,” highlighted Maggie Reyes, a marriage mentor and life coach.

The sooner you prepare yourself for financial issues, the more well-rounded your solution is likely to be too. Panic and stress are never good companions for handling money issues, and to counter it; you want to have a plan in place before it starts spiralling downwards.

#4: Get on the same page
a wedding couple's shoes

Image Credits: unsplash.com

“Most financial issues in marriage come down to one main factor: both partners have different core values about money,” a certified counsellor explained.

First thing’s first, you need to make sure that you and your partner are on the same page about money and its value. Most of us have different understandings of the importance of money, and it takes some effort to understand where the other party is coming from as two halves of a whole.

For instance, you might be okay dealing with a little debt, but your partner may not be comfortable at the idea of it. So, if they start to see the build-up, it can be their source of severe distress.

When both partners aren’t careful in dealing with the disparity in money perspectives, this issue may burst into other areas of the relationship. Whatever those differences in values may be, it’s essential to put one into another’s shoes and find a compromise.

#5: Stop the problem from travelling
a stressed woman drinking wine

Image Credits: unsplash.com

With consistent money problems, it’s easy to resent the other person and their spending habits. Perhaps you fear that they are hiding money from you and siphoning it into a secret account. Or, maybe they’ve got a personal credit card and are overspending without keeping you in the loop. 

You know what? Stop your paranoia in its tracks! The moment financial problems turn into trust issues; it will impact your marriage. Have faith in your partner if you want them to return the favour.

Final thoughts

Money, and lack of it, can make even the strongest couples weaken and crack from stress. If you approach finances with a level head and as a strong, loving duo, you can overcome those issues in time to come.

Nothing is too difficult to solve. Take heart!

Read More...

Singapore’s first luxury confinement centre has opened with packages from S$12,000

Kai Suites

The birth experience is beautiful and miraculous for many mothers, their babies, and families. However, it is also a profoundly exhausting and even medically traumatising journey.

After giving birth, many mothers need extended rest, recovery, and healing to recuperate from the delivery and begin to adjust to a new life together with their newborns.

This is where confinement centres come in handy because they can create a holistic and full-service experience for both the mother and baby.

Have you heard of KAI Singapore? KAI Singapore is Singapore’s first luxury confinement centre that’s specifically designed to heal and help a new family in every way possible.

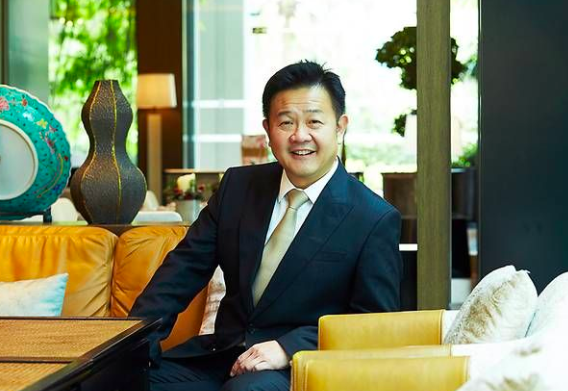
Kevin Kwee, executive director of Laguna National Golf and Country Club, is the co-founder of KAI Singapore. He shared that it is common for new mums in Taiwan, South Korea, and China to recuperate in residential confinement centres in an interview.

the co-founder of Kai Suites

“After 18 months of market research, and finding many such places more clinical than comfortable, I thought I’d improve on the concept by co-founding KAI Singapore. Singapore’s ready for it; I already have local and foreign friends asking to reserve spots,” he added.

The Kai Experience

The centre provides a bespoke embrace to the concept of Japanese hospitality, also known as omotenashi. Kai symbolises restoration and recovery, the two most important factors for a new mother’s health and wellness.

They have a full spectrum of maternity care for families, from prenatal and nutrition advice to postnatal food, and body rejuvenation. The complete guidance is all done in an indulgent environment that rehabilitates every member of the family.

Location

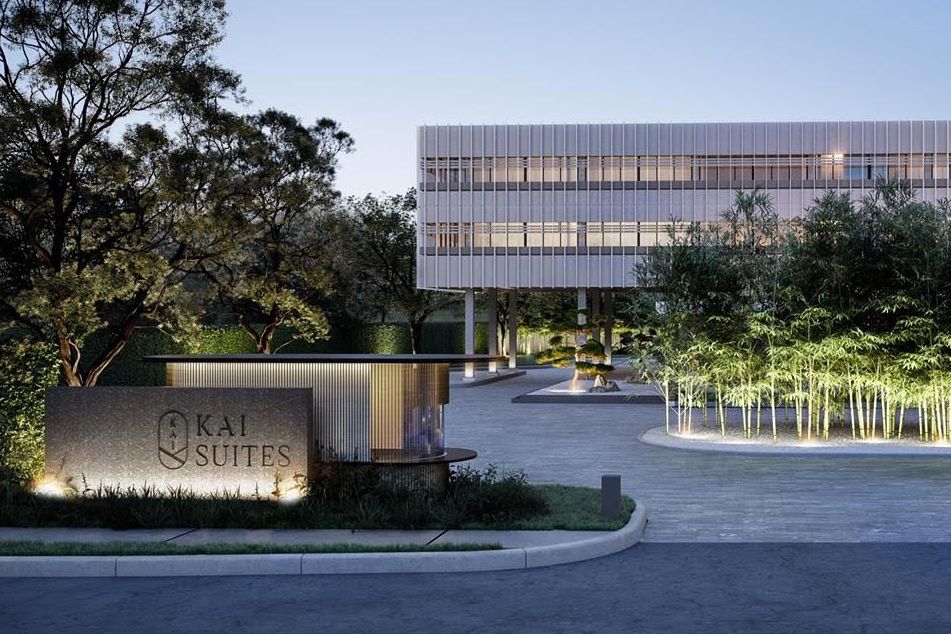
Kai Suites Exterior

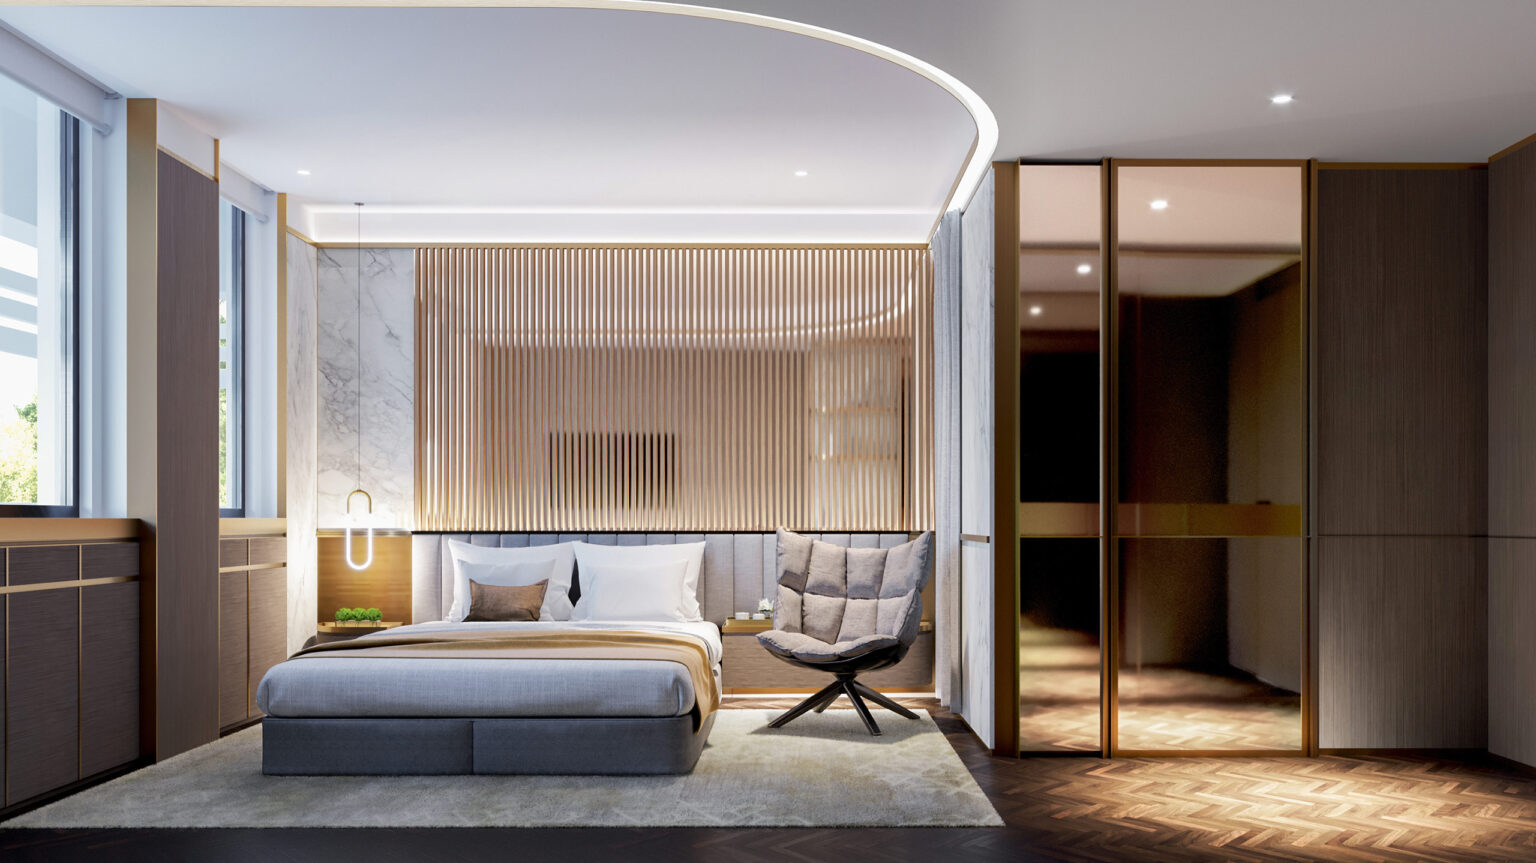
At KAI Singapore, every mother and child receives their suite in a hotel-like facility, one that’s both private and inviting while still being centrally located to town.

Have we not mentioned that they are located at 26 Dunearn Road? You will find yourself a less than 10-minute drive to Orchard from the confinement centre.

Not to mention the list of hospitals within a 3km radius:

  • 1.8km from Thomson Medical (3-minute drive)
  • 2km from Novena Mount Elizabeth Hospital (4-minute drive)
  • 2km from Orchard Mount Elizabeth Hospital (6-minute drive)
  • 4.1km Mount Alvernia Hospital (7-minute drive)
  • 2.8km from Gleneagles Hospital (8-minute drive)

Facilities & Services

Private mothers’ lounge

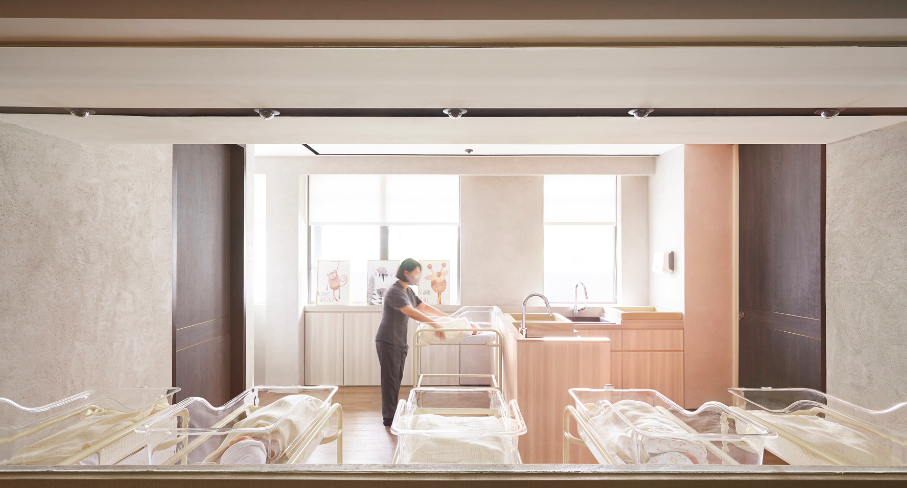
nursery offering camera surveillance

Mothers will be thrilled to know that there’s a private mothers’ lounge that allows mothers to rest and socialise while their babies are asleep in a nursery offering camera surveillance. Stay connected to your child at all times by viewing them through a mobile app.

Integrated wellness haven

Kai Spa

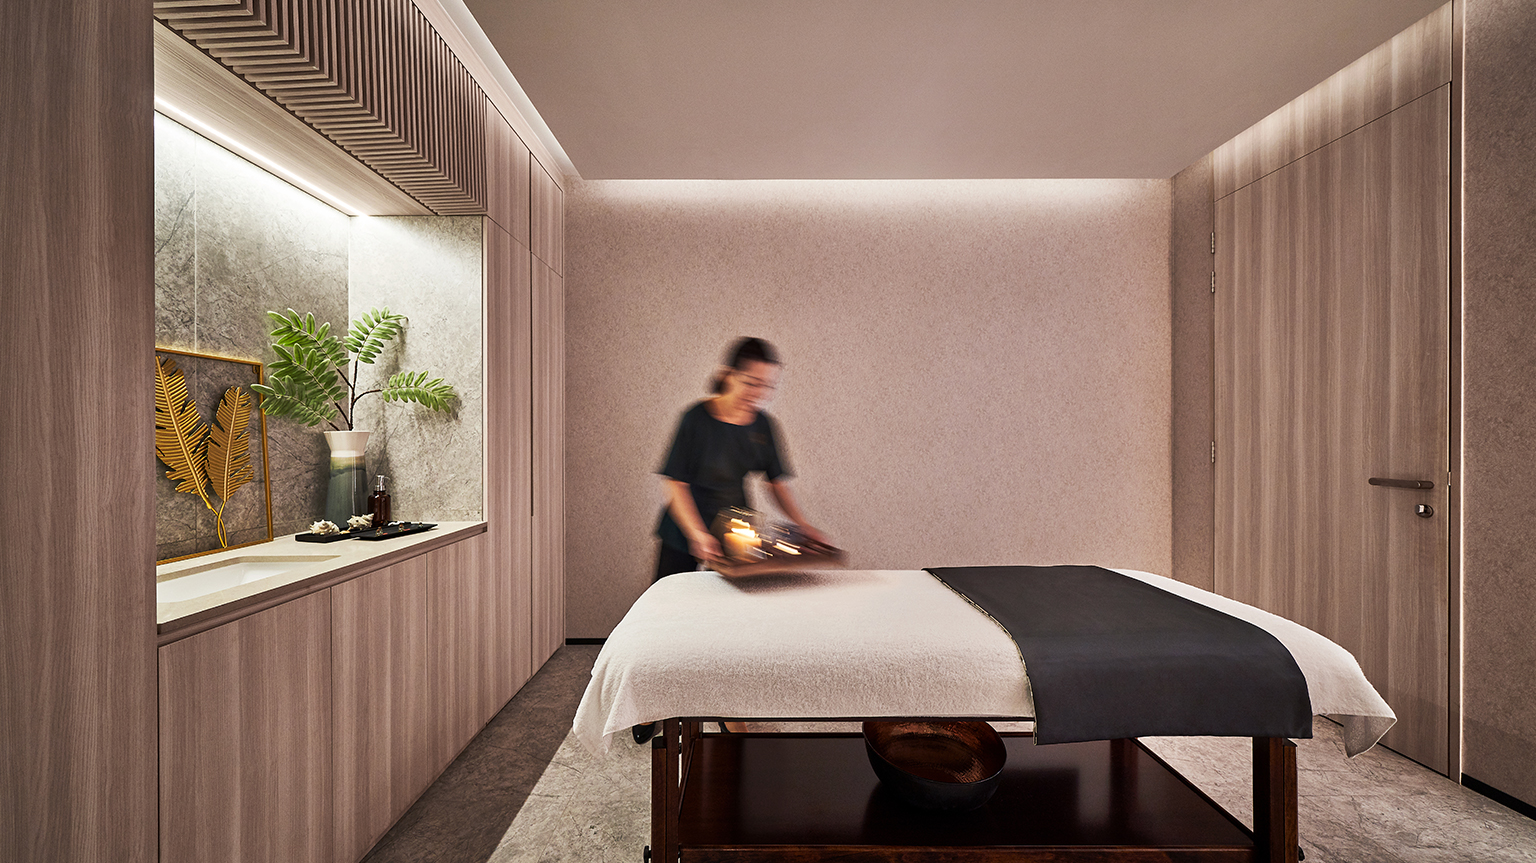
KAI Singapore is the first in Singapore to take the confinement experience and add luxury and elegance to it. You get to access a spa, salon, and aesthetics clinic during your stay!

Take advantage of the complimentary daily warm herbal baths and weekly breast massages to promote postnatal healing.

Their Kai Spa also has a range of facial treatments and therapy sessions for you to be pampered:

  • Age repair facial or essential rose facial
  • Prenatal massage using both Malay and Swedish techniques
  • Breast lactation massage to remove soreness and boost milk production
  • Head & shoulder massage which uses essential oils to soothe the tension away
  • Jamu massage & bengkung wrap to restore the abdomen to its original state

There’s also a relaxation lounge for mummies to get their pretty manicures and pedicures done!

24-hour professional care

Kai Suites reception area

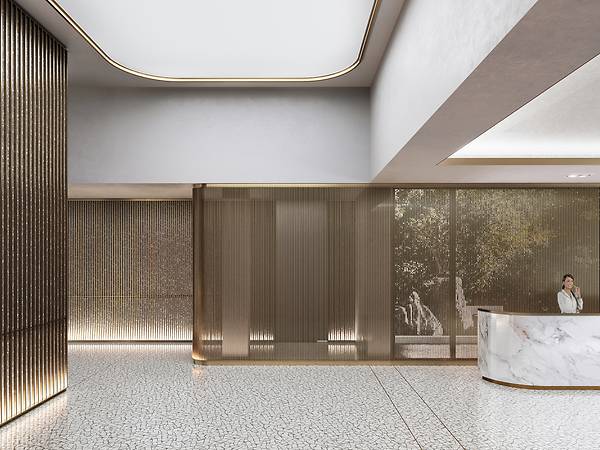
As valued guests of KAI Singapore, you will be taken care of by a 24-hour expert care team. These are highly trained and supervised medical staff so you will be assured the best attention. There is also in-room dining, housekeeping, security, and concierge services.

Nourishing foods crafted by chefs & nutritionists

Kai Cuisine

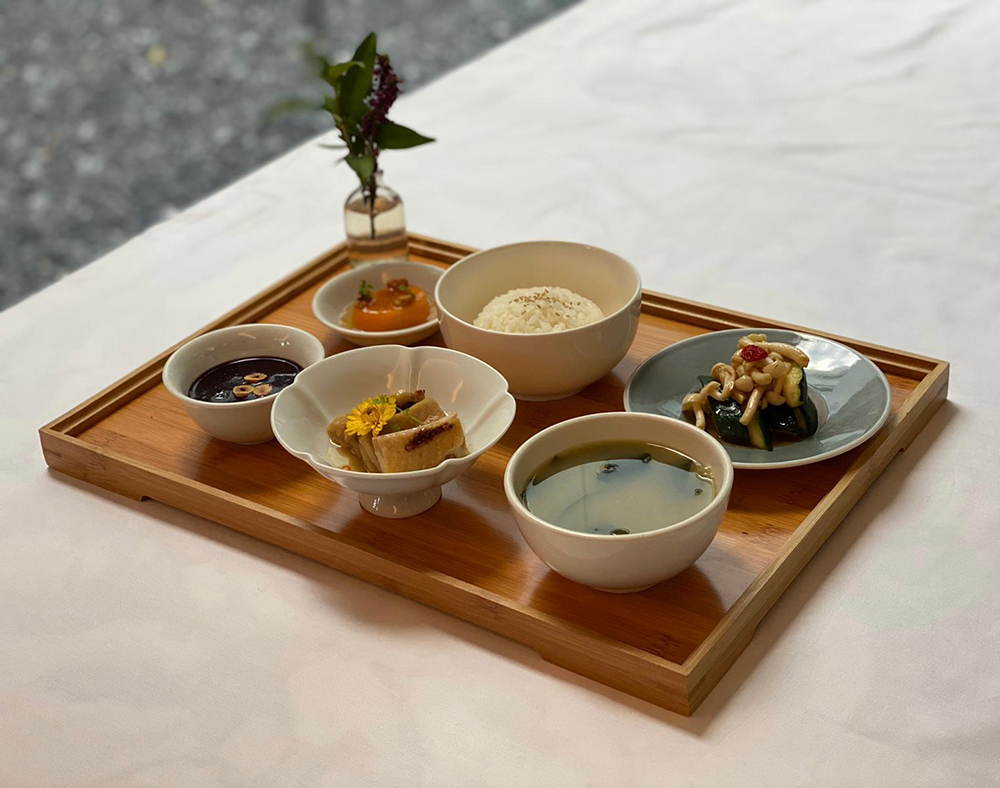
Your daily meals are catered by a state of the art kitchen that uses fresh, local ingredients and traditional cooking. The menu tailors to the individual recovery needs and requirements of the mother.

Using Traditional Chinese Medicine (TCM)  principles of 一休二排三调四健养 (the process of healing, detoxification, restoration and nourishment), you can expect pure, natural, and wholesome foods with no added MSG or artificial additives.

Kai Cuisine is also all about using the best, natural herbs such as black dates, and sulphur-free ‘dang gui’ or angelica root. They even make their sauces, seasonings, and condiments from scratch in controlled batches in-house.

Every top-notch service is designed with Asian cultural values and heritage in mind, treating childbirth as a richly time-honoured tradition that provides rest and critical bonding time between mother and baby.

Package Prices

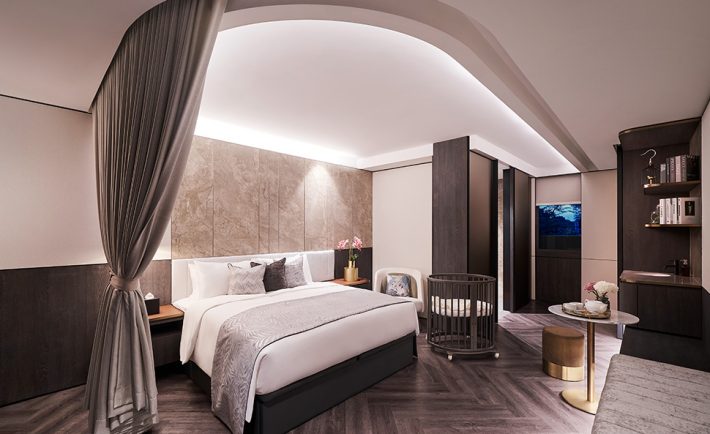
One of the Kai Suites

The standard package at KAI Singapore begins at S$12,000.

It comes with an extensive three-month prenatal program that teaches valuable mothering skills and wellness techniques, a seven-day stay after the baby is born, and a three-month postpartum program that helps mothers adjust to life with their new baby.

Guests can alter their stay-in periods and use the KAI Singapore’ intensive recuperation program for as long as their budget allows.

Final Thoughts

KAI Singapore is an innovation in luxury maternity management that provides top-tier services that address both mother and baby care components. There’s no better place to do it than at KAI Singapore for mothers who are preparing to welcome their new infant.

For more information, please head to kaisuites.com.sg.

Read More...

Financial Responsibilities Of Newly Married Couples

Managing your finances together is one of the most important roles you partake on in a marriage.

Differing views and attitudes towards money can pose issues to a relationship. For instance, you may seem frugal to others and stingy to her. If you both live beyond your means and spend lavishly on each other, you might find yourselves trapped in debt. There is time to change. Planning ahead as a team can help you build a strong foundation for your marriage.

1. GETTING TO KNOW EACH OTHER

Get to know each other’s financial beliefs and spending habits. Understand where your partner is coming from and adapt if necessary. If your partner is a spender, agree on establishing some limits. If your partner is prudent, agree on the things you would like to prioritize. Make your expectations clear to arrive on the same page.

“The handling of finances is one of the major emotional battlegrounds of any marriage. Lack of finances is seldom the issue. The root of the problem seems to be an unrealistic and immature view of money.” – David Augsburger, The Meaning of Money in Marriage

2. DELEGATING FINANCIAL DUTIES

Assess the differences in your income and money management strengths to determine how to divide the financial duties. Delegate the person who is financially savvier to take the role of managing your family’s investment options. While, the person who is better at budgeting can take charge of managing the household bills. Take advantage of each other’s strengths and fill the gaps in between.

3. PROVIDING SOLELY FOR YOUR FAMILY

For families with a sole breadwinner, it is practical to maintain an adequate emergency fund to withstand unexpected financial woes. Please consider the number of dependents when finalizing the amount of money to be set aside.

Single income couples should consider helping each other in terms of their CPF responsibilities. You can top up your spouse’s CPF account, especially if he or she has low CPF balances. You can transfer your CPF Ordinary Account savings after setting aside the Basic Retirement Sum in your own CPF account.

4. SHARING BANK ACCOUNTS

There is no one size fits all! Your household arrangement depends on your marital assets, income levels, and financial commitments. Think about which expenses you want to keep separate and which you want to share. You open a joint account for their household bills. Set aside a specific amount monthly to grow your joint account together. Meanwhile, you can keep your own individual accounts to fund your own spending.

5. AVOIDING FINANCIAL INFIDELITY

Financial infidelity refers to hiding financial information behind your partner’s back. Failing to mention a significant expenditure to your spouse may cause problems in the long run. Top money lies include under-declaring one’s income or hiding one’s debts. Such dishonesty can diminish the level of trust between a couple.

6. WORKING ON SAME FINANCIAL GOALS

Find a way to work on shared financial goals. Agree on the amount of personal contributions depending on your income.  Some of the common themes that most financial goals share are having a budget, living frugally, getting out of debt, and having a good credit score. Do not forget to save for your emergency fund and retirement plans.

Image credits: pixabay.com

You are in this (wild ride) together!

Sources: 1 & 2

Read More...