
Reduce Your Debts Dramatically With The Debt Diet

Ellie Kay once said: “Getting out of debt is like going on a diet — it may sound simple, but it sure isn’t easy.”

Debt takes a toll on your relationships, your family, and your future. Just as being obese leads to physical and emotional challenges, debt has its own negative consequences too.

Inspired by Oprah Winfrey’s Debt Diet, three financial experts namely: David Bach, Jean Chatzky, and Glinda Bridgforth were sent to help several families to solve their monetary dilemmas. They shared debt elimination tips and suggested practical ways for people to increase their income and reduce their spending.

Before anything else, here are the “signs” that you need to go to participate in the Debt Diet:

1. You depend on your credit card to pay for your living expenses.

2. You rely on overtime pay to make monthly expenses meet.

3. You utilize your credit card/s to pay for items that you used to pay for in cash (e.g., groceries or clothing).

4. You use your emergency savings to pay for your bills.

5. You borrow money from your family and friends to pay your bills.

6. You delay paying one bill in order to pay an overdue one.

7. You utilize credit card A to pay bills for credit card B.

8. You can only pay the minimum amount due on your accounts.

If most of the “signs” point to YES, you may employ the following steps of the Debt Diet:

1. Determine how much debt you have and what it is costing you.

2. Monitor your spending and look for ways to make extra money (e.g., by giving up certain expenses).

3. By understanding how credit cards work, use your credit card/s to your advantage.

4. Stop spending on unnecessary things.

5. Make a strategic monthly spending plan.

6. Determine ways to increase your income and identify the steps you need to achieve it.

7. Prioritize your debts.

8. Do your best to know yourself and your spending behaviors.
Image Credits: pixabay.com (License: CC0 Public Domain)
Image Credits: pixabay.com (License: CC0 Public Domain)
Sources: 1 & 2

Read More...

Work Smart: 4 Passive Income Strategies to Try

Passive Income

How many hours do you work in a day? Eight hours? Nine hours? More than that? We Singaporeans are normally tied to our jobs in the hopes we can earn some good income. But do you know there’s a way to work smart—that is, earn additional income with little to no effort? I am talking about passive income.

What is passive income?

There are two kinds of income: active and passive. Active income is the one you earn if you use resources such as time, talent, and even money. Your wages are a form of active income, and so are the commissions, bonuses, and allowances, to name a few.

On the other hand, passive income is how many get richer since it doesn’t require the same amount of effort and resources from you. In fact, many require only a minimum investment—that’s it! You just wait for your money to grow.

But where exactly can you get passive income?

1. Savings Account

Remember when finance experts tell you that it’s better to place your money in the bank than under your bed or anywhere else in the home? Well, here’s the reason why: it’s the quickest and easiest way to start earning passively. A typical savings account is interest bearing, the rate of which can differ among banks, so do your research well. But the more you put money in there, the bigger the interest income is.

Bank savings are also safe, investment wise, especially since these institutions are regulated and protected by insurance. However, it also offers the lowest return, which may not be enough to beat inflation. Needless to say, it’s a great start.

2. Real Estate

As a small country, Singapore has a very limited but highly valuable resource: land. So when something is scarce but the demand is high, you have a pretty good leverage. Properties can be either sold or rented.

Currently, the real estate market in the country is grim, but it’s also cyclical. In fact, you can use this to your advantage by buying a property when it’s still cheap. But remember, real estate is the hardest investment to liquidate. It can take months or even years before properties turn into cash unlike the other passive income options.

Meanwhile, if you don’t want to own a property, you can still invest through real estate investment trusts (REIT).

3. Stocks

Fancy owning some of the biggest companies in Singapore? Try your hand at investing in the stock market. Stocks come in two forms: common and preferred. Some of the stocks also give you dividends, which means you earn a profit from a sale or buy, plus get income from simply owning the stock.

So far, more than 600 companies are part of the Singapore Stock Exchange (SGX). As a start, place your money on blue chips, of which there are 30 of them. They are more expensive than the other stocks, but you’re assured of the company’s stability and reputation.

4. Mutual Funds

What if you don’t like to work personally with stock? Or perhaps you want to access other forms of investment but don’t know how? Then perhaps mutual fund is for you.

It works like a financial pool: people contribute to a certain fund, and an experienced fund manager with deep knowledge and understanding of markets determine where the money is going to be invested. Depending on the fund you’ve chosen, the manager can put it in many investment choices including real estate and bonds.

Hold Up!

Passive income is great for earning a side income, but it wouldn’t be if you allowed your other financial choices to ruin its good impact on you. A perfectly good example is unwise spending complemented by poor credit card features. A simple but powerful way to also protect passive income is to select the best credit card deals in Singapore.

(This article is brought to you by SingSaver.com.sg)

Read More...

Do You Really Have What It Takes To Be A Trader?

Do you want to trade as a career but, you do not know where to start? How about you get to know yourself first?

Begin the journey by examining your relationship with money and life. Do you view life as a daily struggle or as an endless opportunity? Have you lost money recently through your daily activities and are you hoping that the financial markets will treat you better?

Wherever you are right now and whatever your belief system is, your personality will influence your perspective on your profits and losses. This is why it is important to include self-worth into the mix. Analyze your strengths and weaknesses and examine whether you have what it takes.

Marc Pearlman shared his observations based on his experiences as a professional trader and money manager. According to him, here are the tangible qualities that aid in success at day trading:

1. POURING HARD WORK

It is no surprise that hard work tops the list. Since trading is a skill, it needs to be developed through time. A lot of people view trading as a hobby or as a substitute to gambling however, this should not be the case. People only end up bad when they treat financial markets as casinos and not as businesses.

2. PRACTICING DISCIPLINE

Marc compared trading to going to the gym. For example, people may have been frequenting the gym and yet have no noticeable changes in a year. He says it is be due to the lack of discipline and goal-setting, which I agree on. Trading is no different. You must have discipline and concise strategy to reach your goal!

3. KNOWLEDGE IN PROBABILITIES

Making money through trading does not mean that you have to be perfect all the time by making right calculations. Instead, the key is to lose as little as possible when your call is wrong and gain as much as possible when your call is right.

4. LETTING GO OF THE DESIRE TO BE ALWAYS RIGHT

If you would rather be right than make money then, trading may not be for you. In trading, you cannot be right all the time! Furthermore, some may even be wrong more than they are right.

Image Credits: pixabay.com (License: CC0 Public Domain)
Image Credits: pixabay.com (License: CC0 Public Domain)
To accompany these desirable qualities, here is a website that I found that can help you test your skills in Mathematics, Logical Sequence, and more. You may adjust the difficulty by choosing either Easy, Medium, or Hard.

Read More...

Must Read: Simple Money Hacks To Improve Your Financial Life Now

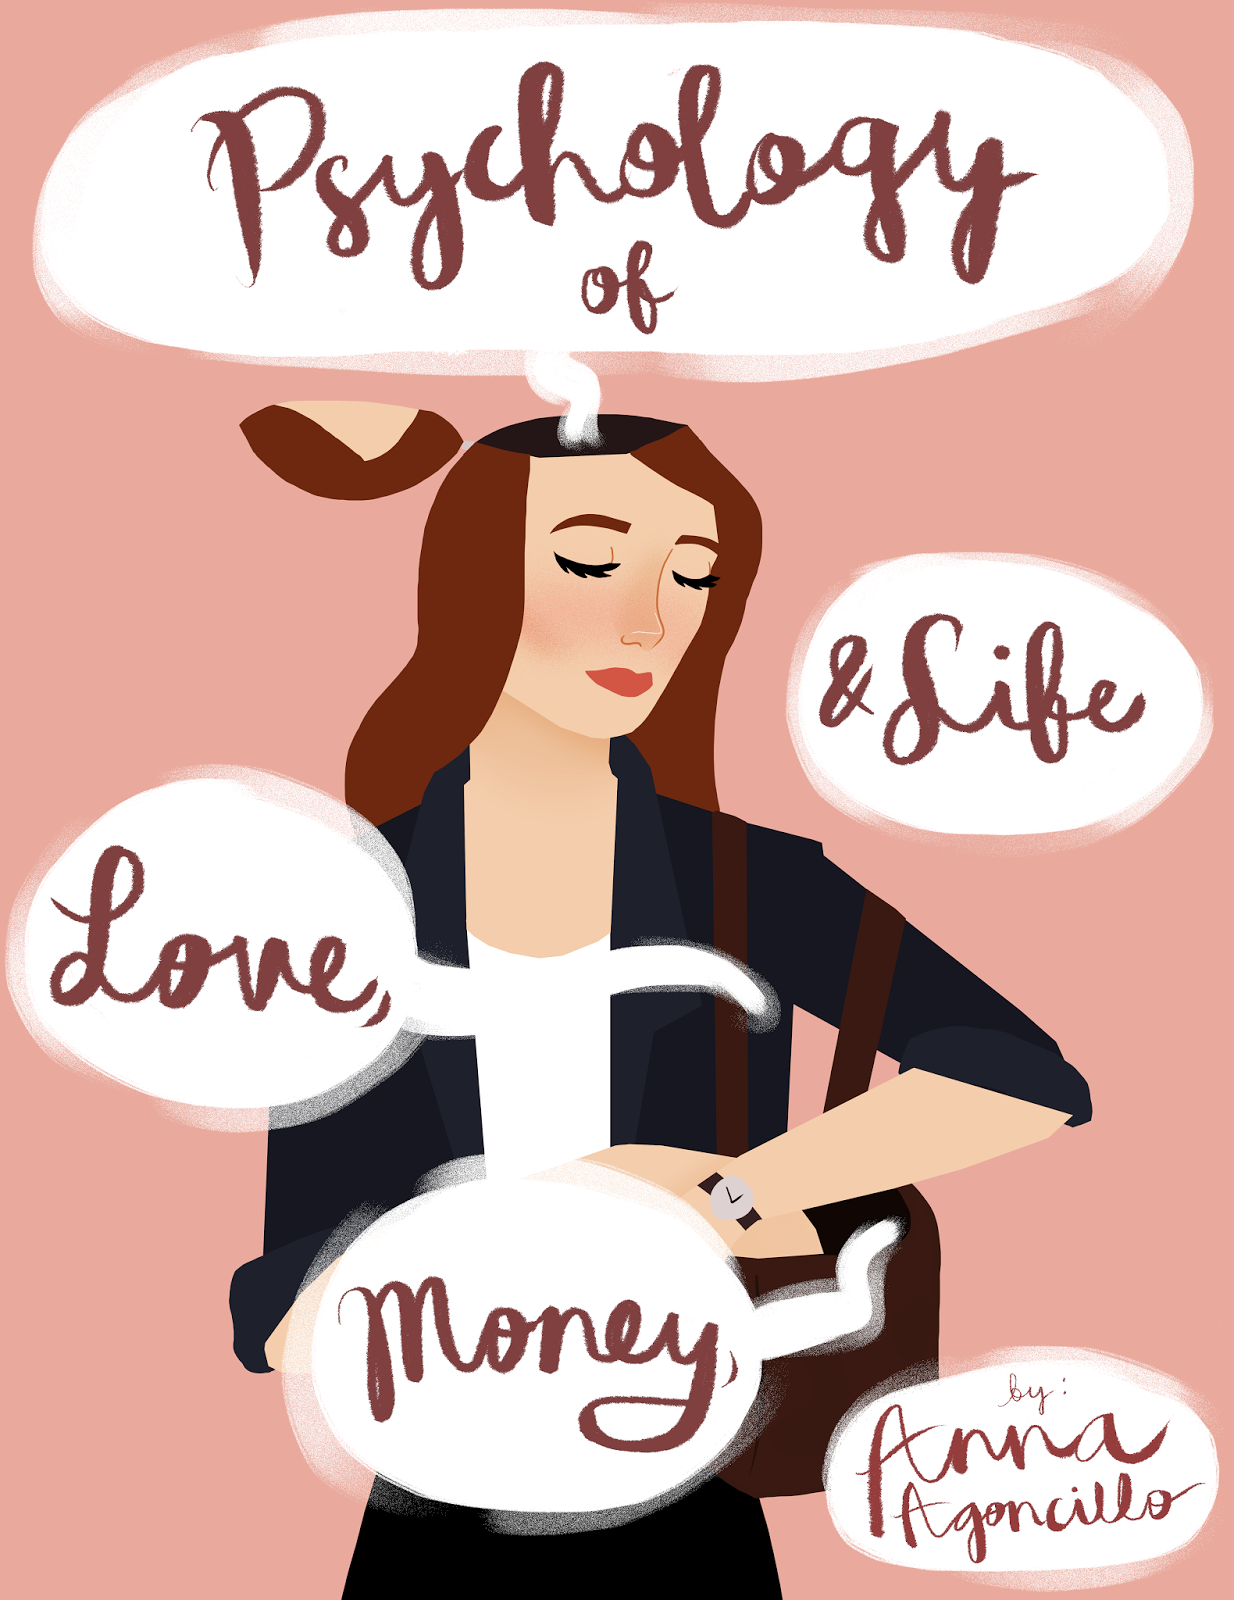
You deserve to achieve understanding, awareness, and especially control over your life. Everyone does. And, “Psychology Of Love, Money, & Life” book might just be the answer!

Money is one of the book’s three sections. Adding the Psychological factor, you will be able to realize that money has effects on your well-being and that you can control its effects. You hold your financial present and future!

So, take a peek inside some of the valuable tips you can get from the #PLMLBook…

1. GAIN PLEASURE FROM MONEY THROUGH ANTICIPATION

If you want to gain positive feelings toward your spending then, ensure that you always have something to look forward to. Let us say you get a raise, treat yourself by buying the designer bag you have been wanting for months. The anticipation of purchase, no matter how small the item is, can increase pleasure enormously.

2. SAVE UP FOR TRAVEL FUND

If you are in a Long Distance Relationship, it can be very expensive. Which is why it is essential to follow a strict budget to save up for your travels. Be responsible enough to spend your money only to what is necessary.

3. SHALL YOU BUY IT OR NOT? STOP THINKING! TAKE THE SWIFT TEST INSTEAD.

When you are thinking twice on purchasing an item especially an article of clothing, ask yourself if you are willing to try it on the dressing room swiftly at that particular moment. If there is no sense of immediate excitement, do not bother to buy it.

4. ONE SIZE MAY NOT FIT ALL

Everybody’s financial situation is unique to the person so, be wary of the “one-size-fits-all” investment strategies from media’s financial gurus. Many factors such as your consumer personality, financial goals, age, etc. should be considered. This is why it is best to listen to your personal financial adviser instead.

5. AVOID THE STATUS QUO BIAS

As I was looking for a new laptop online, my choice leaned towards the brand that I’ve been using for 4 years – the MacBook. Although its competitor had touch screen, 360 bendable monitor, and it’s running on the new Windows software that enables you to download countless of Apps. Certainly, for functionality, the latter was the best choice but I still preferred Macintosh.

This cognitive bias is called the status quo bias. It occurs when you are more likely to prefer the product that you know more of even if there are better options available. Changing your buying habits to avoid this cognitive bias start with the awareness!

Image Credits: misspsychobabble.blogspot.com

Image Credits: misspsychobabble.blogspot.com

Psychology of Love, Money, & Life is now available on Google Play Books, Kobo, Amazon (Kindle), Apple IBooks, and M1 Learning Centre. Find the platform and price that suits you best!

This is written by Anna Agoncillo. She graduated under Cardiff Metropolitan University (UK) with Honors. Combining her passion for psychology and writing, she started a successful blog called “Miss Psychobabble” and has contributed to other platforms including Bored Panda, Psychology Matters Asia, Thought Catalog, Money Digest, and so much more.

Read More...

4 Tips You Need To Know Before Buying A Home As A Single Singaporean

According to the latest Population Trends report, single-hood rates are highest among lower-educated Singaporean men in their 30s and 40s and among higher educated women. It is clearly observable that the number of unmarried Singaporeans have been growing over the years but that does not stop one to contemplate about purchasing his or her own flat.

With the hefty housing prices in the market today, can an individual with an average income really afford a huge investment single-handedly?

To tell you honestly, the answer is YES!

It is possible, but you have to consider these few things:

1. KNOW ABOUT THE AVAILABLE SCHEME AND GRANT

In 2013, the government introduced a scheme that allows first-timer singles aged 35 and above earning up to S$5,000 a month to purchase a 2-room flats in “non-mature” estates. At that year, HDB launched 3,861 flats for sale in Sengkang, Bukit Merah, and Yishun under the Build-To-Order (BTO) exercise.

This relatively new scheme is called Single Singaporean Citizen (SSC). As you are aware of, before SSC, singles could only buy either private properties or resale HDB flats which can be costly! Thus, this will give a great opportunity for all the singles out there that are planning to become home owners despite of their average incomes.

Say you are an unwed Singaporean who just turned 35 a few months ago and you draw an average of S$3,000 a month, you can be entitled to receive the Special CPF Housing Grant (SHG) worth S$10,000. However, the eligibility of SHG is only given to first-timer citizen who is applying for a 2-room flat in non-mature estates. Furthermore, his or her average gross monthly income must not exceed S$3,250.

By knowing the available scheme and grant, one can safely conclude that owning a 2-room flat in Singapore is possible without the need to fork out loads of cash upfront.

2. ANALYZE YOUR BUDGET

Since purchasing a house is probably the biggest financial commitment you have at this point, it must be planned carefully. Before you start looking for a flat in the non-mature estates, know what you can afford as well as what you need to pay for first. Even if you are purchasing a new private property, you will need to reserve extra money to cover repair, taxes, and maintenance. Affordability is certainly a huge issue!

3. PROTECT WHAT YOU OWN

There is a huge sense of comfort and independence in owning your own home wherein you make your own decisions as days go by. Along with that comes the responsibility to take care of yourself. It is important that you have sufficient insurance to cover your health and your life.

Image Credits: pixabay.com (License: CC0 Public Domain)
Image Credits: pixabay.com (License: CC0 Public Domain)
4. CONSULT THE PROFESSIONALS

As I said before, buying a home is a huge commitment to make. This is why you must take your time and do your research with the available resources you have. Aside from this, it is always a good idea to talk to real estate agents or to consult a financial adviser beforehand.

Sources: 1, 2, & 3

Read More...