Affordable And Romantic Honeymoon Destinations In Asia

Whether you prefer a peaceful time at the beach or a lively day packed with cultural adventures, you will not be disappointed with any of these top-rated and incredibly affordable honeymoon destinations in Asia:

LAID-BACK LAOS

For couples who are looking forward to enjoy a laid-back honeymoon filled with rich cultural experience, you may consider going to the spectacular city of Luang Prabang in Laos. The entirety of this beautiful city is a UNESCO World Heritage site. Relaxed is one word that perfectly encapsulates its inhabitants. People in this city are not rushing to catch up with the rest of the world. They simply enjoy the humble things in life. It is immensely different from the fast-paced and relatively demanding lifestyle we have in Singapore!

Honeymooners can enjoy the glorious waterfalls, riverside ambience, amazing river cruises, untouched countryside, and sacred Buddhist temples. It is recommended to visit this destination from March to September.


Cheapest Flights For Two Adults: S$688 thru Air Asia

SPICY SRI LANKA

Sri Lanka is both a budget-friendly and extraordinary way to kick start your new life together. It has been considered as one of the top-rated honeymoon destinations in Asia due to its interesting culture, delectable (and spicy) food, as well as its friendly locals. Its natural resources boast with endless beaches and breathtaking mountains. Paradise is an understatement! Just take a look at what this country’s landscapes can offer:

For optimum weather conditions, it is best to visit the country from May to September at the east coast and from December to March at its west and south coasts.

Cheapest Flights For Two Adults: S$556 thru Air Asia

MAGNIFICENT MALDIVES

Looking for our very own “Caribbean” in Asia? Look no further as Maldives will delight you with its pristine beaches and world-class scuba diving services.

The floating bungalows and resorts set on beautiful blue waters will make you and your better half want to stay there forever. To turn up the romance, you must visit from April to November when rain showers are expected.


Cheapest Airfare For Two Adults: S$374 thru Tiger Airways

VIBRANT VIETNAM

Probably the cheapest destination in this list is Vietnam. In less than 3 hours, you will arrive at this Southeast Asian country that is filled with bustling cities, tranquil beaches, and stunning rivers. Newlyweds can savor the delicious local food, enjoy the cruise in Mekong Delta, and appreciate a biking trip together. Book a flight between September to December for the best weather conditions.
Image Credits: pixabay.com

Image Credits: pixabay.com

Cheapest Airfare For Two Adults: S$208 thru Tiger Airways

Note: All the airfares were based on the prices of the two-way tickets from August 29-31, 2016. Information were taken from cheapflights.com.sg.
Sources:  1, 2, & 3

Read More...

Money-Saving Parenting Hacks That Work

MAKING YOUR OWN SWIVEL ROCKER

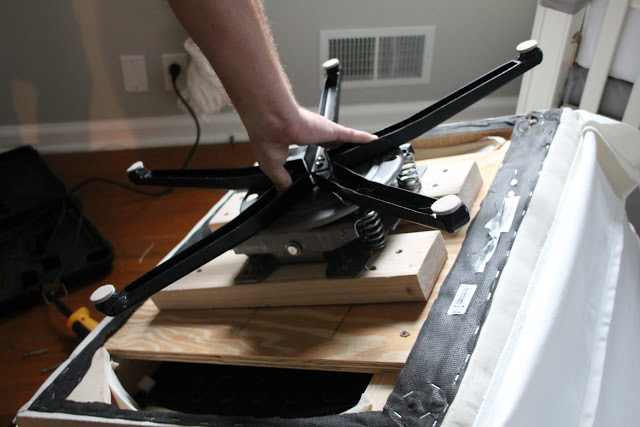
Looking for a great way to save on your nursery swivel rocker? Instead of looking at the baby aisle, try looking for the office aisle. Consider purchasing a pre-owned armchair online and adding your own rocking base to it. You will not only save a lot of cash but you can also have an unforgettable DIY experience with your spouse.

Simply follow the instructions – here.

ORDERING GROCERIES VIRTUALLY

Image Credits: pixabay.com

Image Credits: pixabay.com

One marketing strategy that groceries employ is targeting the children’s interest because they play an influence on what goes inside the carts. Supermarkets purposely place cereals, toys, and sugary treats at a kid-friendly level. If you cannot leave the kiddos alone, opt for shopping online.

A revolutionary feature of most “big name” grocery chains in Singapore is that they offer access to online grocery shopping. This can help you to save money by religiously sticking to your list (or budget), by avoiding the transportation costs, and by preventing the impulsive buying power of your children.

For everyday shopping, I recommend fairprice.com.sg as they have regular deals and discounts. As for affordable organic produce, you can visit bestorganicfood.sg.

STOCKING UP FOR KIDDIE PARTIES

Image Credits: pixabay.com

Image Credits: pixabay.com

Children’s toys, clothes, and other fun items go on sale from June to August due to the Great Singapore Sale. Take advantage of this annual event by stocking up on a variety of inexpensive gifts that you can give on kiddie parties or even Christmas. Set a limit for every individual to avoid going beyond your budget.

KEEPING A PIGGY BANK

Image Credits: pixabay.com

Image Credits: pixabay.com

Be the good example to your children by putting some of your loose change into a money jar. Since most young children want to be like their parents, seeing you do it will provide them with encouragement to save.

After serving as an example for a month, provide your child with his or her very own piggy bank. Have your child draw the picture of the specific toy on the side of the piggy bank. Through this, they will be motivated to save in order to get what he or she wants.

USING FREE RESOURCES

Image Credits: pixabay.com

Image Credits: pixabay.com

Your nearby public library can serve as your savior during those school-free days. Not only can you borrow children’s books but you can also rent CDs/DVDs for the whole family – at no cost. Aside from these, the public libraries also offer a wide array of free events that your family can join. Visit nlb.gov.sg to stay updated with the National Library Board’s events calendar.

BREASTFEEDING YOUR BABY

Image Credits: pixabay.com

Image Credits: pixabay.com

One of the empowering things that only women can do is to breastfeed their baby. As much as you can, opt for breastfeeding because it will not only be healthy but also be able to save you as low as S$1,500 per year.

If you want to save even more on breast pump, borrow from your family or friends but make sure to change the plastic attachments. You can buy those for far less than a brand new pump.

Sources: 1 & 2

Read More...

Financial Intimacy: How To Mix Love With Money

Relationships and investing are both complicated and mixing the two can either be a home run or a recipe for disaster. As Michelle Singletary, author of Your Money and Your Man: How You and Prince Charming Can Spend Well and Live Rich, once said:

“Couples want to know should they have his, hers, or ours, or all of the above. They’re not sure how to manage it. And that’s where a lot of the arguments come in, especially if there is uneven income earning between the two.”

Sometimes an individual may feel like a child receiving an allowance from his or her spouse, but it turns out that the person simply cannot handle money well. The situation can be resolved if both parties begin to be accountable for their money. Aside from this, here are some tips to boost your financial intimacy:

1. INTERVIEW EACH OTHER

Upon entering a serious relationship, you must discuss about your perspectives on money, spending habits, and sharing costs. This will make talks about financial issues easier as time goes by – especially if you are planning to spend the rest of your lives together.

For couples who are about to get married, you must touch on the long-term subjects such as how to enhance your credit scores, how to address retirement, how lavish your wedding ceremony will be, and how do you plan to manage your money.

2. BE COMPLETELY HONEST

Regardless of whether you have joint or separate bank accounts, you must always be honest to your partner about your current financial situation and your ideal financial situation. Tell him or her about your purchases, debts, income, assets and other things that are in your account/s right now. As for your ideal financial situation, relay your future plans such as having annual overseas trips.

Financial intimacy entails full disclosure about your finances including knowing what documents are signed and where the records are kept.

3. SEEK OUTSIDE HELP

When it comes to marriage, you become half of a legal and financial partnership once you say “I do!” This is why Premarital Counseling incorporating a strong financial component is a great help. If you are deciding to purchase a condo or an HDB through your CPF accounts, the financial professional will guide you to good credit score and substantial amount of savings. An accountant during the first year of marriage is also helpful as your taxes can get complicated during the transition from single to married.

Image Credits: pixabay.com (CC0 Public Domain)

Image Credits: pixabay.com (CC0 Public Domain)

Sources: 1,2, & 3

Read More...

Sensible Steps To Prepare For Your Child’s Tertiary Education

1. ESTIMATE YOUR TOTAL COSTS
The education system in Singapore follows high standards of quality and fosters excellence in its students. Offering various choices for pre-school, primary, secondary and tertiary education, it is worth taking a careful consideration at Singapore’s local schools. Not only do they provide a more affordable rate but they also set the bar for all the universities across the nation.
Estimate how much you have to pay for the school fees, living expenses, and other miscellaneous. Do not forget to factor in the inflation rate. For example: If the school fee at NTU or NUS is about S$27,560 last 2010, it will increase to up to S$38,000 by 2030 due to the annual inflation rate of 1.6%. How do you plan to save up for that?
2. LOWER THE COSTS
If the total spending capacity of your household is tight, consider reducing your child’s university expenses. Take up scholarships and other financial aids available at the school. Also, it is important for your child to figure out what he or she really desires to become before venturing off to a course and later shifting to another. An education fund for four years is definitely cheaper than a fund for six.
3. CHOOSE THE FINANCIAL PACKAGE WISELY
There are tons of financial packages tailored to help you save for your child’s tertiary education. Before deciding to commit to one, you must…(a) set your goals first, (b) assess if the package meets your needs, (c) determine how much you can afford, (d) and know how much risk you are willing to take.
After clearing those things up, you must choose between:
a. LIFE INSURANCE PLANS
If you are going to rely on whole life policies, note that only a part of the policy value is guaranteed. The rest of the non-guaranteed value relies on the performance of the insurer’s participating fund. While investment-linked policies do not guarantee the fund values. Said values rely on the investment performance of underlying funds.
b. UNIT TRUSTS AND EXCHANGE TRADED FUNDS (ETF)
The underlying assets that your unit trust or ETF is invested in determines the value of your investment. Given that your investment path is fixed until your child enters tertiary education, you must select a unit trust or ETF that accommodates your timeline and investment objective.
c. BONDS
Bonds, usually regarded as less risky than equities, are primarily fixed income-securities. You shall receive the bond face amount on maturity. However, it comes with the credit default risk of the issuer. A decreasing credit quality of the issuer may cause its bond’s price to decline.
Image Credits: pixabay.com (CC0 Public Domain)

Image Credits: pixabay.com (CC0 Public Domain)

d. TUITION FEE LOAN SCHEME
Aside from the options above, you can consider loans such as the Tuition Fee Loan Scheme for approved schools. The loan has 0% interest during the period of study.
e. CPF EDUCATION SCHEME
The CPF Education Scheme allows you to borrow from your CPF ordinary account to sustain your child’s local tertiary education costs at approved schools. It is subjected to a withdrawal cap. After graduating, your child will be required to repay the amount withdrawn plus additional interest.
Sources: 1, 2, & 3

Read More...

Important Money Matters To Sort Out After Divorce

Ending your relationship with someone you vowed to spend a lifetime with is never easy. Getting a divorce causes a significant life change that is often complex and stressful. It involves coping with several issues such as division of assets, discussion of maintenance, and custody of the children. These issues bring forth emotional, economic, and legal considerations.

Divorce is not simplistic wherein one solution fits everyone else’s circumstance. It is case-specific as it takes the needs and means of each person into account. Even the length of your marriage affects the division of assets. For instance, if your marriage is brief, the court may decide to part you with the money you had before coming in to the relationship.

According to the 2013 Population Trends by Statistics Singapore, marital dissolutions are escalating with 7,386 in 2009 from 7,216 in 2008. With this increasing number of divorced couples, it is important to discuss the financial matters to sort out after the breakup.

1. IMMEDIATE FINANCIAL CONCERN

Your first concern shall be the recurrent household bills. If you had been paying your bills through a joint account, you have to make some arrangements with your bank to dissolve this account and pay through your personal account instead. Remember to update your GIRO arrangements as well.

2. MAINTENANCE AFTER DIVORCE

Maintenance is intended to cover the living expenses and necessities of the wife and her children. Under Singapore’s law, maintenance for the wife continues until she remarried or passes away while the maintenance for the children continues until the age of 21 or until graduation. The husband can pay the wife in a lump sum but only monthly maintenance is allowed for the children.

There is no specific amount or length of maintenance as the Family Justice Courts examine the situation to arrive at a reasonable and fair decision.

3. THE FAMILY HOME

One of the most daunting decisions you have to make (especially if you used your CPF savings to buy a property with your ex-spouse) is the housing arrangement. Are you going to sell your family home? Or will you keep it while the other one moves out?

If you intend to sell your house wherein CPF savings were used to purchase it, you will need to apply for CPF refunds to your respective accounts. Please visit the CPF Board website for more information.

Image Credits: pixabay.com (CC0 Public Domain)

Image Credits: pixabay.com (CC0 Public Domain)

Sources: 1, 2, & 3

Read More...