Why Personal Loan Is Not As Daunting As It Sounds

All is fine and dandy when your life is nicely panned out for you, but as Singaporeans, we can never be too cautious. What if a once-in-a-lifetime opportunity knocks, and you suddenly require a larger-than-expected sum of money to seize this opportunity?

Opportunities can come in different forms in your various stages in life. There may be investment opportunities, a chance to go abroad on an exchange programme, or a chance to further develop your skill sets.

If you find yourself short on cash and need a sum of money to tide you over a short period of time, a personal loan can come in useful.

When we think about loans, most would frown upon it. We would assume that borrowers are incapable of managing their own finances, or that they are financially irresponsible. That is but a misconception, as personal loans are merely tools that can improve our lives if used in a responsible and wise manner.

As compared to home loans, car loans or educational loans which have specific purposes, personal loans are a more flexible type of loan which can be used for almost any purposes you wish. The most straightforward of which are personal instalment loans, where you borrow a lump sum of money from a bank. You can use the borrowed cash for any reason you like. Payment is in fixed monthly payments over a specified time period.

You never know when you might need a loan, but it’s always good to be aware that there is this option out there without breaking the bank. A loan can be useful in the following situations:

  • A buffer for depleting all your savings – taking a personal loan instead of using up your emergency savings in case of, well, emergencies, and you need the savings
  • Seizing opportunities with smaller cash outlays – taking a personal loan for immediate cash to enrol in a workshop or class to improve your skill sets and employability, which will result in an eventual higher return
  • Fulfilling aspirations – perhaps an exchange abroad, a hobby you’ve always wanted to master or even an important bucket list item
  • Repaying a high-interest loan first – taking a personal loan to pay off higher-interest loans, such as credit card bills

Not all banks and money lenders are created equal. Different financial institutions offer different incentives – some offer lower interest rates while others have lower minimum criteria.

Ultimately, it’s always good to compare loans before applying for one, so you end up with the best bang for your buck for your personal goals and budget – one that has the lowest interest rate, the lowest fees, meets your requirements and has the best welcome offers.

SingSaver offers a convenient platform for comparing between different financial institutions. For a limited time only, get the first 3 months of interest FREE when you apply from SingSaver’s website. That’s not all — SingSaver has also partnered OCBC to offer 0% interest free loan applicable for loan with 2 years tenure.
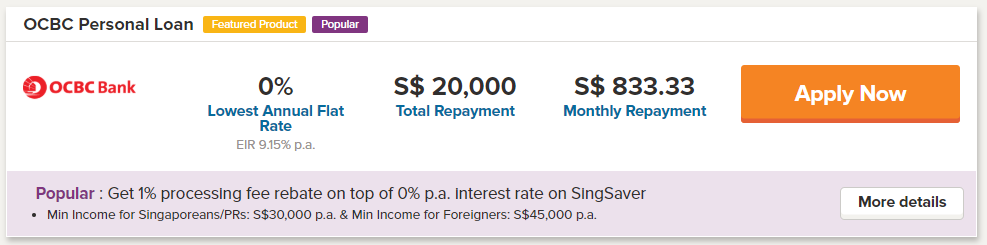
Not only does choosing the right loan mean meeting your goals earlier, it also means that you can pay off your loans faster.

So while you’re all up for borrowing, be aware of the higher interest rates accounts that you’re liable to paying, so that you clear off those loans first.
Read More...

Why It Makes Sense To Choose A Bank Mortgage Loan

Before you purchase your HDB flat, you will be faced with the dilemma of deciding between a HDB loan or a bank mortgage loan. This article demonstrates why it may make sense to choose a bank mortgage loan.

HDB loan is pegged at 0.1% above the interest rate of CPF Ordinary Account. Therefore, the current interest rate on HDB loan is 2.6%. However, you might be able to save on your interest payment if you choose a bank mortgage loan instead. Based on a comparison result from SingSaver, the interest rate on current bank loans varies from 1.62% to 2.28%. Therefore, if you are looking to borrow a loan amount of $200,000, HSBC’s TDMR-Pegged Package is the cheapest at 1.65%. Using this as a comparison, a home owner would need to pay $907 per month by taking a HDB loan, as compared to $814 per month by taking the HSBC home loan ($200,000 mortgage, 25 year repayment at 2.6% versus 1.65%). Therefore, assuming interest rates for both packages stay constant, a home-owner who took up the HSBC TDMR-Pegged package would have saved approximately $28,000 over the loan tenure.

Banks also tend to reward loyal customers for doing more banking activities with them. By taking a bank mortgage loan, the homeowner will be able to earn higher interest rates on their savings deposited. Some common savings accounts are the DBS Multiplier, Standard Chartered Bonus Saver Account and the Maybank SaveUp Account. The additional interest rate given to your savings is on top of the savings that you may have already incurred as a result of paying lower interest expenses on your home loan.

If you are able to apply a savvy refinancing strategy, you will be able to gain some form of control over the interest rates that you pay on your bank mortgage loans. Some of the strategies include

  • Actively comparing home loans on comparison website such as SingSaver to get the best quote,
  • refinance only after lock-in periods are over to avoid paying any penalties,
  • negotiate with the banks for waivers on items such as legal fees etc.

Therefore, by applying a smart refinancing strategy, you can further maximize the savings on your bank mortgage loan.

Do note that a bank mortgage loan has some slight disadvantages as well. A higher downpayment (20% of purchase value) is required, of which at least 5% must be in the form of cash. Therefore, greater cash outlay will be required when choosing a bank mortgage loan over a HDB loan. However, if your budget meets this cash outflow, then this will not be an issue to you. For such group of prospective home-owners, it makes perfect sense for them to choose a bank mortgage loan.

Here’s an exclusive offer from SingSaver: Apply for a home loan and receive $200 cash upon approval. For more details, click here.


Read More...

Essential Tips On Finding The Right Loan For Your Needs

You have a stable job right now, but since you’re thinking of embarking on a new business soon, you’ll need to acquire a loan. You need the money to purchase your supplies, to hire people and to market your business’ existence. And while you’re certain that you need a loan for this endeavour, you still don’t know how to actually to find the right loan for your needs. In your mind, you think this decision is crucial because the success of your business relies on it – and you’re right. To help you out with your dilemma, consider the essential tips below to find the right loan for you:

  1. How much do you really need?

Just because a lender offers you a loan worth thousands of dollars, doesn’t mean you should take it immediately. Keep in mind that the bigger amount you borrow, the bigger your payments will be – and this can become an issue if your business isn’t as successful as you’d like it to be. On the other side of the coin, if your loan is too small, it might not help you in any way, and you’ll end up paying for high-interest rates. To avoid being placed in this kind of situation, carefully think how much you need for your business and look for a lender which can give you that amount.

  1. What is the interest rates?

Aside from the loan amount itself, you should also consider the interest rates associated with it. Is the lender offering you the amount you need but has very high-interest rates? Are there any lenders in the market who can give you a lesser interest rate? Think about these things first before choosing a loan. It’s also essential to ask the lender if there are any other fees or penalties to be paid after you received the loan. All of the processes involved in the loan should be transparent to you to avoid problems in the future.

  1. What’s the term?

Different loans have different terms. Some loans can be paid for six months while others, in ten years. Since you’re still starting a business, it might be best to settle for a loan which will require you to repay within an extended period of time. This will allow you to save up for the interest rates and the loan, without putting your business’ operations at risk.

Aside from the things you’ve read from this article, it’ll also help if you can actually work with experts when it comes to finding the right loan for your needs. Places like oinkmoney.com may be a good starting point.

Be A Responsible Borrower

Finding the right loan for your needs is never easy. There are several things to think about to come up with the best possible decision. You also have to keep in mind that your responsibility as a borrower doesn’t end the moment you receive the money – you should pour in your time and effort in order to pay all of these in time. If not, your life may be affected negatively. Remember all the things presented in this article, and for sure, you’ll come up with a decision on which loan to get without compromising your financial health in the long run.

Sarah Porter

Sarah Porter is a money-savvy writer and mum of two based in Manchester, UK. She is the Brand and Marketing Manager at the UK loan website Oink Money (oinkmoney.com), as well as the founder of a well known money-saving website. Sarah is originally from Edinburgh where she studied Business and later worked in finance for a FTSE 100 company. She left her career in finance to pursue her passion for writing, a move which allowed her to travel the world with her laptop while running her blog.

Read More...

How to find the best personal loan without damaging your credit rating

A personal loan can help you amass funds that you would require to pay for pressing expenses. However, if you have a poor credit score, you are likely to find it very difficult to get a personal loan approved. A bad credit rating will spoil your chances of acquiring a personal loan. A poor credit score or a poor credit history indicates your failure to pay back your loan amounts. Hence, if you are finding it difficult to get a personal loan approved, you should improve your credit history first.

Often we make the error of assuming that specific factors affect our credit rating when they have no impact. Factors such as your debit card usage, marital status and age have no role in determining your credit score. Other details such as your employment status, bank balance and income have no direct impact on your score, though it might influence your approval.

You will have to give individual attention to the factors that are likely to impact your credit score and the chances of getting a personal loan. Simply getting an appropriate personal loan is not sufficient as you also must have a decent credit rating to benefit from it. If you are looking for a personal loan by taking on a trial-and-error method it will be destructive and fruitless.

Let us look at some tips you can follow to find a personal loan without hurting your credit score:

Pay your dues on time

Even if you fail to pay your credit card bills and other dues on time, try to pay it within a month of the due date. Making payments within 30 days past the due date is accepted normally. By doing so, you can opt for the personal loan of your liking, without worrying about getting rejected. It will also have a positive influence on your credit score.

Avoid applying for personal loans from different lenders

If you are applying for multiple personal loans at the same time, your credit rating is likely to take a hit. This indicates your lack of confidence in obtaining a loan and which will reflect badly on your credit rating. Instead of applying for personal loans from multiple lenders, you must check the prospective rate of interest and eligibility by using a Personal Loan Eligibility Calculator.

Get a quote from the lender of your choice

If you apply for a personal loan formally, the lender will carry out a credit check. It is likely to leave a negative score on your rating. If this takes place often, your score will go down drastically. So, find out if you are eligible for a loan before applying by talking to the moneylender in person and going through the eligibility criteria.

Compare the fees charged by different lenders

Many banks offer low-interest rates but charge substantial supplementary fees. These include high prepayment penalties, excessive processing fees, arbitrary upkeep charges and more. These charges are likely to raise your burden and may lead you to miss a monthly instalment that may eventually damage your credit rating. So before applying, compare the charges and fees imposed on personal loans.

Seek help from non-banking financial institutions

Your chances of getting a loan will enhance significantly if you widen your pool of options. Apart from banks, approach non-banking financial institutions. These institutions are listed with Monetary Authority of Singapore and offer a wide range of loans. Like banks, these institutions also depend on your credit score and history to evaluate your risk as a debtor. However, these institutions may have different packages for different risk appetites.

Your credit score is the most significant financial tool to get the best personal loan. If you have the right credit score, you will easily get the approval for loans at the best available interest rates. As a result, it is very important that you make sure your lender offers you competitive interest rates and simple personal loan eligibility calculator together with other sufrepplementary benefits.

Read More...

5 Commandments Of Borrowing Money

Whether you are borrowing your friend’s stilettos for a wedding or your mother’s mixing bowl for a party, we live in a culture that embraces the culture of borrowing.

There are certain rules involving this act such as dry-cleaning the suit that you borrowed. But, do you know the rules involving money? Here are just some commandments to get you started!

#1: THOU SHALL NOT BORROW BEYOND YOUR MEANS

Your hard-earned income must not revolve around debt repayments. Exhaust your resources to borrow an amount that is within your means. If you cannot afford an item then, skip it first! Save enough money and direct it to completing a purchase.

Many financial experts recommend that you maintain a Debt-to-Income ratio of 20%. How do you calculate this? Simply add up your monthly debt categories (i.e., excluding mortgage) and divide the total amount by your net monthly income. Ask for your partner’s help, if necessary.

#2: THOU SHALL NOT PAY LATE

There are several reasons why Japanese citizens uphold the value of time. For starters, paying on time is one of the vital rules of borrowing money.

It goes without saying that late fees or increased interest rates add insult to injury. Not to mention, being late can dramatically lower your credit score. In the long run, your bad track record will be reported to the credit bureaus.

#3: THOU SHALL NOT BORROW FRIVOLOUSLY

Borrowing money is an act built on a strong purpose and an intention of repayment. For debt categories that yield a sense of profit such as for education or for business, loaning money makes sense. The same ideal applies to loaning items that you will use for a long period of time (e.g., a car).

However, you must contemplate on loaning money for fleeting pleasures. Do you really need the latest gadgets in the market? Is attending an international music festival a crucial part of your life? Are you willing to spend thousands of dollars on a wedding anniversary weekend? Lastly, is a designer bag better than a functional one? Aim to borrow money for the right reasons.

#4: THOU SHALL NOT BE FINANCIALLY PRESSURED

Close your eyes and envision the last time you experienced social pressure. Was it your first day at a new workplace? Or, does it go way back in your secondary school days? At a certain degree, all of us felt pressured to do something we do not want to. It exists in all forms including financial situations.

In said challenging times, a deperate move that people make is to borrow money. You get trapped into a situation that unable you to make smart financial situations. Combat this by creating an emergency fund. Cushion your financial problems and continue to cultivate this fund even when you are experiencing debt. Please do not borrow or lend money to friends or relatives, if you are solely pressured into doing so!

#5: THOU SHALL NOT COMPARE LOANS CARELESSLY

Upon entering a new field, my basic instinct is to do my research about the company. Before travelling to a new country, my basic instinct is to do my research about their culture. What basic instinct do I apply before taking on a loan? Well, research of course! I recommend that you do the same thing too.

Image Credits: pixabay.com

Comparing loans is more than the mere act of scoring the lowest interest rates. You must carefully read thru the essential elements such as penalties and add-ons. For instance, some insurance companies include costly add-ons such as specific life insurance. The extra elements will increase the interest rate of the money that you borrowed. Thus, you must approach everything with extreme caution.

Sources: 1 &2

Read More...