Newbie’s Guide To Financial Planning

Picture a curve going up. This is your lifetime money curve. Every decision you make affects the direction of your curve. For example, once you earn money from your first job then, the money curve will go up higher. But living in reality, your money curve are exposed in certain financial pressures such as taxes and bank fees, which, will push the money curve direction down. The good news is that, with a strategic plan that evaluates the potential pressures, you can survive or prevent the downward money curve. This strategic plan is called a Financial Plan.

Financial planning is an important process that draws out your monetary future. It is a process of managing your finances and knowing where you want to go. Here are 5 pointers to guide you…

1. INFORMATION GATHERING

In order to manage your finances, the first step is to gather all the important documents (e.g., bank statements, insurance policies, and investment accounts) and financial information. Organize these records by using a folders or filing accessories that will cost less than S$5 at Popular Bookstore or Daiso.

2. EVALUATING

After you gathered all the essential information, you must evaluate all the areas of your financial life including long-term savings (e.g., retirement and college fund), short-term savings (e.g., payment for bills and emergency fund), key documents (e.g., durable power of attorney and will) and insurance (e.g., life and car insurance). Calculating your net worth is also in this step.

3. SETTING GOALS

Following evaluation is goal setting. It involves two things: identifying your goals and knowing what resources you need. Identifying your financial goals both short-term (e.g., staycation in Bali) and long-term (e.g., retirement at 50s) is vital to knowing what your next plan of action will be. After plotting your goals, you must know the resources you will need to achieve them.

4. TAKING ACTION

Since your goals are set, your next plan of action is to decide whether you shall do it on your own or to hire a professional financial advisor. The personal actions you can take may include purchasing life insurance, creating a will, and setting a side money for your retirement. While, hiring a professional can help you reach your objectives in the midst of time your constraints.

5. MONITORING

The last step is monitoring. Monitoring involves tracking your progress and altering your goals based on the reevaluation of your current economic situation.
Image Credits: carlocanyougo.tumblr.com

Image Credits: carlocanyougo.tumblr.com

With a systematic and a holistic Financial Plan, may your money curve take a flight…leading you to success! 🙂

Sources: Entrepreneur and MoneySense
Read More...

Retire In The World’s Cheapest And Most Beautiful Countries

In 2013, Live and Invest Overseas and International Living examined the best countries worldwide where you can retire for S$1,760/month or less.

Live and Invest Overseas is a trusted online publication dedicated to giving information on retiring, living, and investing overseas. With a similar goal, International Living, established in 1979, had surveyed experts and contributors to get the cost of living information of countries around the world. These are the latest large-scale data available to date:

1. NICARAGUA, CENTRAL AMERICA

Nicaragua, a multiethnic country of approximately 6 million people, is one of the most beautiful countries in America as it boasts its Pacific coastline, Caribbean beaches, and freshwater lakes. You can live for about S$1,350 a month inclusive of utility bills (no air-conditioning), groceries, entertainment, rent, maid (3 times a week), and health insurance. Not a bad way to retire!

2. PHILIPPINES, ASIA

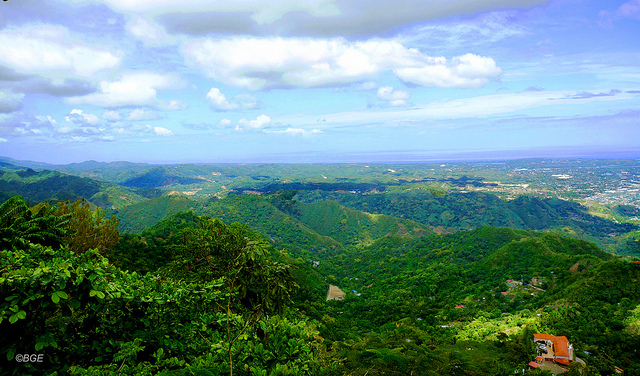
Philippines, a picturesque country consisting of 7,107 islands, ensures that you can enjoy a low-cost island life once you retire. For about S$1,410 a month, you can avail services such as electricity, water, gas, cable TV, Internet, grocery shopping, rent, and entertainment costs. Relax in the beach and reminisce the old times while sipping a fresh coconut juice that will cost you lest than a dollar!

Image Credits: Brian Evans via Flickr

Image Credits: Brian Evans via Flickr

3. MALAYSIA, ASIA

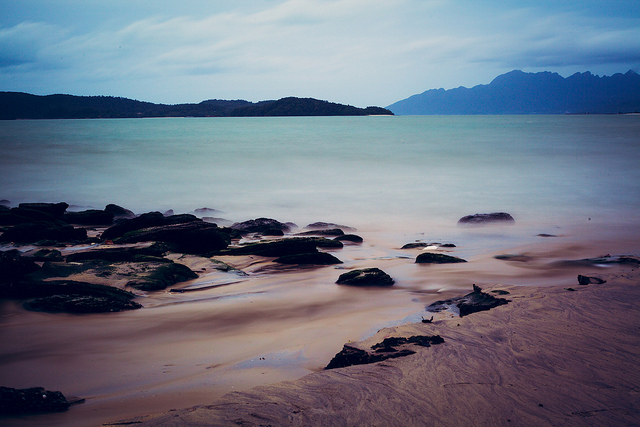
How about retiring close to home? In Malaysia, you can retire for a cost of approximately S$1,450 a month. This is inclusive of utility bills, handphone bills, Internet services, maid (4 hours/week), transportation, health insurance, and entertainment. Keep your healthy physique by buying a bagful of fruits that will cost you only S$5.

Image Credits: Tatiana Vdb via Flickr

Image Credits: Tatiana Vdb via Flickr

4. ECUADOR, SOUTH AMERICA

Aside from English, if you are fluent in Spanish then, you may consider living in Ecuador. With mostly Spanish-speaking citizens, Ecuador known for its rich ecosystem that hosts many species of plants and animals. For approximately S$1,760 a month, you can indulge on utilities, grocery shopping, health insurance, maid (2 times a week), Internet services, cable TV, handphone services, entertainment, and transportation. The top choice of most American retirees is the wonderful city of  Cuenca due to its glorious weather and affordable real estate.

Image Credits: andresmbernal via Flickr

Image Credits: andresmbernal via Flickr

Age gracefully by retiring in a comfortable place where you are at peace with your finances! The world is your oyster. 🙂

Sources: 1 , 2, and 3

Read More...

Should You Borrow Money From The Bank Or Licensed Money Lenders?

Believe it or not, the bank often lends its money to people who are stable enough that they would not need to borrow the money anymore. This is why some Singaporeans turn to alternative ways of acquiring money including Licensed Money Lenders. Now, before you borrow money from any of these options, you must know their differences first.

BANKS

Loaning money from the bank guarantees that there would be future repayment of the principal amount and its interest. A loan can either be specific or open-ended credit up to a certain ceiling amount.

Characteristics:

1. Larger Loans – Banks are ideal for larger loans such as renovating your home, starting a business, or buying a car.

2. Credit Assessment – A good credit score with a low debt to credit ratio is a must to qualify for a loan. And, if you want to pay a low interest rate, you need to be vigilant about your credit score.

LICENSED MONEY LENDERS

Licensed Money Lenders are businesses that are regulated by the Singapore’s Law. Unlike the loan sharks that lend with high interest rates, licensed money lenders’ fees are controlled by the parameters of the Law, which means you can expect to have a fair deal. Some of the known money lenders in Singapore are Max Credit, CashMax Credit and Quickloan Pte Ltd.

Characteristics:

1. Smaller Loans – Licensed money lenders are the ideal option for smaller loans such as paying utility bills, getting your laptop fixed, or repairing your car (even amounting to S$1,500).

2. Credit Assessment – Unlike the banks, licensed money lenders give more leeway in the credit score. This is because they lend a significantly smaller amount. So, if you have a bad credit and you cannot get a personal loan, licensed money lenders are there for you.

3. Transaction Speed – Licensed money lenders approve the borrower’s application within the day itself!

4. Higher Interest Rate – Since they carry more risk for granting loan to people with poor credit rating, they usually charge a higher interest rate and late fees

Image Credits: Taber Andrew Bain via Flickr

Image Credits: Taber Andrew Bain via Flickr

Although the license money lenders give more freedom in the credit score, they will reject your application if you have a large sum credit card debt or if you have an outstanding loan from another money lender.

Sources: Investopedia and Sumo Credit Pte Ltd

Read More...

3 Investments You Should Immediately Consider

Investment is an asset purchased with a purpose to generate more income in the future or to sell it for a higher price. There are a myriad of investment selections available in the market today but here are a few 3 simple investments you can start with…

1. MUTUAL FUNDS

Being a newbie in the investment scene is not a problem anymore. With Mutual Funds, you can entrust a professional investment manager to produce capital gains for you and your co-investors. Mutual funds are investments that gather the investors’ money into a pool to make multiple types of investments, known as the portfolio. Shareholders participate proportionally in the gains and losses. Lastly, it gives the budding investors the access to professionally manage, diversified portfolios of equities, bonds and so on. This can be difficult and nearly impossible to create with a small amount of money.

2. CENTRAL PROVIDENT FUND INVESTMENT SCHEME

The Central Provident Fund (CPF) Investment Scheme is a way to invest your CPF savings to various banks such as OCBC, DBS, or UOB. This will enhance your retirement or housing money. Simply, the money you will generate from your investments will eventually go to your CPF account and not your pockets. To be eligible, you need to be above 18 years old and have over S$20,000 in your Ordinary Account (i.e., used for housing, education, investment, and insurance) and over S$40,000 in your Special Account (i.e., used for retirement). Compare the investment options and their charges. Instead of complaining about the CPF, why don’t you start investing?

3. REAL ESTATE INVESTMENT TRUSTS

Real Estate Investment Trusts (REITs) allows you to invest your money to a range of properties. REIT investors pool their money to buy buildings then, they divide the rental returns. This is a cheaper alternative to buying a property. Furthermore, REITs receive special tax considerations and mostly offer investors high yields and liquid method (i.e., converting your assets into cash) of investing in real estate. Although there are benefits, it is important to hire a trusted REIT Manager. One REIT in Singapore is CapitaMall Trust including properties such as Plaza Singapura, Junction 8, and JCube.

Image Credits: www.rentalrealities.com via Flickr

Image Credits: www.rentalrealities.com via Flickr

Sources: Central Provident Fund Board, MoneySense, and Investopedia

This article does not form part of any offer or recommendation, or have any regard to the investment objectives, financial situation or needs of any specific person.  Before committing to an investment, please seek advice from a financial or other professional adviser.

Read More...