5 Things to Consider Before Getting a Personal Loan

Personal loan is one of the most sought-after loans in Singapore. With a personal loan, you can borrow funds from a financial institution and pay them back in fixed instalments over an agreed period. However, you typically need to meet a minimum income requirement and to pass a background check on your credit history.

Generally, it is much cheaper to get a personal loan rather than borrowing money from a moneylender. Moreover, you will need to submit a lesser number of documents compared to other types of loans such as car or home loans. These factors contribute to the popularity of personal loans.

Apart from these, consider the following points before getting a personal loan.

#1: PERSONAL LOAN HAS A MINIMUM INCOME REQUIREMENT

The eligibility for personal loan incorporates your income and your age. You need to pass the minimum income requirement (e.g., S$30,000 per annum) and the age requirement (i.e., usually under 60 years old). These strict requirements ensure that you will be capable of paying off the loans and that you will be paying on time.

#2: PERSONAL LOAN IS NOT FOR EVERYONE

Now that you know the basics of personal loans, you must remember that it is not for everyone. You need to contemplate the purpose of the loan before getting one. Compute for the monthly fees and other charges.

You see, it is better to use your extra funds if you intend to use the loan for lifestyle desires. Lifestyle desires include purchasing a new gadget or booking an international cruise. On the other hand, you need to carefully assess your business plan and financial situation if you intend to use the money for business and investment.

#3: PERSONAL LOANS CAN MAKE OR BREAK YOUR CREDIT STANDING

Examine your credit standing as it affects your personal loan application. Paying your dues on time is one way to keep your credit score on the good side. In contrast, accumulated monthly charges and overdue payments add red flags to your credit score. As a new applicant, carefully consider the terms and conditions of the bank.

#4: PERSONAL LOANS COME WITH SERVICE FEES AND OTHER CHARGES

Do not be fooled by the attractive loan prices flashed by the banks and financial institutions. You can end up paying more money due to service fees and other charges. You will pay the monthly fees along with the effective interest rates. If you plan to pay by cheques, returned checks can also be charged. Thus, new applicants must consider other forms of payment such as mobile banking.

#5: PERSONAL LOANS SHOULD BE YOUR LAST RESORT

Building an emergency fund is a part of the fundamentals of being financially savvy. When an unfortunate event takes a toll on your finances, you still have reserves. If your emergency funds have depleted, personal loans should be your last resort.

Avoid spending your personal loan to impress other people with your new gadget or with a grand getaway. Spend your extra funds on your lifestyle desires instead of borrowing money.
Personal loans have a variety of advantages and disadvantages. We hope that you can manage your finances well if you decide to avail yourself of a personal loan in the future.
Sources: 1 & 2


Read More...

Hidden Costs of Using Credit Cards in Singapore

You may not be able to pay for items in full cash, but you can certainly swipe your card! Credit cards offer convenience to afford larger purchases anytime. It can also help you establish a good credit history.

However, it is important to understand the actual cost of credit cards when fees and interest are factored in. The actual cost of using a credit card can add up!

#1: THE COST OF PAYING MINIMUM DUE ONLY

There are consequences to only paying the minimum fee. Firstly, it will take longer to eliminate your balance. Secondly, your interest continues to accrue steadily in what you owe. Your minimum payment may not be enough to cover the interest charges for the month.

#2: THE LATE PAYMENT FEES

If the payment is passing your due date, the late payment charges vary by bank. This charge is usually between S$60 to S$80. A late payment may cause you to forfeit some of your credit card rewards or cause your interest rate to spike significantly higher than your regular purchase.

#3: THE COST OF CASH ADVANCE

Did you know that you can use your credit card to withdraw cash through a cash advance? Cash advance on credit cards can be awfully expensive, with interest rates going as high as 30%. You can be charged about 6% of the amount withdrawn per transaction or a minimum of S$15.

Apart from that, you will also receive an interest rate charge of around 28% per annum, subject to compounding if the charges are not repaid in full on the amount withdrawn.

#4: THE COST OF OVERSEAS TRANSACTIONS

These days, more and more people are shopping online using their credit cards. When shopping from an overseas website, it is important to know that there are fees. Two types of fees that can be charged are foreign transaction fee and dynamic currency conversion fee.

#5: THE ANNUAL COSTS

While some annual fees can be waived, others cannot. The next time you receive your credit card statement with the annual fees charged, try calling your bank to ask for a waiver. Doing this may save you more than a hundred dollars!

Image Credits: pixabay.com

Sources: 1 & 2


Read More...

When is it a Good Idea to Take a Personal Loan in Singapore?

Are you caught in a sudden financial situation? To alleviate the severity of your problem, you can consider taking a personal loan.

Personal loan allows you to borrow money to pay for personal expenses, which you must repay over time. Things can quickly turn into a nightmare when you do not have the capacity to pay it back. This leads us to these questions: Is a personal loan nonideal? When is bad and when is it helpful?

How It Works

A personal loan is an installment loan that gives a fixed amount of money to the borrower. Its most appealing feature is its ability to provide funds for any purpose. You are not limited by one purpose alone.

When it comes to repayment, you can expect that the interest rate will be fixed. This repayment plan ensures that you get a relatively lower or more affordable interest rate compared to the interest rates offered by credit cards.

When Is It Harmful?

A personal loan can turn into a borrower’s nightmare when the funds are used for the wrong reasons. It is important to think about the consequences of borrowing instead of only focusing on addressing the unpleasant financial situation.

For instance, basic needs are supposed to be covered by your monthly income. You should not use a personal loan to cover your basic needs because these are recurring expenses. Imagine what will happen if you use your personal loan to finance your weekly grocery trips!

When Is It Helpful?

1. When you borrow money for a meaningful purpose such as medical emergencies or major occasions

Despite being a joyous occasion, weddings are expensive. From your wedding dress to your venue, an average wedding in Singapore can cost about S$30,000. With a personal loan, you will get to ease your cashflow by spreading out the payment at a friendlier pace.

2. When you have a strategic plan to pay the loan back

As a borrower, it is your responsibility to plan how you can pay back the amount. If you already know how you are going to spend the money, you should also know how you will be able to repay it. Moreover, it is important to only borrow what you need!

3. When you have the discipline to pay your loan/s on time

Commit to repaying your loan on time. Most personal loans become a burden for the borrowers when they fail to pay their due dates on time. Negligence can lead to penalties, making your personal loan seem unbearable.

4. When you want to consolidate your debts

Do you have multiple loans at high interest rates? If so, it is a practical idea to consolidate these outstanding balances into a personal loan with a lower interest rate. Doing this will enable you to choose your repayment terms and ensure that you can afford the monthly installments.

5. When you want to take the less complicated borrower’s route

Personal loans are less complicated to avail compared to other loans. In fact, many banks and financial institutions in Singapore allow you to apply for it online.

6. When you want to boost your credit score

You can get a small personal loan to improve your poor credit score. Just make it a habit to pay the installments on time and commit to your repayment plan! This works because your payment records will show lenders how trustworthy and reliable you are.

CONCLUSION

Personal loan allows you to borrow money to pay for personal expenses, which you must repay over time. It can either be harmful or helpful, depending on how you use it.

On one hand, personal loans can be used as tools for the right circumstances such as paying for your wedding day. On the other hand, personal loans can be harmful when you do not have a strategic repayment plan or when you use it for the wrong reasons. Weigh your options before committing to a personal loan.

Sources: 1, 2, & 3

Read More...

Have You Heard About the Debt Snowball Strategy?

WHAT IS THE DEBT SNOWBALL STRATEGY?

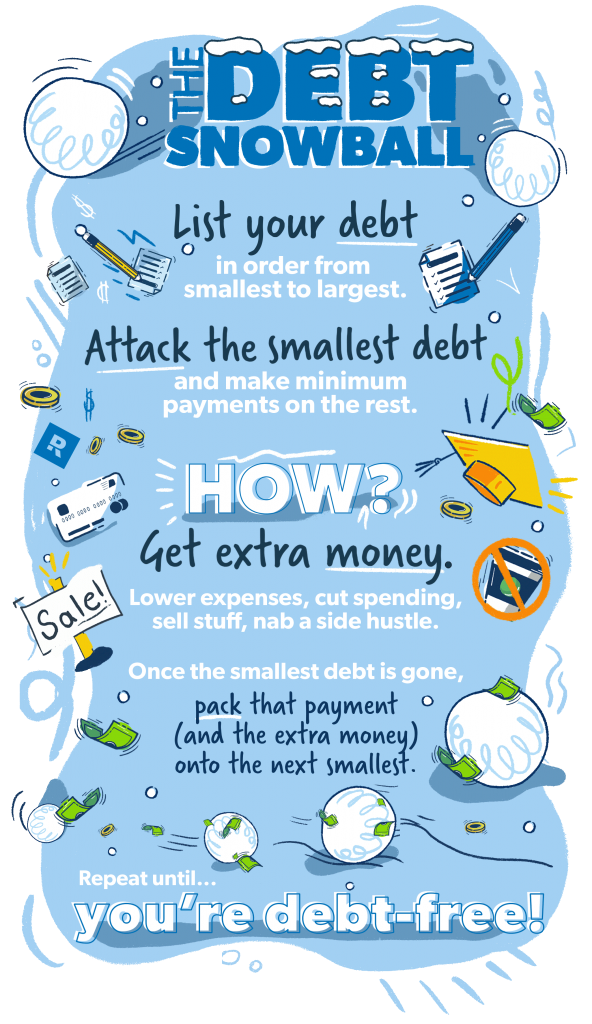
Popularized by personal finance author Dave Ramsey, Debt Snowball is a strategy used for paying down debts. It focuses on paying off your smallest balance first before moving to the larger ones. The person lists down all his or her debts and categorizes these debts from smallest to largest. Money will then be allocated to pay off the smallest debt first, while making only minimum monthly payments on the other debts.

This strategy would not save you as much interest as the Debt Avalanche, but it can help you stay on track in your debt repayment journey.

HOW CAN YOU GET STARTED?

List down all your debts to get started. Then, gain momentum as you knock out each remaining balance. When the smallest debt is paid in full, you will move your efforts toward the next smallest debt on the list. To illustrate, here are the steps:

Step 1: Write down all your debts from smallest to largest, regardless of its interest rate

Step 2: Make minimum payments on all your debts except for the smallest debt on your list.

Step 3: Pay as much money as you can on your smallest debt. This is going to be your priority.

Step 4: Repeat the process until each debt is paid in full.

HOW CAN I APPLY THIS STRATEGY?

Let us imagine that you can afford to put aside S$1,000 every month to pay off your three sources of debt: S$30,000 worth of student loan debt (minimum monthly payment of S$500), S$5,000 worth of car loan debt (minimum monthly payment of S$100), and S$2,000 worth of credit card debt (minimum monthly payment of S$50).

Using the Debt Snowball strategy, you would spend a total of S$650 to cover each debt’s minimum monthly payment. You would then put the remaining S$350 toward the credit card debt because it is the smallest on your list.

Once the credit card debt has been fully paid, the extra payment will go towards your second-smallest debt. At some point, you will be able to clear up your car loan and focus all your money on eliminating your student loan. Like a snowball, each paid-off debt frees more cash to get rid of the remaining ones.

WHAT ARE ITS ADVANTAGES AND DISADVANTAGES?

Its advantages include increasing your motivation and easing your implementation. Paying off three or more debts can seem more manageable if you break it down into smaller pieces. You see, you can get frustrated with the repayment plan if you focus all your efforts on the largest debts. Furthermore, this strategy is easy to implement. You do not need to compare the annual percentage rates (APRs) for all your debts or to tackle deeper into the terms and conditions. You simply need to know the balance owed and its minimum monthly payment to categorize each debt.

On the other hand, its disadvantages include issues in time and interest. Since this strategy focuses on repaying debts according to the balance, it may take you longer to pay off your debts. Interest can be another factor because you are prioritizing balances over APRs. Remember, you could end up paying more money in interest over time.

WHAT ARE THE KEY TAKEAWAYS?

The Debt Snowball Strategy helps you pay off debts by focusing on your smallest balance before moving on to the remaining ones. You will always pay the minimum on each of your debts, except on your smallest debt. This strategy cannot save you as much interest as the Debt Avalanche, but it can help you stay motivated.

Prudent use of personal loans can save you more in the long run, especially if you’re currently saddled with severe credit card debt or are facing a financial emergency that could wipe out your savings. Ultimately, the only way to prevent bad debt from snowballing is to have the discipline to control your spending until your loan is repaid. If you find yourself in any of the above situations and are looking for a personal loan to help relieve some of your financial burden, be one of the first 2 applicants daily to have your 1st year’s interest (up to S$550) covered by SingSaver. Click here to learn more. Offer until 21st Mar 2022. T&Cs apply.

Image Credits: ramseysolutions.com

If you need professional help when it comes to managing your debt, you can seek assistance from a credit card counselling organization such as the non-profit organization called Credit Counselling Singapore (CCS).

Sources: 1, 2, & 3

Read More...

6 Overlooked Perks Of Using Credit Cards In Singapore

From ease of purchasing items to fraud protection, credit cards offer the several benefits. Just please use your plastic card responsibly!

#1: RECEIVE ONE-TIME BONUSES

Signing up for new credit cards will qualify you for the initial bonuses or sign-up rewards. You can new items or reward points that can be redeemed for travel, gift cards, and more.

In contrast, a debit card that comes with a bank account generally offers no initial bonus or ongoing opportunity to earn rewards.

#2: TAKE ADVANTAGE OF THE GRACE PERIOD

When you make a purchase using your debit card, your money disappears right away. When you make a purchase using your credit card, your money remains in your account until you pay for your bill.

There are two main benefits of having a grace period. Firstly, the time value of money will save you money. Delaying eventual payment will allow you to earn money during the grace period. Secondly, you will have a set period to pay for your purchase. You do not have to watch your bank account balance vigilantly.

#3: BE REWARDED WHEN YOU SHOP

Reward credit cards allow its users to earn points for every purchase. Many reward credit cards give bonus points for certain categories such as restaurants, groceries, or petrol.

When your earnings reach a threshold, points can be redeemed for travel or gift cards to shop at participating retailers and restaurants. All you need to do is to choose a card that suits your spending pattern and your lifestyle!

#4: INDULGE IN THE COMPLEMENTARY CASHBACK

You can get a percentage of the items you purchase refunded back into your account with the credit card’s cashback feature. How much you get back varies per bank or credit card. Nonetheless, rebates usually apply only to certain items.

For instance, Standard Chartered’s Unlimited Cashback credit card* lets you receive 1.5% cashback on your eligible purchases. No minimum spending is required. Another example of no minimum spending is the Citi Cash Back+ Card*. It offers 1.6% cashback on all spending.

Note: *Terms and Conditions apply.

#5: BUILDING OF CREDIT SCORE

When people assess whether you are qualified for a loan extension or not, banks do not just look at your annual income. These banks also examine your credit rating for indications of proper financial management.

By using your credit card sensibly and regularly, you can build reputable credit rating. Enjoy lower interest rates for your unsecured loans by having a better credit score. Be sure to pay off your balances each month and keep your spending to a minimum.

#6: EXTRA LAYER OF PROTECTION

Apart from the convenience that cashless shopping can bring, certain credit cards offer a range of purchase protection insurance. This type of insurance will help ensure your peace of mind as you shop. The following protections can be given by your issuer: a. price protection, b. purchase protection, and c. fraud protection.

Image Credits: unsplash.com

Price protection refers to getting back the difference or a percentage of the difference if an item you bought on your card drops in price within a timeframe. Purchase protection refers to the coverage against theft or accidental damage. This protection usually lasts until six months. Lastly, fraud protection refers to being refunded for purchases made using your stolen credit card or card details.

Sources: 1, 2, & 3

Read More...