HDB has allocated over $742 million for upgrading works of these HDB flats islandwide

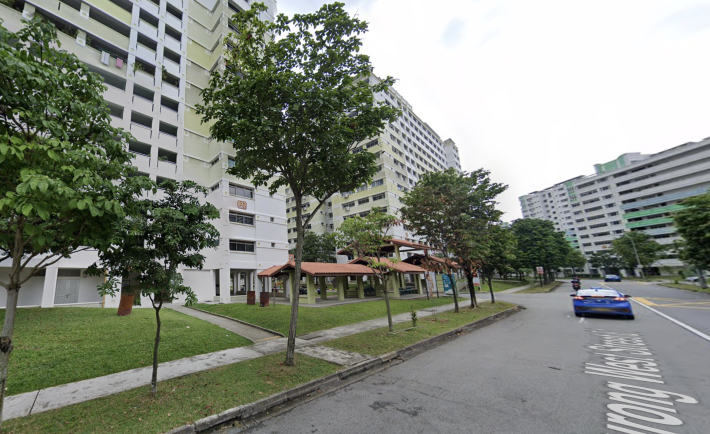
833 Jurong West Street 81

The Ministry of National Development (MND) and Housing & Development Board (HDB) have earmarked over 53,000 HDB flats for enhancements, as part of the latest Home Improvement Programme (HIP) selection.

These flats are dispersed throughout the island, and here’s the full list:

Hougang

Blks 358 – 363 Hougang Avenue 5

Blks 830 – 835 Hougang Central

Blks 460 – 468 Hougang Avenue 8/Hougang Ave 10/Upper Serangoon Road

Serangoon

Blks 531 – 535, 535A & 536 – 542 Serangoon North Avenue 4

Blks 500 – 506, 506A, 506B & 507 – 511 Serangoon North Avenue 4

Blks 232A, 234A, 236A & 255 – 258 Serangoon Avenue 2 / Central Drive

Ang Mo Kio

Blk 317 Ang Mo Kio Street 31

Blks 104A, 104B, 253 & 253A Ang Mo Kio Street 11/21

Blks 613 – 619 Ang Mo Kio Avenue 4

Toa Payoh

Blks 35 – 37, 43 – 46 & 48 – 50 Lorong 5 Toa Payoh

Blks 80, 80A, 80B, 81, 81A, 81B, 82, 82A, 82B, 84, 84A, 84B & 86 Lorong 2/4 Toa Payoh

Choa Chu Kang

Blks 201 – 204 & 205 – 221 Choa Chu Kang Avenue 1/Central

Blks 223 – 239 Choa Chu Kang Central

Blks 553 – 569 Choa Chu Kang North 6 / Street 52

Blks 305 – 308, 340 – 346 & 350 – 355 Choa Chu Kang Avenue 4/Loop/Central

Blks 150 – 152 & 154 – 160 & 162 – 164 Jalan Teck Whye

Blks 751 – 761 Choa Chu Kang North 5

Blks 762 – 771 Choa Chu Kang North 5 / Street 54

Bedok

Blk 140 Bedok North Street 2

Bukit Panjang

Blks 437, 440, 442 & 447 – 453 Fajar Road/Bukit Panjang Ring Road

Blks 170 – 176 Gangsa Road / Lompang Road
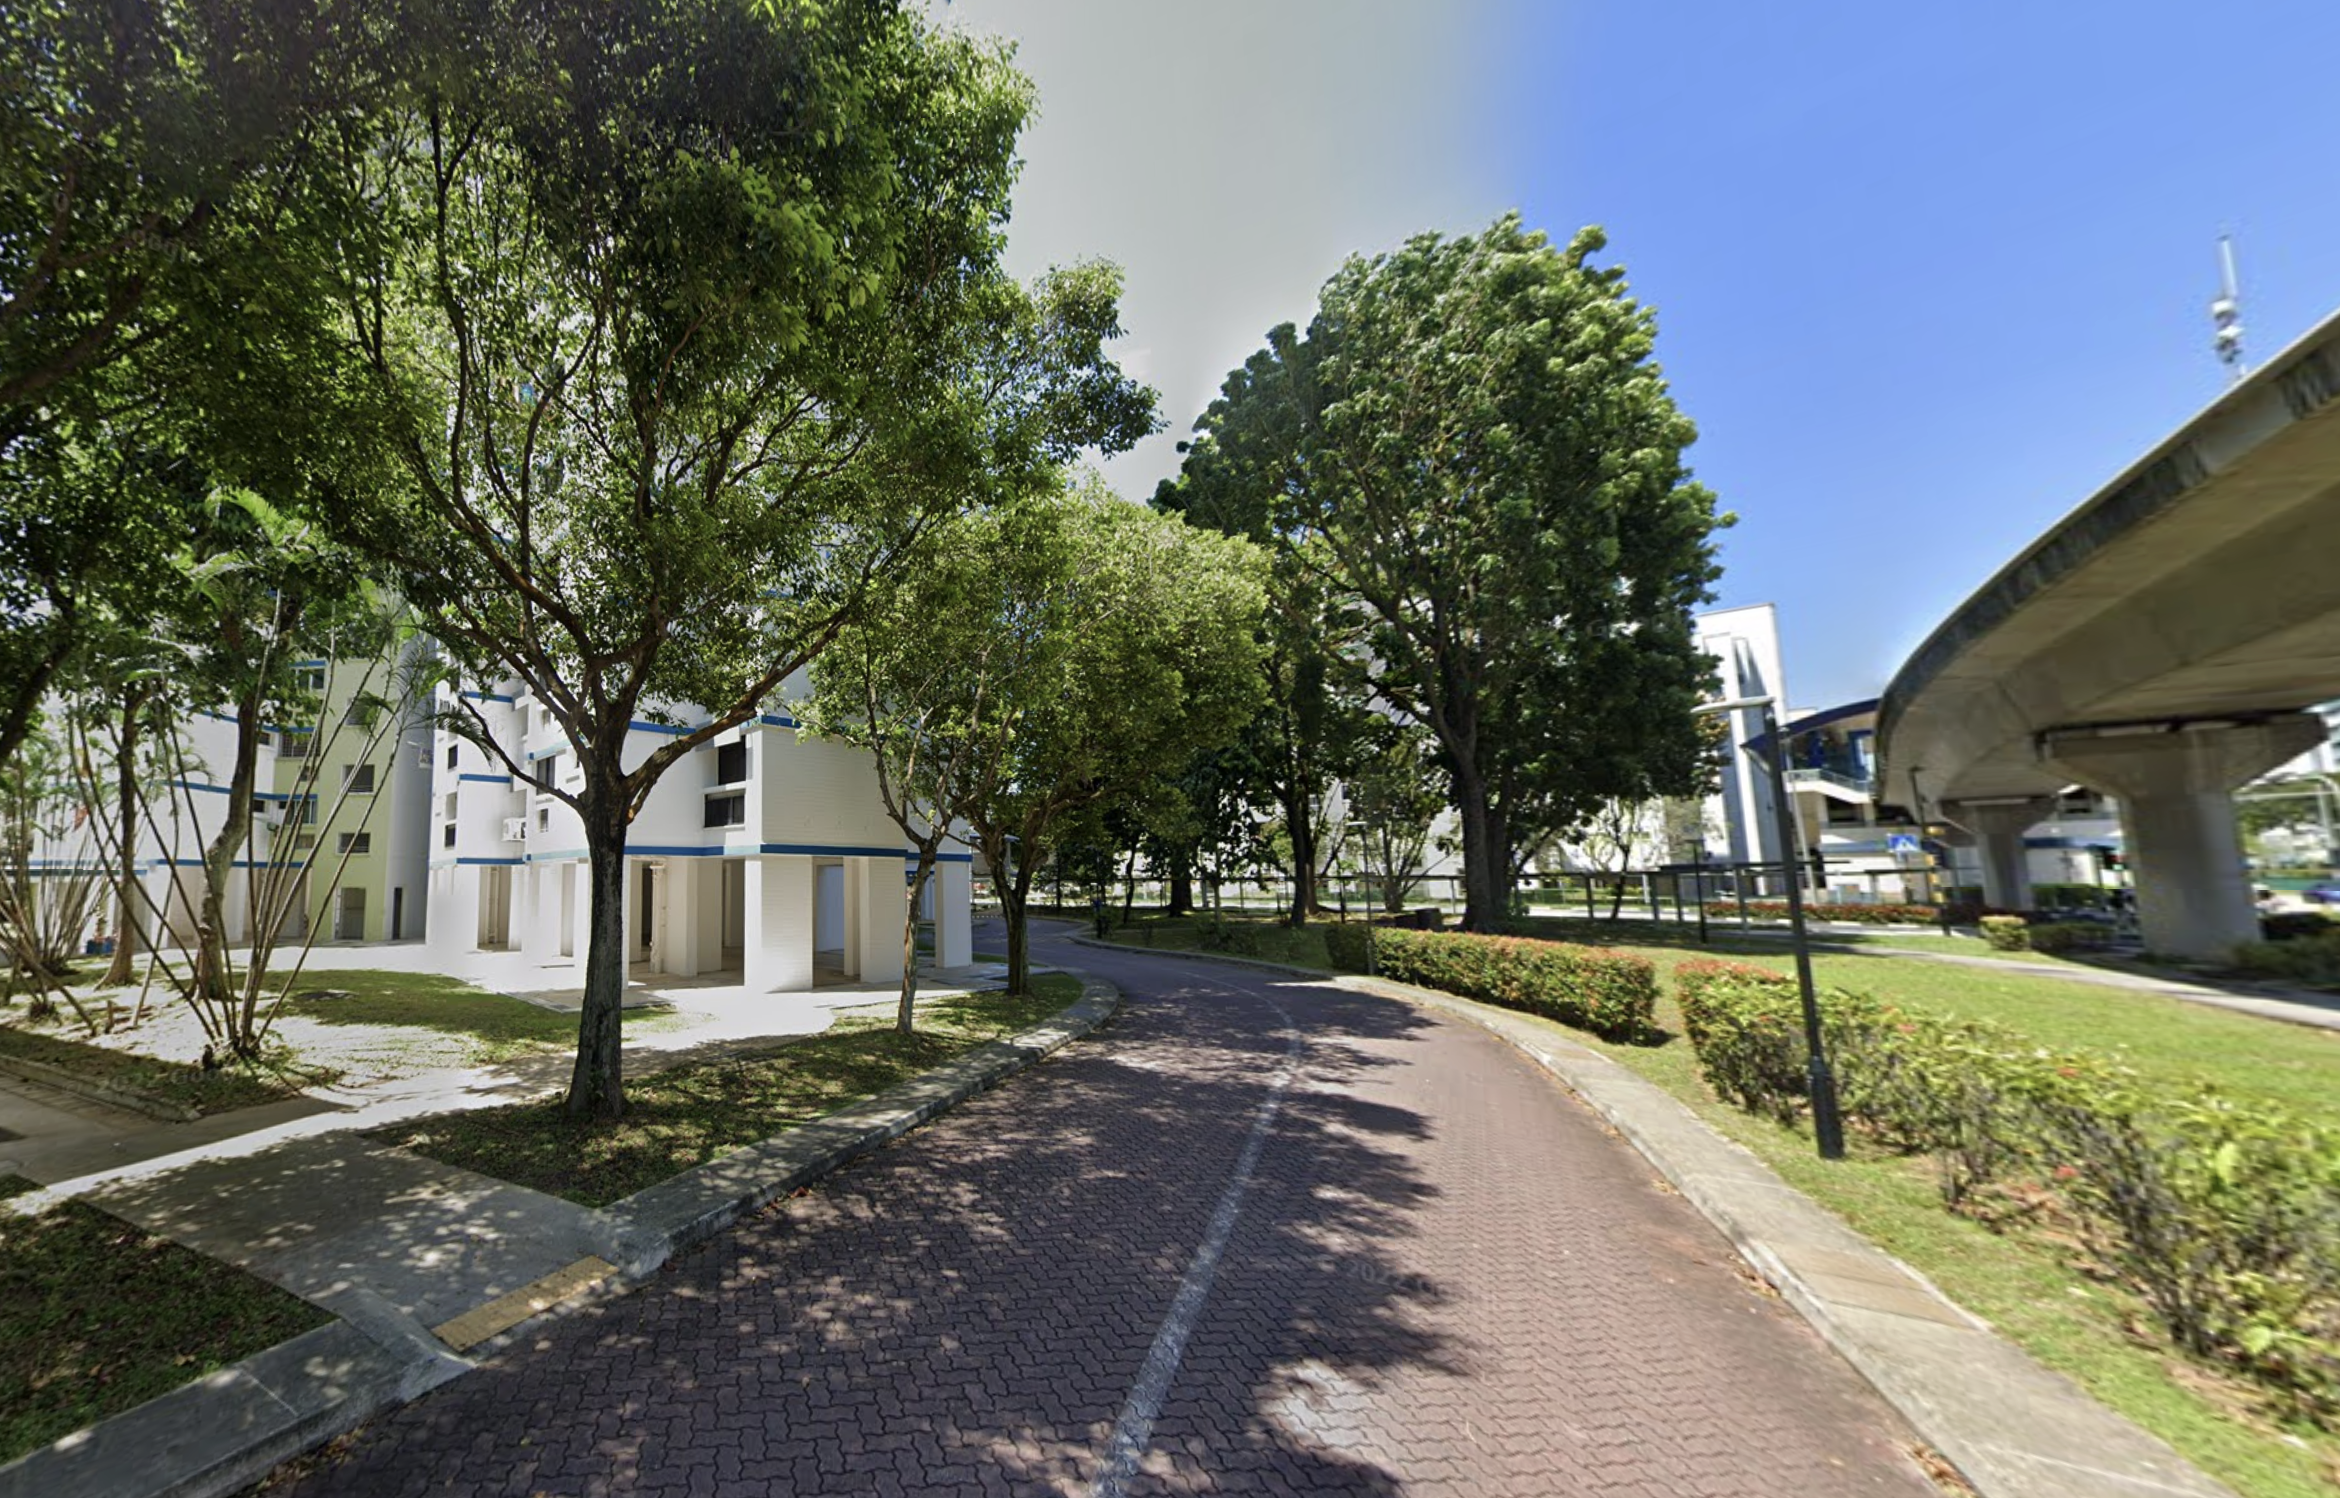
171 Gangsa Road

Image Credits: Google

Kallang

Blks 4, 5 & 6 Boon Keng Road

Blks 13, 14, 14A Upper Boon Keng Road

Blks 59A, 59B, 59C & 60 Geylang Bahru

Bukit Batok

Blks 285 – 287, 290A – 290G & 291A – 291E Bukit Batok East Avenue 3 / Street 24

Geylang

Blks 27 – 29, 33, 41, 42, 55, 56, 92 & 92A Balam Road / Circuit Road /Pipit Road

Blks 28, 30, 56 & 9 Cassia Crescent / Pine Close

Woodlands

Blks 401, 406, 408 – 410, 413 – 418, 421 & 424 – 427 Woodlands Street 41

Blks 851 & 856 – 864 Woodlands Street 83 / Blks 601 – 605 Woodlands Drive 42

Blks 701 –713 Woodlands Drive 40 / 70 / Blks 744 –747 Woodlands Circle

Blks 714 –720 Woodlands Drive 70 / Avenue 6

Blks 659 – 664 Woodlands Ring Road

Pasir Ris

Blks 463 – 466 & 478 – 487 Pasir Ris Street 41 / Drive 4

Blks 531 – 543 & 564 – 569 Pasir Ris Drive 1 / Street 51

Blks 544 – 562 Pasir Ris Street 51

Blks 203 – 216 Pasir Ris Street 21

Blks 217 – 230 Pasir Ris Street 21

Blks 231 – 251 Pasir Ris Drive 4 / Street 21

Blks 180 – 199 Pasir Ris Street 11/12

Blks 500 – 521 Pasir Ris Street 52

Sengkang

Blks 229 – 236 Compassvale Walk

Tampines

Blks 491A – H, 492B – D, 493A – E, 494B, 494C, 495A – F, 496B – G Tampines Avenue 9 / Street 43 / 45

Blks 242 – 247 & 253 – 256 Simei Street 1/5

Blks 472, 474, 476, 477, 479 – 484, 485A, 485B, 486A – C, 487A – C, 488A, 488B, 489A – C, 490A & 490B Tampines Avenue 9 / Street 43 / 44 / 45

Blks 301 – 323 Tampines Street 32 / 33

Blks 371 – 374 & 381 – 396 Tampines Avenue 7 / Street 32 / 34

Queenstown

Blks 129 – 133 Clarence Lane

Blk 134, 135 & 139 Jalan Bukit Merah

Blks 3, 3A, 5, 30, 30A Holland Close / Blks 7, 7A Commonwealth Avenue

Jurong West

Blks 961, 965 – 966 & 974 – 980 Jurong West Street 92 / 93

Blks 810 – 832, 828A & 830A Jurong West Street 81

Blks 357 – 363 & 365 – 369 Yung An Road / Corporation Drive

Blks 752 – 761 & 764 – 766 Jurong West Street 74

Blks 833 – 853 Jurong West Street 81

Blks 115 & 321 – 336 Ho Ching Road/ Tah Ching Road/ Kang Ching Road

A budget exceeding $742 million has been allocated for these upgrades.

Initiated in 2007, HIP assists flat owners in addressing prevalent maintenance issues like spalling concrete and ceiling leakage, which occur due to the natural aging of older flats.

This year, flats chosen for HIP will use a new Corrosion Resistant Repair (CRR) method in bathrooms to reduce recurrence.

Although the CRR method is more expensive and time-consuming, it will be primarily used for repairing spalling concrete in toilets, where the issue is most prevalent.

For other areas, HDB will continue using the current localized repair method.

The program will also include upgrades to improve the general living conditions of these flats.

Will you or someone you know be affected? Spread the news!
Read More...

The advantages of marrying a miser

wedding couple

Marrying/Married a penny-pincher?

Sure, your spouse’s frugal ways might drive you insane sometimes, but have you ever considered the perks of being hitched to a miser?

Before you roll your eyes… Hear us out.

Financial stability
  • Goodbye, money worries!

Your penny-pinching partner’s careful spending habits mean you’re less likely to get yourself into debt.

While your friends are maxing out credit cards, you will be sitting pretty with a healthy bank balance.

  • Your personal money guru

Think of your miser spouse as your very own financial advisor (minus the extra fees).

They are great at sniffing out deals and making investments; you will be building a nest egg that would make even Warren Buffett proud.

Who needs a lottery ticket when you’ve got a miser by your side?

  • Future-proofing your finances

With a miser in your corner, you’re likely to have a financial cushion to fall back on.

So when your car decides to throw a tantrum or your pipes’ got a leak somewhere, you won’t be left high and dry.

Budget consciousness

Ever catch yourself tossing out almost-empty shampoo bottles or letting food spoil in the fridge?

fridge filled with food

Image Credits: unsplash.com

Your thrifty spouse will put an end to that faster than you can say sorry.

They will influence you on what it means to stretch every dollar (and cent), making sure nothing goes to waste.

Long-term planning
  • Thinking ahead pays off

Your miser’s money meticulous character means you’re likely to have a solid retirement plan.

While others are scrambling to save near retirement, you will be sipping cocktails on a beach, thanks to decades of savings.

  • Weathering life’s storms

Your miser’s habit of living way below your means also ensures you’re always prepared for life’s lemons.

A sudden job loss or an unexpected medical bill doesn’t sound so scary anymore.

Minimalism and mindful spending
  • Embracing the simple life

When you’re with someone who’s very cautious with cash, you start seeing the beauty in less.

No more drowning in stuff you don’t need but want.

  • Thoughtful purchases, fuller wallet

You will probably find yourself asking, “Do I really need this?” before every purchase.

It’s not about depriving yourself, but about making smart choices.

Marrying a miser isn’t all doom and gloom. Yes, you might have to fight for every penny spent on fun stuff, but your frugal spouse is basically a human ATM, helping you save for the future especially when you’re not too good at it. Plus, you will become a pro at finding ways to live life on the cheap. Who knows, you might even find yourself enjoying clipping coupons and hunting for promotions yourself?

Read More...

What if your husband wants a baby but you’re not ready to sacrifice your career for it?

baby's feet

You’re reading this because you’re not quite ready to trade your office wear for maternity wear.

Balancing career ambitions with motherhood is tough, but even tougher when your partner’s biological clock is ticking louder than yours.

How should you approach this issue?

Well, both of you have valid feelings and your husband’s desire for a mini-me is just as real as your “love” for your job.

Chat about your hopes, fears, and dreams; maybe there’s a compromise hiding somewhere.

What are your options?

  • Delaying parenthood

Who says you need to have a baby right now? Consider setting a future timeline that works for both of you. Perhaps in a few years, you will feel more ready.

  • Alternative paths

Freeze those eggs, girl! It’s like pressing pause on your fertility clock.

  • Career flexibility

Look into flexible work arrangements, remote options, or even part-time gigs. Some employers can be very accommodating (or should be soon).

If you don’t already know, all employers must have a process for workers to request flexible work arrangements starting in December.

Here’s a quick summary of the abovementioned linked news article:

  • From December 2024, all employers in Singapore must have a process in place for workers to formally request flexible work arrangements.
  • Employers have two months to decide on such requests and must provide reasons if a request is rejected.
  • The guidelines aim to make it easier for employees to request flexible work arrangements while acknowledging employers’ right to decide work arrangements.
  • Flexible work arrangements include flexi-place (working remotely), flexi-time (adjusting working hours), and flexi-load (part-time work or job sharing).
  • Employees should make requests responsibly, considering the impact on workload and performance. Employers should explore ways to accommodate requests where feasible. 
  • Tripartite partners will provide support to employers to implement flexible work arrangements effectively, including training and funding.

To make a formal flexible work arrangement request, click through this link to access Tripartite’s guidelines.

Seeking support

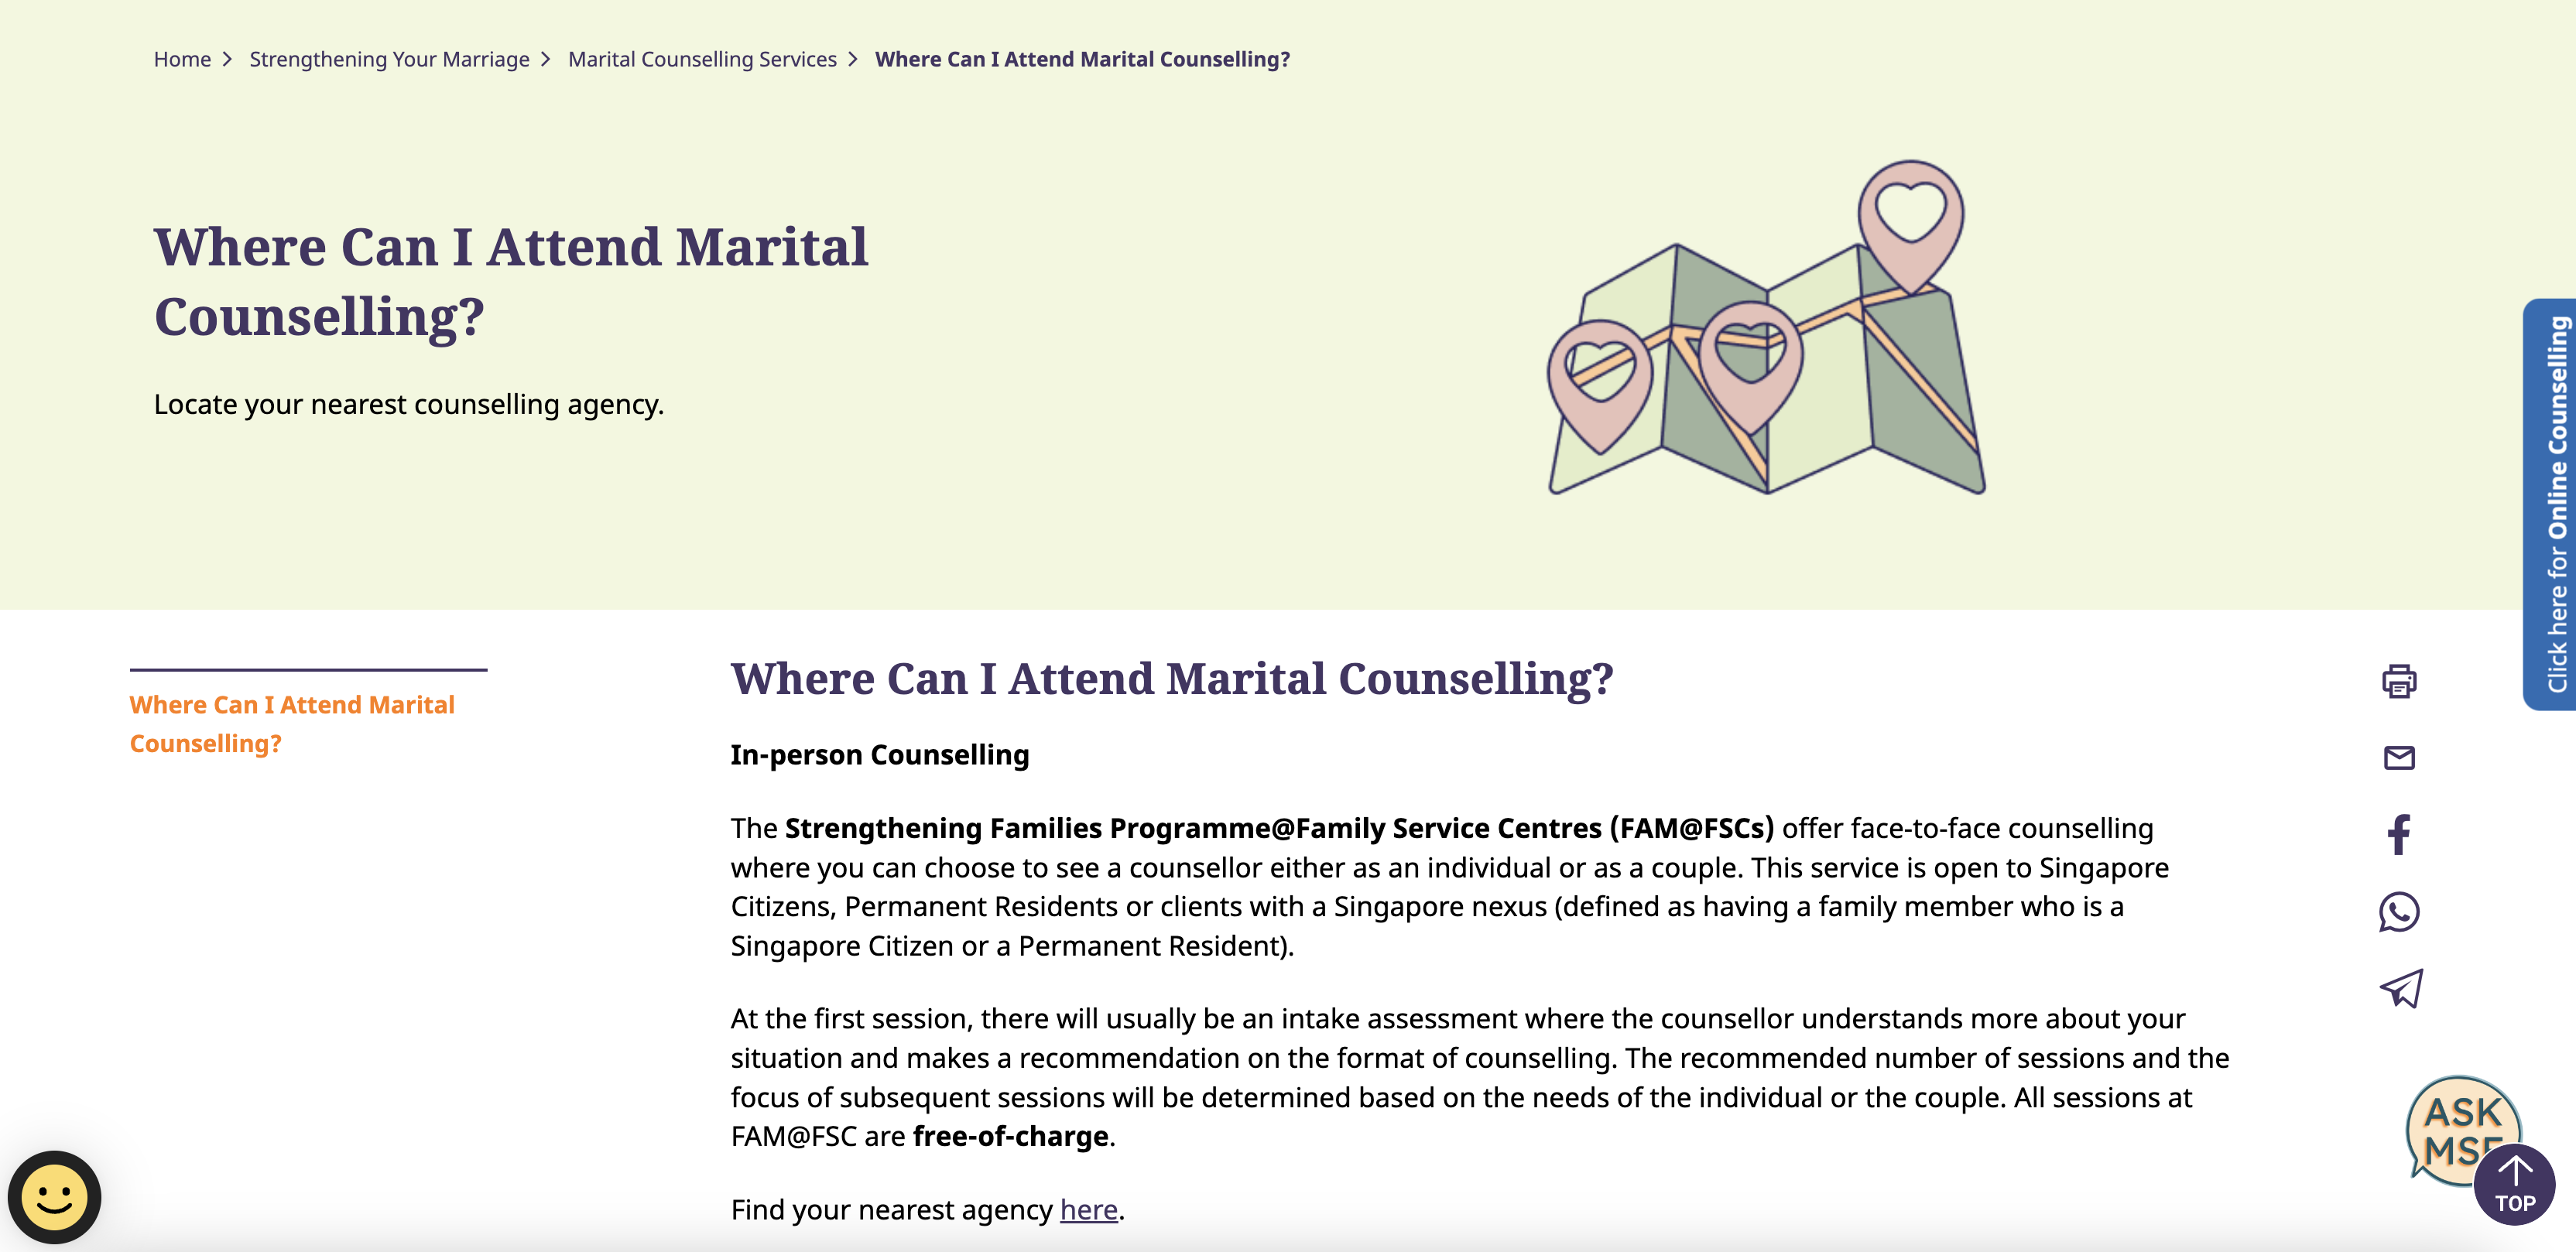
familyassist.msf.gov.sg

You can also consider booking a session with a marriage counselor or family therapist to gain an unbiased perspective and let them be the guiding compass you need.

Or grab teh/kopi/bubble tea with a friend who’s been there, done that.

Also, it’s good to investigate your workplace support options. Are there flexible parental leave policies or back-to-work programs? Chat with HR on what’s available.

Making a decision

  • Setting goals together

As a team of two, write down your short-term and long-term objectives. Where do you see your career in 5 years? What about your family life?

  • Flexibility is key

Life likes throwing us lemons, so keep an open mind.

Maybe you can find an in-between, like delaying parenthood for a year or two while you go chase after some career milestones.

Or perhaps there’s a way to balance both without sacrificing either?

Don’t be afraid to voice your concerns. Your career matters too. Take time to think it through and don’t let anyone pressure you to make an immediate decision. Whatever you decide, make sure it sits well within you. Your life goals are just as important as his.

Read More...

Kiasu Parents’ Guide to Financial Preps Before the Baby Arrives

#1: INSURANCE COVERAGE

When it comes to expecting a baby, it’s always wise to be prepared for the unexpected. That’s why maternity insurance is a must-have. For those who love being ahead of the game, like many Kiasu parents, maternity insurance is essential. Maternity insurance can provide financial protection and peace of mind during this significant life event.

Take, for example, Income’s Maternity 360. With a single premium, this plan offers three years of comprehensive coverage for both mother and baby, including protection against death, 10 pregnancy complications, and 23 congenital diseases. Plus, it includes a hospital care benefit, ensuring you’re covered in various situations.

#2: HOSPITAL BAG

Packing your hospital bag is an exciting step, but it’s important to plan based on your expected stay. Most mothers spend 2 to 3 days in the hospital after giving birth, though a C-section may require a longer stay. Fathers planning to stay with their partners should also consider this when packing.

Think about what will make you comfortable and prepared for those few days. For example, when my friend Lea was expecting her first child, she packed cozy pajamas, snacks, and even a favorite pillow from home, making her stay much more comfortable.

#3: HOME PREPARATION

Bringing your baby home for the first time is a thrilling moment, but it’s crucial to ensure your home is ready. This goes beyond just cleaning; it’s about creating a safe, welcoming environment.

Start by minimizing furniture and switching to non-toxic products (e.g., disinfectants and natural cleaning products). Less furniture means fewer places for germs and dust to gather. For laundry: wash sheets, blankets, and your baby’s clothes with mild detergent to avoid skin irritation. Then, consider professional cleaning if necessary.

#4: EMERGENCY FUND

Life with a baby can be unpredictable, and having an emergency fund is crucial. Aim to save enough to cover three to six months’ worth of your take-home pay. If that seems daunting, start with a smaller goal, like S$1,000, then gradually increase it.

#5: BABY-CENTERED BUDGET

Adjusting your budget to include baby-related expenses is essential. Consider ongoing costs like health insurance, doctor visit copays, diapers, formula, food, clothing, and daycare. Don’t forget one-time expenses for setting up the nursery and stocking up on baby gear. My cousin Nik created a detailed budget before her baby was born and found it incredibly helpful in managing her finances smoothly.

#6: BENEFICIARIES UPDATE

Major life changes, like having a baby, are a perfect time to review and update your beneficiaries on life insurance and retirement plans. You might still have your parents, siblings, or even a previous partner listed instead of your child. When my brother updated his beneficiaries after his first child was born, it gave him great comfort knowing his family’s future was secured.

Image Credits: unsplash.com

Preparing for a baby is an exciting journey filled with many steps, but with a little planning and forethought, you can ensure you’re ready for the adventure ahead.

Sources: 1,2, & 3

Read More...

How to Thrive When a Spender Marries a Saver


You’ve found the love of your life and decided to get married. However, as you plan for your shared future, you realize that one of you is a spender while the other is a saver.

Fortunately, there are strategies to manage joint finances that can satisfy both partners. Here are some tips for maintaining a balanced relationship between a spender and a saver that have been beneficial for me and my spouse.

TALK ABOUT YOUR MONETARY FEELINGS

Money often elicits strong emotions: it can cause anxiety or excitement, and managing it can either calm or stress you out. Before getting married, take time to explore each other’s feelings about money and the reasons behind them. Did you grow up in a household where money was scarce or abundant? Your upbringing significantly influences your money attitudes, and your future spouse might see things differently.

When my husband and I were engaged, we had a deep conversation about our financial upbringings. He grew up in a frugal household where every dollar was accounted for, while I was raised in a family that enjoyed spending on experiences and luxuries. Understanding these backgrounds helped us empathize with each other’s financial perspectives.

DISCUSS YOUR SPENDING PRIORITIES

One partner might value designer items, while the other enjoys an expensive hobby. Perhaps you both love to travel, aspire to own a home, or want to retire early. By discussing your desires, you can find common ground. Planning and saving for shared goals can ensure that both partners are satisfied with the purchases you make together.

We both love to travel, but I tend to splurge on spontaneous trips while my husband prefer saving for bigger vacations. By discussing our priorities, we agreed to save a portion of our income specifically for travel, allowing us to enjoy both planned and impromptu trips. If both partners agree, you can establish a clear plan for discretionary spending and saving for long-term goals.

CHOOSE PAYMENT METHODS WISELY

The pain of spending can be mitigated by using credit cards or small denominations of cash. One-click purchases and buy-it-now payments are also less painful. These payment methods can make spending less distressing for savers. Conversely, using cash, especially in large denominations, can make spending more painful for savers, though spenders are generally less influenced by the payment method.

Image Credits: unsplash.com

I noticed that my husband found it easier to stick to our budget when using cash. We decided to allocate a monthly cash allowance for discretionary spending, which helped us control our expenses better.

CONSIDER OPPORTUNITY COSTS

Many people, particularly spenders, often overlook opportunity costs at the time of purchase. When reminded of these costs, spenders tend to make more frugal choices.

For example, in a study where spenders had to choose between a S$950 and a S$1,360 stereo, they were more likely to choose the S$950 stereo when reminded that the cheaper option left them with S$410 in cash. This extra cash can be used for a weekend getaway. Highlighting opportunity costs can help spenders make more mindful decisions.

HIGHLIGHT VIRTUE IN SPENDING

Savers are more willing to spend on virtuous items, such as healthy food, compared to vices. If a saver is hesitant about a vacation, emphasize the virtuous aspects of the trip, such as quality time with family or the health benefits of relaxation.

SEEK PROFESSIONAL HELP

If you struggle to agree on a budget, consider consulting a financial planner. They can help create a budget that works for both of you.

Financial planners offer impartial advice and can determine whether certain expenses are affordable or should be postponed.

AVOID COMPARING YOURSELF TO OTHERS

Spenders and savers often have different life goals, which can lead to tension. Avoid comparing yourself to your partner as a way to justify your spending habits. This approach only deepens the divide and rarely resolves issues.

If you’re a saver, it’s easy to feel superior because you save more, but such feelings can harm your relationship. Remember, spending habits do not define a person’s worth or value in a relationship.

Image Credits: unsplash.com

By following these tips, you can foster a financially harmonious relationship. Embrace your differences, communicate openly, and work together towards common goals to ensure a happy and prosperous future.

Sources: 1 & 2


Read More...