Singapore Wedding Ang Bao Rates Guide Verified by Popular Venues
Been putting off checking your mortgage rate because the whole thing feels like a moving target?
Fair. Rates have been shifting all year, and if you last looked at your home loan when you signed the papers, chances are the market has already moved past you.
Here’s the good news: rates have actually softened compared to where they sat a couple of years ago. The less good news? “Rates are lower” doesn’t automatically mean your current package is a good deal. Let’s break down what’s actually happening with home loan rates in 2026, and what’s worth paying attention to.
Fixed rate packages for HDB flats and private property are currently landing in a fairly tight range, with the most competitive promotional packages sitting well below the “headline” rates banks advertise publicly. Floating packages, pegged to SORA (more on that below if you’re not familiar), have also eased from their highs.
The catch is that “current rates” isn’t one number. It’s dozens of packages across 16-plus banks, each with its own spread, lock-in period, and fine print. What looks like a great fixed rate on a bank’s website is sometimes beaten by an unpublished promotional rate available only through a broker.
Fixed rate means your interest rate stays the same for a set period, usually 1 to 3 years. You know exactly what you’re paying each month. The tradeoff is that if rates drop further after you lock in, you don’t benefit until your lock-in ends.
Floating rate packages move with SORA, the benchmark that replaced the old SIBOR system a few years back. These often start with a lower headline rate than fixed packages, and they give you more flexibility to switch once your lock-in ends without penalty. The tradeoff is your monthly repayment can shift if the benchmark moves.
Neither is objectively “better.” It depends on your risk appetite and how long you plan to hold the loan. If you’re the type who wants to know exactly what’s leaving your account every month, fixed wins. If you’re comfortable riding some movement in exchange for a potentially lower starting cost, floating is worth a serious look.
This is the question we’re getting asked the most. Here’s a rough way to think about it.
If your current lock-in period has already ended, or is ending soon, and you haven’t checked rates in over a year, it’s very likely you’re paying more than you need to. Banks don’t proactively lower your rate just because market rates have dropped. You have to go and get the better deal yourself.
If you’re still deep in a lock-in period, run the numbers before jumping ship. Early repayment penalties can eat into the savings from switching, so it’s worth comparing the penalty cost against what you’d actually save over the remaining lock-in.
A quick gut check: if the rate gap between what you’re paying and what’s currently available is more than 0.3 to 0.5 percentage points, it’s usually worth running the full comparison.
Here’s the thing nobody tells you when you’re comparing Singapore mortgage rates on your own: the rate you see advertised on a bank’s website is often not the best rate that bank is actually willing to offer.
Banks run promotional packages that aren’t always publicly listed, and mortgage brokers get access to these because they bring in volume. This is where working with a broker like DollarBack Mortgage tends to make an actual difference, not just in finding a lower rate, but in comparing all 16 major banks at once instead of you calling each one individually. On top of that, using a broker for refinancing or a new purchase can come with cash rewards of up to $3,300, which stacks on top of whatever rate savings you land.
If you’ve got a loan above $300k, that’s not a small amount to leave on the table.
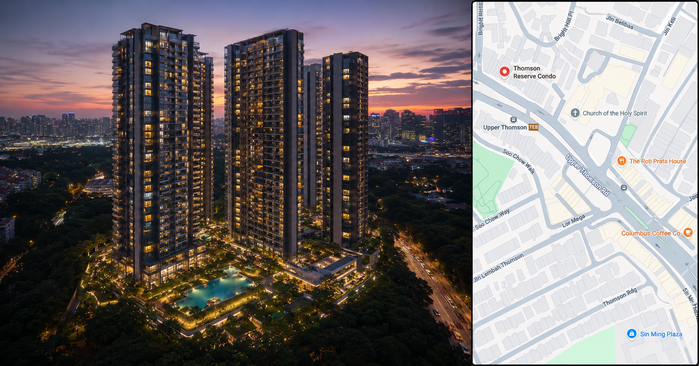
For most Singaporean families, buying a condominium is the single largest financial commitment they will make. Getting the structure right — CPF usage, loan quantum, cash reserves, and TDSR positioning — matters enormously before you commit to a unit.
This guide breaks down the real numbers for the most anticipated new launch condo at Upper Thomson — Thomson Reserve at Bright Hill Drive in District 20 — so you can assess whether it fits your financial profile before the showflat opens.
Official pricing has not been released as of mid-2026, with the showflat preview targeted for later this year. Based on the land acquisition cost of S$1,178 psf per plot ratio and current D20 market benchmarks, analyst estimates place launch pricing in the mid-$2,300s to $2,700 psf range.
In practical quantum terms:
For a Singapore Citizen buying their first private property with a bank loan, the Loan-to-Value (LTV) limit is 75%. For a $2.1M 3-bedroom unit, the maximum bank loan is $1.575M and the remaining 25% ($525,000) must come from CPF OA funds and/or cash.
Of the 25% downpayment, at least 5% must be in cash (the option fee on booking). The remaining 20% can be CPF OA and cash combined. Assuming $150,000 in CPF OA savings, the minimum cash outlay on a $2.1M unit is approximately $270,000 in cash — before legal fees and BSD.
BSD is tiered and frequently underestimated. On a $2.1M purchase:
Total BSD: approximately $68,600. This must be paid in cash or CPF OA and is separate from your downpayment.
Singapore’s Total Debt Servicing Ratio (TDSR) caps monthly debt repayments at 55% of gross monthly income. At a 3.2% stress-test rate over 25 years, a $1.575M loan generates monthly repayments of approximately $7,600. To qualify comfortably, you would need a minimum gross monthly income of approximately $13,800 with no other outstanding debt.
HDB flat owners can own one HDB flat and one private property simultaneously — but must sell the HDB flat within 6 months of receiving keys to the new condo (after TOP). With Thomson Reserve’s expected TOP in the 2028–2029 range, upgraders have approximately 2–3 years to plan the transition while continuing to service their HDB loan at favourable rates during construction.
The Upper Thomson corridor has seen consistent PSF growth of 6–10% annually since 2020, supported by the completion of the TEL and increasing demand from families seeking top primary school catchment. Thomson Reserve is the first mega development in this enclave in over a decade — a structural undersupply condition that supports long-term pricing.
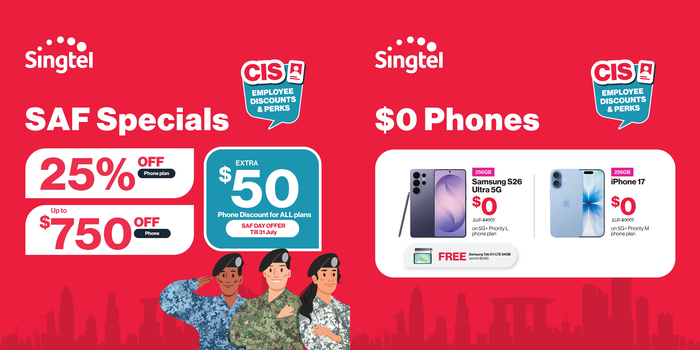
In celebration of SAF Day 2026, Singtel is recognising the dedication and service of Singapore’s national defenders with exclusive Corporate Individual Scheme (CIS) mobile offers for eligible Ministry of Defence (MINDEF), Singapore Armed Forces (SAF) and Ministry of Home Affairs (MHA) personnel.
Available until 31 July 2026, the limited-time promotion lets eligible customers enjoy 25% off Singtel mobile plans every month, along with total handset savings of up to $750 when they sign up for an eligible mobile plan.
Exclusive SAF Day 2026 Offers
Eligible MINDEF, SAF and MHA personnel can enjoy:
Prefer SIM-Only?
Those who don’t need a new phone can opt for Singtel’s popular SIM-Only Plan from just $19.25/month, which includes:
How to Redeem
Eligible customers can:
The exclusive SAF Day 2026 promotion is available until 31 July 2026.
Ask us questions, discover the latest offers & more on Telegram.
Drivers, this is one fuel deal you may want to take note of before the month ends.
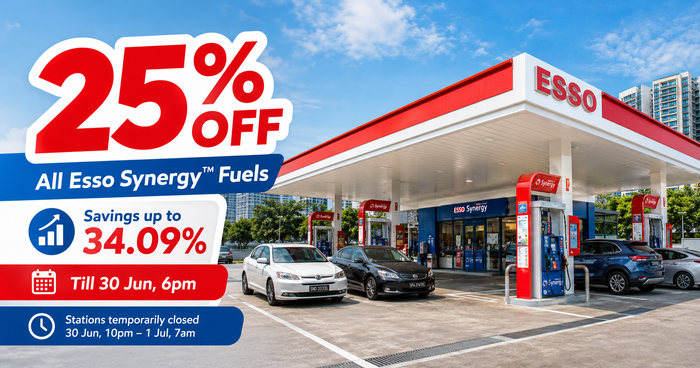
From now till 30 June 2026, 6pm, Esso Smiles members can enjoy 25% off all Esso Synergy™ fuels at Esso stations islandwide. The promotion comes just before Esso stations undergo operational changes, with all stations set to temporarily close from 10pm on 30 June 2026 and progressively reopen from 7am on 1 July 2026.

The changes follow ExxonMobil’s sale of its Esso-branded retail fuel station network in Singapore to Indonesia-based Chandra Asri Group. The deal covers nearly 60 Esso stations and related supply agreements, with Chandra Asri expected to continue using the Esso brand and sourcing fuel from ExxonMobil.
On top of that, the convenience retail side at Esso stations is also changing. Cold Storage will be taking over FairPrice Group’s convenience retail operations at Esso petrol stations over the coming months, replacing the existing FairPrice Xpress/Cheers setup with a refreshed in-station retail concept.
For motorists, the main thing to know is simple: pump before 6pm on 30 June.
According to Esso’s promotional materials, drivers can enjoy 25% instant fuel discount, and savings may go up to 34.09% when paired with Surprise Fuel eVouchers. One example shown for Synergy Extra works out to a gross fuel spend of $88, less $22 instant fuel discount and an $8 fuel eVoucher, bringing total savings to $30 and nett fuel spend to $58.

That means a sample gross cost of $3.42/L for Synergy Extra could work out to about $2.25/L after discounts, based on the attached illustration. For Synergy Supreme+, another example shows the nett cost coming down from $3.94/L to about $2.60/L after discounts.

Drivers may also be able to stack partner bank card savings for further rebates, subject to the respective card terms and conditions. Esso has also reminded customers to use any available Surprise Fuel eVouchers for maximum savings.
Those who are not Esso Smiles members can sign up via the Esso app to enjoy the promotion and access future rewards.
With all Esso stations closing temporarily from 10pm on 30 June to 7am on 1 July, drivers should avoid leaving their refuel to the last minute. If your tank is running low, this could be a good time to swing by, use your eVouchers, pay with an eligible partner bank card, and lock in the savings before the transition begins.
Promotions are subject to terms and conditions. Always check the Esso app or station notices before pumping.
There’s a reason most startups fail within the first few years. It’s not always about funding or timing or bad luck. A lot of the time, the founder built a solution to a problem nobody actually had. The best tech entrepreneurs think differently from the start. They don’t begin with a product idea. They begin with a problem.
The most successful founders tend to have personal experience with the frustration they’re trying to fix. Sara Blakely couldn’t find the right undergarment for a specific outfit. Brian Chesky couldn’t afford a hotel room. These weren’t abstract market observations; they were real, lived annoyances.
Tech entrepreneurs do the same thing. They notice friction. They get stuck somewhere and instead of moving on, they sit with it. Why does this feel so broken? Who else hits this wall? That instinct to keep pulling at a thread is what separates people who spot genuine problems from people who chase trends.
Ideas that come purely from a spreadsheet rarely hold up. The entrepreneurs who consistently back winning ideas spend serious time in conversations. With potential customers, with people working inside industries they’re curious about, with anyone who’s touched the problem they’re looking into.
What they’re doing isn’t market research in the formal sense. It’s pattern recognition. When you hear the same frustration described in ten different ways by ten different people, you start to understand the shape of the problem. You also hear things that surprise you, which is often where the real insight hides.
The founders behind some of the most successful growing businesses didn’t validate ideas in boardrooms. They had a lot of uncomfortable conversations, heard a lot of “that’ll never work,” and kept refining anyway.
Not every problem is worth solving. Two questions cut through the noise pretty quickly: how often does this problem come up, and how much does it actually hurt?
A problem that irritates people once a year is a much harder foundation than one that gets in the way every single day. And a problem that’s mildly annoying is very different from one that costs people real time, real money, or real stress. The sweet spot is high frequency combined with genuine pain. That’s where people will pay for a solution, and pay again.
This is underrated. Whenever someone builds a clunky workaround for something: a spreadsheet doing the job of software, a manual process filling in for automation, a group chat acting as a customer service tool; that’s a signal. People don’t build workarounds for problems they can live with. They build them because they have to.
Smart founders keep their eyes open for these moments. They’re everywhere once you start looking.
Spotting a real problem is only part of it. Entrepreneurs who get this right also ask hard questions about the market around that problem. Are there enough people dealing with this? Is this a space that’s been ignored, or is it genuinely unsolvable for a reason?
The best ideas often sit at the intersection of a painful, frequent problem and a market that’s been underserved because solving it was previously too expensive, too slow, or just too hard.
None of this is mystical. The founders who consistently find problems worth solving are curious, they talk to people, and they stay honest about what they’re actually seeing. They resist the urge to fall in love with their own ideas before the evidence is there.
That kind of discipline, more than any particular genius, is what tends to lead somewhere real.